US Disposable Straws
This Freedonia industry study analyzes the $553 million US disposable straw industry. It presents historical demand data (2012, 2017, and 2022) and forecasts (2027 and 2032) by material (conventional plastic, bioplastic, paper, and molded fiber) and market (foodservice, consumer/retail, and beverage packaging).
Free Sample Report
Request a free sample of this report and our team will email it to you.
Report Overview
-
Conventional plastic straws continue to be replaced by new alternatives
-
Paper, bioplastic, and molded fiber straws all expected to see strong growth
This Freedonia industry study analyzes the $553 million US disposable straw industry.  It presents historical demand data (2012, 2017, and 2022) and forecasts (2027 and 2032) by material (conventional plastic, bioplastic, paper, and molded fiber) and market (foodservice, consumer/retail, and beverage packaging). The study also evaluates company market share and competitive analysis on key industry competitors including Hoffmaster Group (Aardvark), D&W Fine Pack, WinCup, Pactiv Evergreen, and Fuling.
Featuring 56 tables and 16 figures – available in Excel and Powerpoint! Learn More This report includes data from 2012-2032 in 5 year intervals and tables featuring year-by-year data for 2019-2026.
The US market for disposable straws continues to face unprecedented disruption, with the lingering impact of the COVID-19 pandemic, sustainability initiatives, and bans on single-use plastics all combining to escalate changes in volume usage, pricing, and the types of materials used in produce straws. Foodservice is by far the largest market for straws and will continue to have an outsized impact on overall straw industry trends.
Demand for disposable straws is forecast to grow 1.5% annually to $597 million in 2027. However, this growth rate hides two opposing underlying trends:
- Growth in average prices will be supported by a transition from conventional plastics to higher value materials such as paper and bioplastics and this will support growth in market value.
- Demand in unit terms will decline as sustainability-driven efforts and bans aim to reduce or eliminate straw use.
Sustainability Becomes the Major Factor in Straw Choices
Historically, straw end users have generally valued performance and cost over sustainability in purchasing decisions. However, growing public awareness of the negative impacts of small plastic items like straws and expansion of single-use plastics bans have made plastic straws a target of sustainability initiatives, especially among foodservice leaders whose products are in the spotlight. This has resulted in:- a strong push toward using biodegradable alternatives – such as paper, molded fiber, and bioplastics – instead of polypropylene
- efforts to reduce usage by only providing straws upon request or eliminating straws altogether by using alternatives such as strawless lids
New Materials Compete for Market Share as Conventional Plastic is Phased Out
As more consumers recognize the negative environmental effects of conventional plastic straws, they will continue to be replaced by new alternatives that have entered the market. However, there has yet to be a clear leader in the race to replace conventional plastic.Initially, paper and polylactic acid (PLA) bioplastic straws were the most available products. However, paper’s performance issues inhibited early adoption while PLA received criticism for its lack of biodegradability. As a result, newer materials such as molded fiber and polyhydroxyalkanoate (PHA) bioplastic have recently entered the market, aiming to provide both good performance and strong environmental profiles.
US Straw Production Ramps Up as Alternative Materials Flourish
Historically, straws have largely been manufactured in Asia (mostly in China) and imported to the US. While straws can be expensive to ship long distances, China’s large low cost plastics industry allowed the country to be a dominant player in the US market despite shipping costs. However, plastic straw bans in China combined with temporary US tariffs led to an increase in domestic production, especially for paper and bioplastic straws.Historical Market Trends
At its broadest level, demand for disposable straws is driven by trends in foodservice revenue, which is an indicator of the number of meals eaten away from home and the amount spent on those meals. Growth in foodservice activity in turn is dependent on a number of macroeconomic and demographic factors including:- the health of the overall economy and levels of disposable income, which impact the ability of consumers to spend on more expensive restaurant meals (compared to home cooking)
- changes in the population mix, especially in terms of age cohorts (such as young adults) that are likely to eat out more often
- trends in consumer spending, including spending on travel and entertainment, which impact foodservice sales at hotels and sports and recreation venues
- the share of total restaurant orders that are provided via drive-thru, curbside pickup, carryout, or delivery services
- the presence and diversity of drink options, as straws are mainly used for cold beverages such as soft drinks, iced coffee, and smoothies
- social factors such as health concerns, which not only influence the amount consumers eat out but their decision on whether to use a straw
- sustainability initiatives, which impact the overall level of straws used as well as the types of materials used
- regulations, especially restrictions on single-use plastics which often include straws
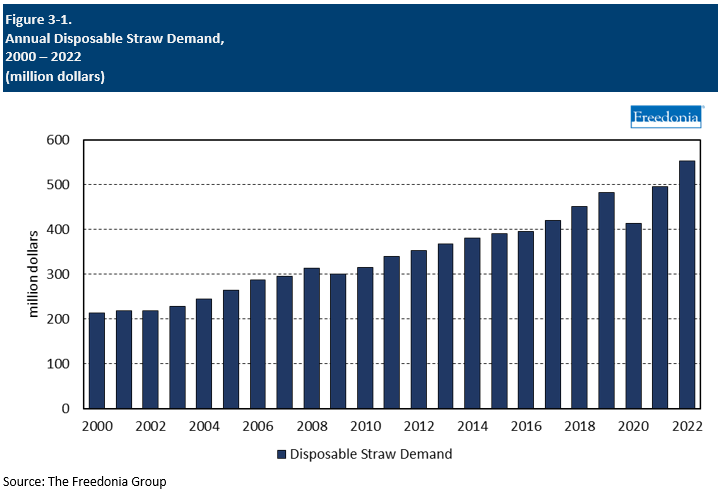
Straw usage fell sharply in 2020 as the COVID-19 pandemic limited restaurant sales, with especially large losses in the full service restaurant and bar segment. While straw demand grew in 2021 and 2022 this was solely due to recovery in the foodservice sector, as use of straws per order continued to decline.
Demand by Material
Disposable straws can be made of a variety of materials including:- conventional plastics, mainly polypropylene
- bioplastics, such as polylactic acid (PLA) and polyhydroxyalkanoate (PHA)
- paper
- molded fiber from sugarcane, bamboo, wheat straw, and other plant sources
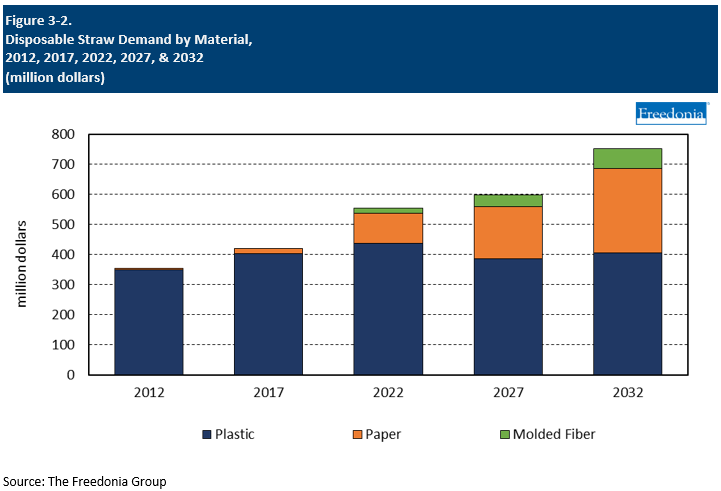
- Plastic will continue to be the primary material used in the straw industry due to its combination of low cost and good performance. While demand for straws made from polypropylene and other conventional plastics will decline, overall use of plastic will be supported by strong growth in demand for bioplastic straws.
- Paper straw demand will continue to register above average growth as paper replaces conventional plastic straws in all markets. However, growth will lag that of other alternative straw materials due to the poor customer response to some early product introductions. Paper straw producers are working to address performance issues and develop improved adhesives and coatings that do not prevent biodegradability.
- Molded fiber straws are the newest entrant to the disposable straw market. Molded fiber straws have good market growth potential as they effectively balance sustainability and performance. However, prices need to decline in order for these straws to see widespread adoption.
Pricing Trends
The disposable straws industry is competitive, and product pricing is a significant factor in customer purchasing decisions. Factors influencing prices for disposable straws include:
- raw material and labor costs
- shipping and transportation costs
- supply and demand balances
- customization, design, and printing costs
- changes in the material mix
- increasing participation in and corresponding competition from products made of newer and more innovative materials
- import competition
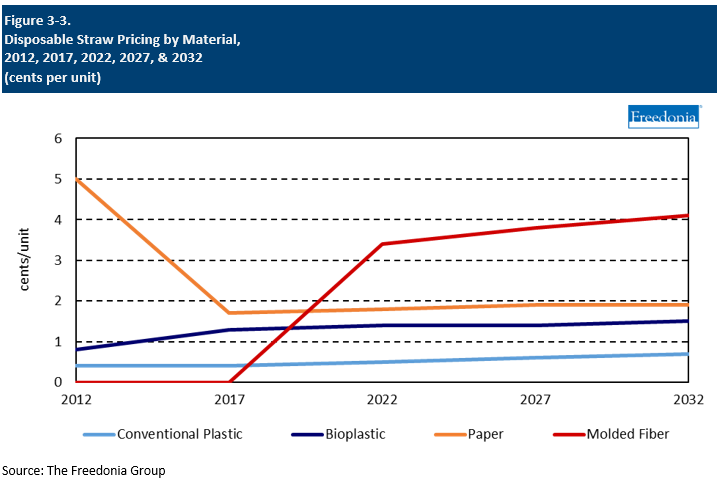
- The price of plastic straws is largely determined by the price of polypropylene, which, in turn, is affected by crude oil and natural gas prices.
- Paper straw prices are linked to the price of bleached and unbleached kraft paper and food grade paper.
The US market for disposable straws continues to face unprecedented disruption, with the lingering impact of the COVID-19 pandemic, sustainability initiatives, and bans on single-use plastics all combining to escalate changes in volume usage, pricing, and the types of materials used in produce straws. Foodservice is by far the largest market for straws and will continue to have an outsized impact on overall straw industry trends.
Demand for disposable straws is forecast to grow 1.5% annually to $597 million in 2027. However, this growth rate hides two opposing underlying trends:
- Growth in average prices will be supported by a transition from conventional plastics to higher value materials such as paper and bioplastics and this will support growth in market value.
- Demand in unit terms will decline as sustainability-driven efforts and bans aim to reduce or eliminate straw use.
Sustainability Becomes the Major Factor in Straw Choices
Historically, straw end users have generally valued performance and cost over sustainability in purchasing decisions. However, growing public awareness of the negative impacts of small plastic items like straws and expansion of single-use plastics bans have made plastic straws a target of sustainability initiatives, especially among foodservice leaders whose products are in the spotlight. This has resulted in:- a strong push toward using biodegradable alternatives – such as paper, molded fiber, and bioplastics – instead of polypropylene
- efforts to reduce usage by only providing straws upon request or eliminating straws altogether by using alternatives such as strawless lids
New Materials Compete for Market Share as Conventional Plastic is Phased Out
As more consumers recognize the negative environmental effects of conventional plastic straws, they will continue to be replaced by new alternatives that have entered the market. However, there has yet to be a clear leader in the race to replace conventional plastic.Initially, paper and polylactic acid (PLA) bioplastic straws were the most available products. However, paper’s performance issues inhibited early adoption while PLA received criticism for its lack of biodegradability. As a result, newer materials such as molded fiber and polyhydroxyalkanoate (PHA) bioplastic have recently entered the market, aiming to provide both good performance and strong environmental profiles.
US Straw Production Ramps Up as Alternative Materials Flourish
Historically, straws have largely been manufactured in Asia (mostly in China) and imported to the US. While straws can be expensive to ship long distances, China’s large low cost plastics industry allowed the country to be a dominant player in the US market despite shipping costs. However, plastic straw bans in China combined with temporary US tariffs led to an increase in domestic production, especially for paper and bioplastic straws.Historical Market Trends
At its broadest level, demand for disposable straws is driven by trends in foodservice revenue, which is an indicator of the number of meals eaten away from home and the amount spent on those meals. Growth in foodservice activity in turn is dependent on a number of macroeconomic and demographic factors including:- the health of the overall economy and levels of disposable income, which impact the ability of consumers to spend on more expensive restaurant meals (compared to home cooking)
- changes in the population mix, especially in terms of age cohorts (such as young adults) that are likely to eat out more often
- trends in consumer spending, including spending on travel and entertainment, which impact foodservice sales at hotels and sports and recreation venues
- the share of total restaurant orders that are provided via drive-thru, curbside pickup, carryout, or delivery services
- the presence and diversity of drink options, as straws are mainly used for cold beverages such as soft drinks, iced coffee, and smoothies
- social factors such as health concerns, which not only influence the amount consumers eat out but their decision on whether to use a straw
- sustainability initiatives, which impact the overall level of straws used as well as the types of materials used
- regulations, especially restrictions on single-use plastics which often include straws
Straw usage fell sharply in 2020 as the COVID-19 pandemic limited restaurant sales, with especially large losses in the full service restaurant and bar segment. While straw demand grew in 2021 and 2022 this was solely due to recovery in the foodservice sector, as use of straws per order continued to decline.

Demand by Material
Disposable straws can be made of a variety of materials including:- conventional plastics, mainly polypropylene
- bioplastics, such as polylactic acid (PLA) and polyhydroxyalkanoate (PHA)
- paper
- molded fiber from sugarcane, bamboo, wheat straw, and other plant sources
- Plastic will continue to be the primary material used in the straw industry due to its combination of low cost and good performance. While demand for straws made from polypropylene and other conventional plastics will decline, overall use of plastic will be supported by strong growth in demand for bioplastic straws.
- Paper straw demand will continue to register above average growth as paper replaces conventional plastic straws in all markets. However, growth will lag that of other alternative straw materials due to the poor customer response to some early product introductions. Paper straw producers are working to address performance issues and develop improved adhesives and coatings that do not prevent biodegradability.
- Molded fiber straws are the newest entrant to the disposable straw market. Molded fiber straws have good market growth potential as they effectively balance sustainability and performance. However, prices need to decline in order for these straws to see widespread adoption.

Pricing Trends
The disposable straws industry is competitive, and product pricing is a significant factor in customer purchasing decisions. Factors influencing prices for disposable straws include:
- raw material and labor costs
- shipping and transportation costs
- supply and demand balances
- customization, design, and printing costs
- changes in the material mix
- increasing participation in and corresponding competition from products made of newer and more innovative materials
- import competition
- The price of plastic straws is largely determined by the price of polypropylene, which, in turn, is affected by crude oil and natural gas prices.
- Paper straw prices are linked to the price of bleached and unbleached kraft paper and food grade paper.

- Executive Summary
- Figure 1-1. Disposable Straws Market Outlook
- About This Report
- Report Details
- Study Scope & Product Description
- Impact of COVID-19 Pandemic
- Table | Annual Disposable Straw Demand by Material, 2019 - 2023
- Figure 2-1. Annual Disposable Straw Demand, 2020 - 2025
- Overview
- Historical Market Trends
- Table | Disposable Straw Demand, 2012 - 2022
- Figure 3-1. Annual Disposable Straw Demand, 2000 - 2022
- Supply & Demand
- Table | Disposable Straw Supply & Demand, 2012, 2017, 2022, 2027, &2032
- Trends in Materials
- Demand by Material
- Table | Disposable Straw Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Disposable Straw Demand by Material, 2019 - 2026
- Figure 3-2. Disposable Straw Demand by Material, 2012, 2017, 2022, 2027, &2032
- Materials Comparison: Advantages & Disadvantages
- Table | Materials Used in Disposable Straws: Comparison & Key Characteristics
- Demand by Material
- Pricing Trends
- Table | Disposable Straw Pricing by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Disposable Straw Pricing by Material, 2019 - 2026
- Figure 3-3. Disposable Straw Pricing by Material, 2012, 2017, 2022, 2027, &2032
- Global Perspective
- Regional Trends
- Impact of China on Straw Market
- Global Bans & Restrictions
- Historical Market Trends
- Factors Impacting Straws Demand
- Foodservice Industry Trends
- Figure 4-1. Foodservice Revenues by Establishment Type, 2022
- Beverage Consumption
- Figure 4-2. US Soft Drink Production by Product, 2010 - 2025
- Regulations & Product Bans
- Sustainability Initiatives
- Competitive Products: Reusable Straws & No Straw Options
- Figure 4-3. Comparative Growth: Disposable Straws vs. Reusable Straws, 2022 - 2027
- Consumer Preferences
- Reusable Straws
- Table | Ownership of Reusable Straws by Gender, Age Group, Urban vs. Rural Setting, Annual Household Income
- Table | Ownership of Reusable Straws by Material Type, by Gender, Age Group, &Annual Household Income Bracke
- Table | Consumers Who Travel with Reusable Straws by Gender, Age Group, Urban vs. Rural Setting, Annual Hous
- Table | Tendency to Forget Reusable Straws by Gender, Age Group, Urban vs. Rural Setting, Annual Household I
- Disposable Straw Use Habits at Foodservice Establishments
- Table | Consumer Attitudes: Disposable Straw Use Habits by Gender, 2022
- Table | Consumer Attitudes: Disposable Straw Use Habits by Age Group, 2022
- Table | Consumer Attitudes: Disposable Straw Use Habits by Presence of Children in the Home, 2022
- Table | Consumer Attitudes: Disposable Straw Use Habits by Household Income Bracket, 2022
- Straw Material Preferences
- Table | Straw Material Preferences by Gender, 2022
- Table | Straw Material Preferences by Age Group, 2022
- Table | Straw Material Preferences by Presence of Children at Home, 2022
- Table | Straw Material Preferences by Household Income Bracket, 2022
- Attitudes About Plastic Straw Bans
- Table | Consumer Attitudes About Plastic Straw Bans by Gender, 2022
- Table | Consumer Attitudes About Plastic Straw Bans by Age Group, 2022
- Table | Consumer Attitudes About Plastic Straw Bans by Presence of Children at Home, 2022
- Table | Consumer Attitudes About Plastic Straw Bans by Household Income Bracket,2022
- Reusable Straws
- Foodservice Industry Trends
- Plastic Straws
- Product Description: Advantages & Disadvantages
- Materials Trends
- Demand by Material
- Table | Disposable Plastic Straw Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Disposable Plastic Straw Demand by Material, 2019 - 2026
- Figure 5-1. Disposable Plastic Straw Demand by Material, 2012, 2017, 2022, 2027, &2032
- Conventional Plastic Straws
- Table | Conventional Disposable Plastic Straw Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Conventional Disposable Plastic Straw Demand by Market, 2019 - 2026
- Figure 5-2. Conventional Disposable Plastic Straw Demand by Market, 2012, 2017, 2022, 2027, &2032
- Bioplastic Straws (PLA and PHA)
- Table | Disposable Bioplastic Straw Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Disposable Bioplastic Straw Demand by Market, 2019 - 2026
- Figure 5-3. Disposable Bioplastic Straw Demand by Market, 2012, 2017, 2022, 2027, &2032
- Demand by Material
- Demand by Market
- Table | Disposable Plastic Straw Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Disposable Plastic Straw Demand by Market, 2019 - 2026
- Figure 5-4. Disposable Plastic Straw Demand by Market, 2012, 2017, 2022, 2027, &2032
- New Product Development
- Leading Producers
- Paper Straws
- Product Description: Advantages & Disadvantages
- Demand by Market
- Table | Disposable Paper Straw Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Disposable Paper Straw Demand by Market, 2019 - 2026
- Figure 6-1. Disposable Paper Straw Demand by Market, 2012, 2017, 2022, 2027, &2032
- New Product Development
- Leading Producers
- Molded Fiber Straws
- Product Description: Advantages & Disadvantages
- Demand by Market
- Table | Molded Fiber Straw Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Molded Fiber Straw Demand by Market, 2019 - 2026
- Figure 7-1. Molded Fiber Straw Demand by Market, 2012, 2017, 2022, 2027, &2032
- New Product Development
- Leading Producers
- Markets
- Demand by Market
- Table | Disposable Straw Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Disposable Straw Demand by Market, 2019 - 2026
- Figure 8-1. Disposable Straw Demand by Market, 2012, 2017, 2022, 2027, &2032
- Fast Food & Fast Casual Restaurants
- Table | Fast Food & Fast Casual Disposable Straw Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Fast Food & Fast Casual Disposable Straw Demand by Material, 2019 - 2026
- Coffee & Snack Shops
- Table | Coffee & Snack Shop Disposable Straw Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Coffee & Snack Shop Disposable Straw Demand by Material, 2019 - 2026
- Full-Service Restaurants
- Table | Full-Service Restaurant Disposable Straw Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Full-Service Restaurant Disposable Straw Demand by Material, 2019 - 2026
- Other Foodservice Markets
- Table | Other Foodservice Market Disposable Straw Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Other Foodservice Market Disposable Straw Demand by Material, 2019 - 2026
- Consumer Market (Retail Sales)
- Table | Consumer/Retail Disposable Straw Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Consumer/Retail Disposable Straw Demand by Material, 2019 - 2026
- Beverage Packaging (Drink Boxes & Pouches)
- Table | Beverage Packaging Disposable Straw Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Beverage Packaging Disposable Straw Demand by Material, 2012, 2017, 2022, 2027, &2032
- Demand by Market
- Key Suppliers & Market Share
- Industry Composition
- Market Share
- Figure 9-1. US Disposable Straw Market Share by Company, 2022
- Appendix
- Scope
- Table | Relevant Industry Codes
- Table | Relevant HS Codes
- Definitions
- Freedonia Methodology
- Study-Specific Methodology
- Sources
- Associations & Agencies
- Related Studies & Reports
- Macroeconomic Assumptions
- Economic Environment
- Table | Macroeconomic Indicators, 2012, 2017, 2022, 2027, &2032
- Demographic Trends
- Table | Population & Households, 2012, 2017, 2022, 2027, &2032
- Consumer Spending
- Table | Personal Consumption Expenditures & Retail Sales, 2012, 2017, 2022, 2027, &2032
- Retail Sales
- Table | Nondurable Goods Retail Sales, 2012, 2017, 2022, 2027, &2032
- Economic Environment
- Scope
Sustainability has become the greatest factor in the outlook for straw demand in the US.
Demand for disposable plastic straws overall is forecast to decline 2.5% annually to $384 million in 2027.
Demand for reusable straws is estimated to grow roughly 7% to $57 million in 2023.
The top US suppliers of disposable straws include Hoffmaster (Aardvark), D&W Fine Pack, Pactiv Evergreen, WinCup, Berry Global, and Fuling.