US Flexible Food Packaging
This Freedonia industry study analyzes the US market for flexible food packaging. Historical data (2012, 2017, and 2022) and forecasts for 2027 are presented in current US dollars (including inflation) and units. Demand for flexible packaging is provided for food by material, packaging product, food format, and application.
Free Sample Report
Request a free sample of this report and our team will email it to you.
Report Overview
What flexible food packaging products will grow fastest?
-
Vacuum skin packaging
-
Brick packs
This Freedonia industry study analyzes the US market for flexible food packaging. Historical data (2012, 2017, and 2022) and forecasts for 2027 are presented for flexible food packaging demand in current US dollars (including inflation) and units. Demand for flexible packaging is provided for food by material, packaging product, food format (fresh/refrigerated, frozen, canned or dry), and application. The study also evaluates company market share for key suppliers.
Featuring 85 tables and 53 figures – available in Excel and Powerpoint! Learn More
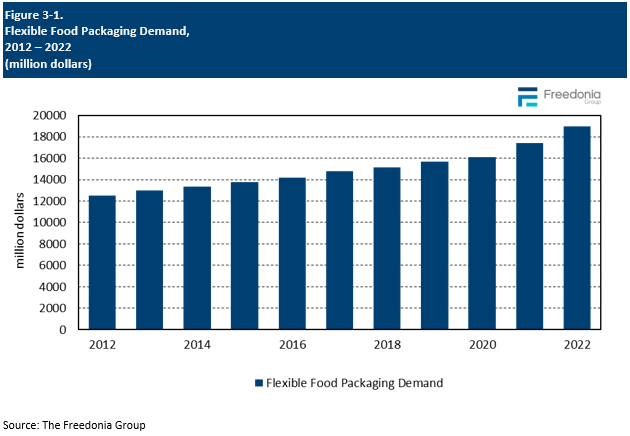
Demand for flexible food packaging is forecast to increase 3.0% per year to $22.0 billion in 2027, with real growth of 1.4% to 225 billion units, above that of food packaging overall. Flexible packaging offers a number of benefits over rigid packaging – including its lighter weight, lower cost, and improved performance – and will continue to penetrate the food packaging market going forward. Nonetheless, food packaging remains a challenging market due to the need to balance cost, performance, sustainability goals, and consumer preferences:
-
High-performance and newer products such as bag-in-box bladders, brick packs, and vacuum skin packaging will experience the strongest advances.
-
Flexible packaging continues to significantly penetrate shelf-stable formats through aseptic and retort pouches and bladders, owing to their lower cost and weight compared to cans.
Meat, Poultry, & Seafood Propel Growth of High-Value Flexible Packaging
Vacuum skin packaging and brick packs – two forms of packaging used almost exclusively with meat, poultry, and seafood products – are expected to grow at the fastest rate of any flexible food packaging product, taking share primarily from wrap (which is used with trays in conventional packaging formats). The unique nature of fresh protein products – their high cost, short shelf life, and sensitivity to temperature and moisture – incentivizes the use of brick packs and skin packaging; despite their higher cost, they improve shelf life and reduce leakage compared to traditional wrap and tray packaging, decreasing food spoilage. These products are also increasingly used in the packaging of the high-growth meat alternatives market, as well as with other fresh, high-cost perishable foods, such as cheese.
Plastic Continues to Dominate Flexible Food Packaging
Despite comprising nearly 90% of total flexible food packaging demand, plastic is expected to continue to see healthy growth going forward due to the variety of advantages it offers, particularly with regard to its performance:
-
Certain high-growth packaging formats – bladders for bag-in-box, brick packs, and skin packaging – can only be made using plastic due to its impermeability, a necessary feature to extend the shelf life of food products.
-
Plastic also benefits from its clarity, allowing consumers to inspect the food before purchase, especially important for fresh applications.
Furthermore, manufacturers of plastic packaging continue to address its poor sustainability image by incorporating recycled content, improving recyclability, reducing plastic used per package, and offering more bioplastic options.
Historical Market Trends
Shifts in demand for food packaging from year to year are determined by a few factors, primarily related to the production and marketing of food products. These activities in turn are influenced by:
-
demographic trends such as age, average household size, and levels of disposable income
-
consumer spending on food and the balance between at-home and away-from-home meals
-
food preferences (e.g., demand for enhanced convenience or for organic products)
-
restaurant and other foodservice industry revenues
In addition, several competitive variables determine the mix of packaging types used and their cost, including:
-
raw material and conversion costs
-
changes in the mix of foods being packaged, particularly in terms of food format (canned, dried, frozen, fresh)
-
trends in packaging size and format, such as shifts toward smaller single-serving packages, family size units, or multipacks
-
the proportion of food that is sold via retail channels versus foodservice establishments
-
environmental and regulatory factors, including trends such as source reduction, the use of recycled content, and recyclability
Food packaging market value growth overall in 2021 and 2022 experienced a strong acceleration in value terms compared to previous years due to the significant inflation following supply chain issues caused by the 2020 pandemic. However, unit growth in those years was below the historical average as consumers facing increased prices opted to cut back on purchases.
Demand by Application
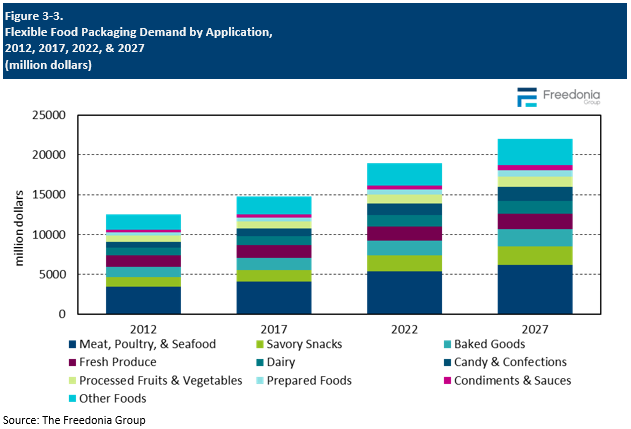
Most food products are packaged in some way before being sold to end users, with some types of fresh produce being one notable exception. The market value of packaging sold for different food applications varies depending on the performance requirements, the volume of packaging needed, and the materials used.
Key food markets for flexible packaging include:
-
meat, poultry, and seafood
-
baked goods
-
snacks
-
dairy
-
candy
-
fresh produce
Demand for flexible food packaging is expected to increase 3.0% per year to $22 billion in 2027, with real growth of 1.4% annually to 225 billion units. Flexible packaging will see solid growth in several applications where conversions from rigid packaging are occurring, much of which involve stand-up pouches or newer product formats like skin packaging.
Meat, poultry, and seafood will remain by far the largest application for flexible food packaging, which benefits from:
-
its low cost and reduced material consumption compared to rigid packaging
-
the effective barrier properties of plastic bags and pouches
-
broad range of packaging available for specific uses (such as cook-in bags)
-
continued conversions to higher value formats such as skin packaging
Savory snacks are the next leading category for flexible packaging, with pouches expected to see healthy growth going forward, especially in the fast-growing nut category owing to their lighter weight compared to traditional plastic jars.
Demand for flexible packaging in baked goods – another significant food application – will be supported by the widespread use of bread bags and inroads by stand-up pouches for products such as cookies.
Although a relatively small application for flexible packaging, prepared foods will see above average gains based on inroads by pouches, particularly stand-up types that offer ample billboard space, an upscale appearance, and resealability.
Yogurt will see good prospects as pouches continue to penetrate the market and take share from cups, jars, and bottles due to their lighter weight and lower cost.
Food Formats
The types of packaging used in the food industry rely heavily on what food is being packaged, especially the technologies used for food preservation. Different food formats require packaging with different performance characteristics based on how the food will be shipped and stored before and after purchase.
The most prevalent food formats are fresh/refrigerated, frozen, canned, and dried/dehydrated, although there are also a few processed foods that are reasonably shelf-stable naturally or through only the use of food preservatives and proper packaging.
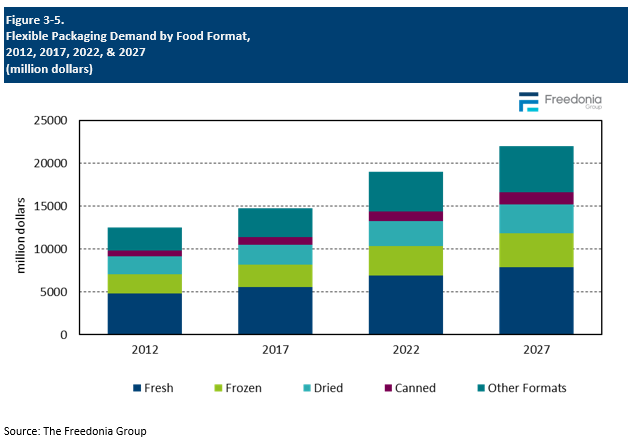
Flexible packaging is used significantly with all food formats, with fresh comprising the largest share due to the size of the fresh meat, poultry, and seafood market. Processed foods that do not require specific formats to maintain shelf-stability – comprising primarily snacks foods such as chips, candy, and cookies – comprise the next leading segments of flexible packaging demand.
Though fresh and frozen foods are the fastest growth food segments overall, the canned format will experience the fastest growth in regard to flexible packaging, owing to the increasing penetration of aseptic and retort pouches and bag-in-box bladders, which are substantially lower cost and weight compared to metal cans.
Pricing Trends
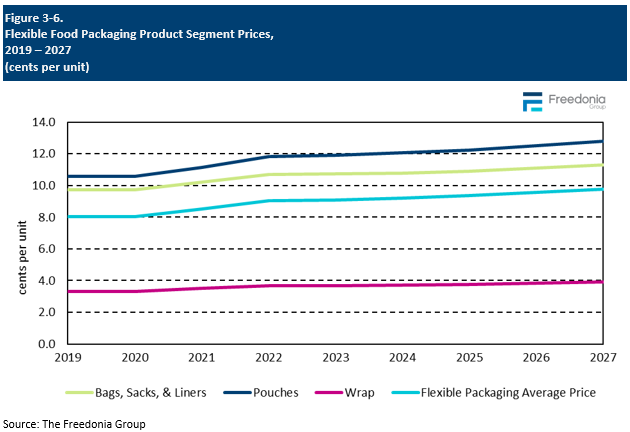
Pricing is an important factor in selecting packaging for a particular food application. Price competition in the food industry is intense, due to the prevalence of relatively low-technology, commodity-type products.
The primary determinant of pricing for flexible food packaging is the cost of raw materials, which typically represent 70% to 80% of the final packaging price.
Other key factors influencing the price of flexible food packaging include:
-
the presence of value-added features such as spouts and reclosable zippers
-
the packaging product mix, both in terms of package size and material composition
-
supply chain pressures – packaging producers are often squeezed between large raw material suppliers on one end and large food processors on the other, leaving them less options for pricing flexibility
-
pressure to improve sustainability, which can result in the use of higher cost packaging materials
In 2021, the price of key raw material inputs used in the production of flexible packaging – plastic, paper, and aluminum foil – increased dramatically due to shortages caused by supply chain issues, leading to a large increase in end pricing of food packaging products. These price increases continued through most of 2022 – with aluminum packaging seeing price growth even into 2023 – though paper and plastic packaging prices have mostly flattened.
Going forward, pricing for flexible packaging is expected to normalize, with the major packaging material categories – plastic and paper – forecast to see price growth mostly in line with historical trends.
Demand for flexible food packaging is forecast to increase 3.0% per year to $22.0 billion in 2027, with real growth of 1.4% to 225 billion units, above that of food packaging overall. Flexible packaging offers a number of benefits over rigid packaging – including its lighter weight, lower cost, and improved performance – and will continue to penetrate the food packaging market going forward. Nonetheless, food packaging remains a challenging market due to the need to balance cost, performance, sustainability goals, and consumer preferences:
-
High-performance and newer products such as bag-in-box bladders, brick packs, and vacuum skin packaging will experience the strongest advances.
-
Flexible packaging continues to significantly penetrate shelf-stable formats through aseptic and retort pouches and bladders, owing to their lower cost and weight compared to cans.
Meat, Poultry, & Seafood Propel Growth of High-Value Flexible Packaging
Vacuum skin packaging and brick packs – two forms of packaging used almost exclusively with meat, poultry, and seafood products – are expected to grow at the fastest rate of any flexible food packaging product, taking share primarily from wrap (which is used with trays in conventional packaging formats). The unique nature of fresh protein products – their high cost, short shelf life, and sensitivity to temperature and moisture – incentivizes the use of brick packs and skin packaging; despite their higher cost, they improve shelf life and reduce leakage compared to traditional wrap and tray packaging, decreasing food spoilage. These products are also increasingly used in the packaging of the high-growth meat alternatives market, as well as with other fresh, high-cost perishable foods, such as cheese.
Plastic Continues to Dominate Flexible Food Packaging
Despite comprising nearly 90% of total flexible food packaging demand, plastic is expected to continue to see healthy growth going forward due to the variety of advantages it offers, particularly with regard to its performance:
-
Certain high-growth packaging formats – bladders for bag-in-box, brick packs, and skin packaging – can only be made using plastic due to its impermeability, a necessary feature to extend the shelf life of food products.
-
Plastic also benefits from its clarity, allowing consumers to inspect the food before purchase, especially important for fresh applications.
Furthermore, manufacturers of plastic packaging continue to address its poor sustainability image by incorporating recycled content, improving recyclability, reducing plastic used per package, and offering more bioplastic options.
Historical Market Trends
Shifts in demand for food packaging from year to year are determined by a few factors, primarily related to the production and marketing of food products. These activities in turn are influenced by:
-
demographic trends such as age, average household size, and levels of disposable income
-
consumer spending on food and the balance between at-home and away-from-home meals
-
food preferences (e.g., demand for enhanced convenience or for organic products)
-
restaurant and other foodservice industry revenues
In addition, several competitive variables determine the mix of packaging types used and their cost, including:
-
raw material and conversion costs
-
changes in the mix of foods being packaged, particularly in terms of food format (canned, dried, frozen, fresh)
-
trends in packaging size and format, such as shifts toward smaller single-serving packages, family size units, or multipacks
-
the proportion of food that is sold via retail channels versus foodservice establishments
-
environmental and regulatory factors, including trends such as source reduction, the use of recycled content, and recyclability
Food packaging market value growth overall in 2021 and 2022 experienced a strong acceleration in value terms compared to previous years due to the significant inflation following supply chain issues caused by the 2020 pandemic. However, unit growth in those years was below the historical average as consumers facing increased prices opted to cut back on purchases.

Demand by Application
Most food products are packaged in some way before being sold to end users, with some types of fresh produce being one notable exception. The market value of packaging sold for different food applications varies depending on the performance requirements, the volume of packaging needed, and the materials used.
Key food markets for flexible packaging include:
-
meat, poultry, and seafood
-
baked goods
-
snacks
-
dairy
-
candy
-
fresh produce
Demand for flexible food packaging is expected to increase 3.0% per year to $22 billion in 2027, with real growth of 1.4% annually to 225 billion units. Flexible packaging will see solid growth in several applications where conversions from rigid packaging are occurring, much of which involve stand-up pouches or newer product formats like skin packaging.
Meat, poultry, and seafood will remain by far the largest application for flexible food packaging, which benefits from:
-
its low cost and reduced material consumption compared to rigid packaging
-
the effective barrier properties of plastic bags and pouches
-
broad range of packaging available for specific uses (such as cook-in bags)
-
continued conversions to higher value formats such as skin packaging
Savory snacks are the next leading category for flexible packaging, with pouches expected to see healthy growth going forward, especially in the fast-growing nut category owing to their lighter weight compared to traditional plastic jars.
Demand for flexible packaging in baked goods – another significant food application – will be supported by the widespread use of bread bags and inroads by stand-up pouches for products such as cookies.
Although a relatively small application for flexible packaging, prepared foods will see above average gains based on inroads by pouches, particularly stand-up types that offer ample billboard space, an upscale appearance, and resealability.
Yogurt will see good prospects as pouches continue to penetrate the market and take share from cups, jars, and bottles due to their lighter weight and lower cost.

Food Formats
The types of packaging used in the food industry rely heavily on what food is being packaged, especially the technologies used for food preservation. Different food formats require packaging with different performance characteristics based on how the food will be shipped and stored before and after purchase.
The most prevalent food formats are fresh/refrigerated, frozen, canned, and dried/dehydrated, although there are also a few processed foods that are reasonably shelf-stable naturally or through only the use of food preservatives and proper packaging.
Flexible packaging is used significantly with all food formats, with fresh comprising the largest share due to the size of the fresh meat, poultry, and seafood market. Processed foods that do not require specific formats to maintain shelf-stability – comprising primarily snacks foods such as chips, candy, and cookies – comprise the next leading segments of flexible packaging demand.
Though fresh and frozen foods are the fastest growth food segments overall, the canned format will experience the fastest growth in regard to flexible packaging, owing to the increasing penetration of aseptic and retort pouches and bag-in-box bladders, which are substantially lower cost and weight compared to metal cans.

Pricing Trends
Pricing is an important factor in selecting packaging for a particular food application. Price competition in the food industry is intense, due to the prevalence of relatively low-technology, commodity-type products.
The primary determinant of pricing for flexible food packaging is the cost of raw materials, which typically represent 70% to 80% of the final packaging price.
Other key factors influencing the price of flexible food packaging include:
-
the presence of value-added features such as spouts and reclosable zippers
-
the packaging product mix, both in terms of package size and material composition
-
supply chain pressures – packaging producers are often squeezed between large raw material suppliers on one end and large food processors on the other, leaving them less options for pricing flexibility
-
pressure to improve sustainability, which can result in the use of higher cost packaging materials
In 2021, the price of key raw material inputs used in the production of flexible packaging – plastic, paper, and aluminum foil – increased dramatically due to shortages caused by supply chain issues, leading to a large increase in end pricing of food packaging products. These price increases continued through most of 2022 – with aluminum packaging seeing price growth even into 2023 – though paper and plastic packaging prices have mostly flattened.
Going forward, pricing for flexible packaging is expected to normalize, with the major packaging material categories – plastic and paper – forecast to see price growth mostly in line with historical trends.

- Executive Summary
- Figure 1-1. Flexible Packaging for Food: Market Outlook
- About This Report
- Report Details
- Study Scope & Product Description
- Figure 2-1. Flexible Food Packaging: Product Examples
- Short-Term Trends
- Table | Annual Flexible Food Packaging Demand by Product, 2020 - 2024
- Figure 2-2. Annual Flexible Food Packaging Demand, 2020 – 2024
- Overview
- Historical Market Trends
- Table | Flexible Food Packaging Demand, 2012 - 2022
- Figure 3-1. Flexible Food Packaging Demand, 2012 - 2022
- Demand by Product
- Table | Flexible Food Packaging Demand by Product, 2012, 2017, 2022, &2027
- Figure 3-2. Flexible Food Packaging Demand by Product, 2012, 2017, 2022, &2027
- Demand by Application
- Table | Flexible Food Packaging Demand by Application, 2012, 2017, 2022, &2027
- Figure 3-3. Flexible Food Packaging Demand by Application, 2012, 2017, 2022, &2027
- Demand by Material
- Table | Flexible Food Packaging Demand by Material, 2012, 2017, 2022, &2027
- Figure 3-4. Flexible Food Packaging Demand by Material, 2012, 2017, 2022, &2027
- Food Formats
- Table | Flexible Packaging Demand by Food Format, 2012, 2017, 2022, &2027
- Figure 3-5. Flexible Packaging Demand by Food Format, 2012, 2017, 2022, &2027
- Fresh Food
- Table | Flexible Packaging Demand for Fresh Food by Product, 2012, 2017, 2022, &2027
- Frozen Food
- Table | Flexible Packaging Demand for Frozen Food by Product, 2012, 2017, 2022, &2027
- Dried Food
- Table | Flexible Packaging Demand for Dried Food by Product, 2012, 2017, 2022, &2027
- Canned Food (Aseptic & Retort)
- Table | Flexible Packaging Demand for Canned (Aseptic & Retort) Food by Product, 2012, 2017, 2022, &2027
- Other Food
- Table | Flexible Packaging Demand for Other Food Formats by Product, 2012, 2017, 2022, &2027
- Pricing Trends
- Table | Selected Flexible Food Packaging Product Prices, 2012, 2017, 2022, &2027
- Figure 3-6. Flexible Food Packaging Product Segment Prices, 2019 - 2027
- Competitive Products
- Figure 3-7. Comparative Value Growth: Flexible vs. Rigid Food Packaging, 2022 - 2027
- Historical Market Trends
- Factors Impacting Food Packaging Demand
- Food Production Trends
- Figure 4-1. Food Shipments, 2000 - 2027
- Food Outlet Trends (Retail vs. Foodservice)
- Figure 4-2. Coronavirus Changes to Food Ordering Patterns & Returning to a Pre-COVID Normal, 2021, 2
- Figure 4-3. Coronavirus Changes to Meal Kit Ordering Patterns & Returning to a Pre-COVID Normal, 202
- Figure 4-4. Coronavirus Changes to Restaurant Ordering Habits & Returning to a Pre-COVID Normal, 202
- Food Retail Channel Trends
- Food Retail Channels
- E-Commerce Sales
- Technology & Innovation
- Sustainability Initiatives
- Sustainability in Packaging
- Recycling & Recycled Content
- Compostability
- Food Waste
- Alternative Materials
- Consumer Perspectives
- Consumer Perspective on Packaging
- Table | Features Consumers Especially Look for When Considering “Sustainable” or “Eco- Friendly” Packing by
- Table | Consumer Attitudes About Recycled Plastics & Biodegradability; By Gender, Age Group, Urban vs. Rural
- Table | Consumer Attitudes About Recycling; By Gender, Age Group, Urban vs. Rural Setting, &Annual Household
- Priority of Features in Food Packaging
- Table | Consumer Attitudes About Priorities of Features in Packaging, 2023
- Consumer Perspective on Packaging
- Food Production Trends
- Flexible Plastic Food Packaging
- Scope & Product Description
- Figure 5-1. Flexible Plastic Food Packaging: Product Examples
- Packaging Products
- Table | Plastic Food Packaging Demand by Product, 2012, 2017, 2022, &2027
- Applications
- Table | Flexible Plastic Food Packaging Demand by Application, 2012, 2017, 2022, &2027
- New Product Development
- Key Suppliers
- Scope & Product Description
- Paper Food Packaging
- Scope & Product Description
- Figure 6-1. Paper Food Packaging: Product Examples
- Packaging Products
- Table | Paper Food Packaging Demand by Product, 2012, 2017, 2022, &2027
- Applications
- Table | Paper Food Packaging Demand by Application, 2012, 2017, 2022, &2027
- New Product Development
- Key Suppliers
- Scope & Product Description
- Small Volume Packaging Materials
- Materials Trends
- Demand by Type
- Table | Smaller Volume Flexible Food Packaging Material Demand by Material, 2012, 2017, 2022, &2027
- Mesh
- Table | Mesh Food Packaging Demand by Application, 2012, 2017, 2022, &2027
- Figure 7-1. Mesh Food Packaging: Product Examples
- Aluminum Foil
- Table | Aluminum Foil Food Packaging Demand by Application, 2012, 2017, 2022, &2027
- Figure 7-2. Aluminum Foil Food Packaging: Product Examples
- Cellulose
- Table | Cellulose Food Packaging Demand by Application, 2012, 2017, 2022, &2027
- Figure 7-3. Cellulose Food Packaging: Product Examples
- Textiles & Nonwovens
- Table | Textile & Nonwoven Food Packaging Demand by Application, 2012, 2017, 2022, &2027
- Figure 7-4. Textile & Nonwoven Food Packaging: Product Examples
- Demand by Type
- Packaging Products
- Table | Small Volume Flexible Food Packaging Materials Demand by Product, 2012, 2017, 2022, &2027
- Applications
- Table | Small Volume Flexible Food Packaging Materials Demand by Application, 2012, 2017, 2022, &2027
- Materials Trends
- Meat, Poultry, &Seafood
- Scope & Product Description
- Table | Industry Codes Related to Meat, Poultry, &Seafood
- Figure 8-1. Meat, Poultry, &Seafood Flexible Packaging: Product Examples
- Packaging Products
- Table | Meat, Poultry, &Seafood: Flexible Packaging Demand by Product, 2012, 2017, 2022, &2027
- Figure 8-2. Meat, Poultry, &Seafood: Comparative Growth for Flexible Packaging Products, 2022 - 2027
- Materials
- Table | Meat, Poultry, &Seafood: Flexible Packaging Demand by Material, 2012, 2017, 2022, &2027
- Applications & Food Formats
- Table | Meat, Poultry, &Seafood: Flexible Packaging Demand by Application & Food Format, 2012, 2017, 2022, &
- New Product Development
- Key Suppliers
- Scope & Product Description
- Savory Snack Foods
- Scope & Product Description
- Table | Industry Codes Related to Savory Snack Foods
- Figure 9-1. Savory Snack Foods Flexible Packaging: Product Examples
- Packaging Products
- Table | Savory Snack Foods: Flexible Packaging Demand by Product, 2012, 2017, 2022, &2027
- Figure 9-2. Savory Snack Foods: Comparative Growth for Flexible Packaging Products, 2022 - 2027
- Materials
- Table | Savory Snack Foods: Flexible Packaging Demand by Material, 2012, 2017, 2022, &2027
- Applications
- Table | Savory Snack Foods: Flexible Packaging Demand by Application, 2012, 2017, 2022, &2027
- New Product Development
- Key Suppliers
- Scope & Product Description
- Baked Goods
- Scope & Product Description
- Table | Industry Codes Related to Baked Goods
- Figure 10-1. Baked Goods Flexible Packaging: Product Examples
- Packaging Products
- Table | Baked Goods: Flexible Packaging Demand by Product, 2012, 2017, 2022, &2027
- Figure 10-2. Baked Goods: Comparative Growth for Flexible Packaging Products, 2022 - 2027
- Materials
- Table | Baked Goods: Flexible Packaging Demand by Material, 2012, 2017, 2022, &2027
- Applications & Food Formats
- Table | Baked Goods: Flexible Packaging Demand by Application & Food Format, 2012, 2017, 2022, &2027
- New Product Development
- Key Suppliers
- Scope & Product Description
- Fresh Produce
- Scope & Product Description
- Figure 11-1. Fresh Produce Flexible Packaging: Product Examples
- Packaging Products
- Table | Fresh Produce: Flexible Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Figure 11-2. Fresh Produce: Comparative Growth for Flexible Packaging Products, 2022 - 2027
- Materials
- Table | Fresh Produce: Flexible Packaging Demand by Material, 2012, 2017, 2022, 2027, &2032
- Applications
- Table | Fresh Produce: Flexible Packaging Demand by Application, 2012, 2017, 2022, &2027
- New Product Development
- Key Suppliers
- Scope & Product Description
- Dairy Products
- Scope & Product Description
- Table | Industry Codes Related to Dairy Products
- Figure 12-1. Dairy Product Flexible Packaging: Product Examples
- Packaging Products
- Table | Dairy Products: Flexible Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Figure 12-2. Dairy Products: Comparative Growth for Flexible Packaging Products, 2022 - 2027
- Materials
- Table | Dairy Products: Flexible Packaging Demand by Material, 2012, 2017, 2022, 2027, &2032
- Applications & Food Formats
- Table | Dairy Products: Flexible Packaging Demand by Application & Food Format, 2012, 2017, 2022, &2027
- New Product Development
- Key Suppliers
- Scope & Product Description
- Candy & Confections
- Scope & Product Description
- Table | Industry Codes Related to Candy & Confections
- Figure 13-1. Candy & Confections Flexible Packaging: Product Examples
- Packaging Products
- Table | Candy & Confections: Flexible Packaging Demand by Product, 2012, 2017, 2022, &2027
- Figure 13-2. Candy & Confections: Comparative Growth for Flexible Packaging Products, 2022 - 2027
- Materials
- Table | Candy & Confections: Flexible Packaging Demand by Material, 2012, 2017, 2022, &2027
- Applications
- Table | Candy & Confections: Flexible Packaging Demand by Application, 2012, 2017, 2022, &2027
- New Product Development
- Key Suppliers
- Scope & Product Description
- Processed Fruits & Vegetables
- Scope & Product Description
- Table | Industry Codes Related to Processed Fruits & Vegetables
- Figure 14-1. Processed Fruits & Vegetables Flexible Packaging: Product Examples
- Packaging Products
- Table | Processed Fruits & Vegetables: Flexible Packaging Demand by Product, 2012, 2017, 2022, &2027
- Figure 14-2. Processed Fruits & Vegetables: Comparative Growth for Flexible Packaging Products, 2022
- Materials
- Table | Processed Fruits & Vegetables: Flexible Packaging Demand by Material, 2012, 2017, 2022, &2027
- Applications & Food Formats
- Table | Processed Fruits & Vegetables: Flexible Packaging Demand by Application & Food Format, 2012, 2017, 2
- New Product Development
- Key Suppliers
- Scope & Product Description
- Prepared Foods
- Scope & Product Description
- Table | Industry Codes Related to Prepared Foods
- Figure 15-1. Prepared Foods Flexible Packaging: Product Examples
- Packaging Products
- Table | Prepared Foods: Flexible Packaging Demand by Product, 2012, 2017, 2022, &2027
- Figure 15-2. Prepared Foods: Comparative Growth for Flexible Packaging Products, 2022 - 2027
- Materials
- Table | Prepared Foods: Flexible Packaging Demand by Product, 2012, 2017, 2022, &2027
- Applications & Food Formats
- Table | Prepared Foods: Flexible Packaging Demand by Application & Food Format, 2012, 2017, 2022, &2027
- New Product Development
- Key Suppliers
- Scope & Product Description
- Sauces & Condiments
- Scope & Product Description
- Table | Industry Codes Related to Sauces, Condiments, Dips, Dressings, &Jelly
- Figure 16-1. Sauce & Condiment Flexible Packaging: Product Examples
- Packaging Products
- Table | Sauces & Condiments: Flexible Packaging Demand by Product, 2012, 2017, 2022, &2027
- Figure 16-2. Sauces & Condiments: Comparative Growth for Flexible Packaging Products, 2022 - 2027
- Materials
- Table | Sauces & Condiments: Flexible Packaging Demand by Material, 2012, 2017, 2022, &2027
- Applications & Food Formats
- Table | Sauces & Condiments: Flexible Packaging Demand by Application & Food Format, 2012, 2017, 2022, &2027
- New Product Development
- Key Suppliers
- Scope & Product Description
- Other Foods
- Scope & Product Description
- Table | Industry Codes Related to Other Foods
- Figure 17-1. Other Foods Flexible Packaging: Product Examples
- Packaging Products
- Table | Other Foods: Flexible Packaging Demand by Product, 2012, 2017, 2022, &2027
- Figure 17-2. Other Foods: Comparative Growth for Flexible Packaging Products, 2022 – 2027
- Materials
- Table | Other Foods: Flexible Packaging Demand by Product, 2012, 2017, 2022, &2027
- Applications & Food Formats
- Table | Other Foods: Flexible Packaging Demand by Application & Food Format, 2012, 2017, 2022, &2027
- New Product Development
- Scope & Product Description
- Bags, Sacks & Liners
- Scope & Product Description
- Figure 18-1. Food Bags, Sacks & Liners: Product Examples
- Demand by Material
- Table | Food Bags, Sacks, &Liners Demand by Material, 2012, 2017, 2022, &2027
- Figure 18-2. Food Bags, Sacks, &Liners Demand by Material, 2012, 2017, 2022, &2027
- Demand by Application
- Table | Food Bags, Sacks, &Liners Demand by Application, 2012, 2017, 2022, &2027
- Figure 18-3. Food Bags, Sacks, &Liners Demand by Application, 2012, 2017, 2022, &2027
- Key Suppliers
- Scope & Product Description
- Pouches
- Scope & Product Description
- Figure 19-1. Food Pouches: Product Examples
- Demand by Product
- Table | Food Pouch Demand by Product, 2012, 2017, 2022, &2027
- Figure 19-2. Food Pouch Demand by Product, 2012, 2017, 2022, &2027
- Demand by Material
- Table | Food Pouch Demand by Material, 2012, 2017, 2022, &2027
- Figure 19-3. Food Pouch Demand by Material, 2012, 2017, 2022, &2027
- Demand by Application
- Table | Food Pouch Demand by Application, 2012, 2017, 2022, &2027
- Figure 19-4. Food Pouch Demand by Application, 2012, 2017, 2022, &2027
- Key Suppliers
- Scope & Product Description
- Wrap
- Scope & Product Description
- Figure 20-1. Food Wrap: Product Examples
- Demand by Material
- Table | Food Wrap Demand by Material, 2012, 2017, 2022, &2027
- Figure 20-2. Food Wrap Demand by Material, 2012, 2017, 2022, &2027
- Demand by Application
- Table | Food Wrap Demand by Application, 2012, 2017, 2022, &2027
- Figure 20-3. Food Wrap Demand by Application, 2012, 2017, 2022, &2027
- Key Suppliers
- Scope & Product Description
- Other Flexible Packaging
- Scope & Product Description
- Figure 21-1. Other Flexible Food Packaging: Product Examples
- Demand by Product
- Table | Other Flexible Food Packaging Demand by Product, 2012, 2017, 2022, &2027
- Figure 21-2. Other Flexible Food Packaging Demand by Product, 2012, 2017, 2022, &2027
- Lidding
- Table | Food Lidding Demand by Material & Application, 2012, 2017, 2022, &2027
- Bag-in-Box Bladders
- Table | Food Bag-in-Box Bladder Demand by Application, 2012, 2017, 2022, &2027
- Chubs
- Table | Food Chub Demand by Application, 2012, 2017, 2022, &2027
- Brick Packs
- Table | Food Brick Pack Demand by Application, 2012, 2017, 2022, &2027
- Vacuum Skin
- Table | Food Vacuum Skin Packaging Demand by Application, 2012, 2017, 2022, &2027
- Interleaving
- Table | Food Interleaving Demand by Application, 2012, 2017, 2022, &2027
- Scope & Product Description
- Key Suppliers & Market Share
- Industry Composition
- Market Share
- Figure 22-1. Flexible Food Packaging Market Share, 2022
- Appendix
- Scope
- Definitions
- Freedonia Methodology
- Study Specific Methodology
- Sources
- Associations & Agencies
- Related Studies & Reports
- Macroeconomic Assumptions
- Economic Environment
- Table | Macroeconomic Indicators, 2012, 2017, 2022, &2027
- Demographic Trends
- Table | Population & Households, 2012, 2017, 2022, &2027
- Consumer Spending
- Table | Personal Consumption Expenditures & Retail Sales, 2012, 2017, 2022, &2027
- Retail Sales
- Table | Nondurable Goods Retail Sales, 2012, 2017, 2022, &2027
- Economic Environment
Manufacturers of plastic packaging continue to address its poor sustainability image by incorporating recycled content, improving recyclability, reducing plastic used per package, and offering more bioplastic options.
Vacuum skin packaging and brick packs – two forms of packaging used almost exclusively with meat, poultry, and seafood products – are expected to grow at the fastest rate of any flexible food packaging product, taking share primarily from wrap (which is used with trays in conventional packaging formats).
The most important factor in the amount of food packaging needed is the outlook for food production, both in terms of the volume produced and the types of food that are popular.
The top four producers of flexible food packaging products include Amcor, SEE, Printpack, and TC Transcontinental.