US Lawn & Garden Robots
This Freedonia industry study analyzes the $63 million US lawn and garden robot industry. It presents historical sales data (2012 through 2022), forecasts (2027 and 2032) in value and unit terms by product and market.
Free Sample Report
Request a free sample of this report and our team will email it to you.
Report Overview
Get the new information on lawn and garden robots.
-
Product innovations will help lawn and garden robots further penetrate the US market
-
New companies, both established and start-ups, continue to enter the US
This Freedonia industry study analyzes the $63 million US lawn and garden robot  It presents historical sales data (2012 through 2022), forecasts (2027 and 2032) in value and unit terms by product (robotic lawn mowers and other lawn and garden robots, which include those used for snow blowing, weeding, and other gardening tasks) and market (consumer and commercial). Annual data and forecasts for 2019 to 2026 are also included. The study provides consumer survey data. The study also analyzes both industry competitors with commercialized products and up and coming companies, including FarmBot, Franklin Robotics, Honda Motor, Husqvarna, iRobot, Toro, LG Electronics, MTD Products, Positec Technology, STIHL, The Kobi Company, and Zucchetti Centro Sistemi."
Featuring 37 tables and 17 figures – available in Excel and Powerpoint! Learn More
Read the blog: Futuristic Lawncare
US sales of lawn and garden robots are forecast to grow at an average rate of 24% per year to roughly 170,000 units in 2027 – valued at $207 million – due to:
- increased adoption in the commercial sector to mitigate labor shortages
- continued innovations that address common challenges in the US market
- a return to the “Do It for Me” (DIFM) lawn service trend following elevated levels of DIY activity during the initial years of the pandemic
Labor Shortages & High-Value Features Spur Rapid Adoption in Commercial Market
The consumer segment will remain the larger market for lawn and garden robots through 2027 as the technology continues to gain popularity among homeowners. However, the commercial market will become increasingly prominent and become the leading market for lawn care robots by 2032. This shift will result from a number of factors:- Recent innovations, including the use of AI technology, advanced vision systems, and wireless boundaries make lawn and garden robots increasingly attractive to commercial landscapers looking to alleviate labor shortages.
- Although there are more units sold in the consumer segment than in the commercial market, professional users are more likely to purchase high-end, advanced models that carry a high price tag.
Return to “Do It for Me” Services to Boost Sales in All Sectors
The COVID-19 pandemic initially curbed consumer interest in hiring professional lawn care due to a combination of stay-at-home orders, telecommuting, and concerns over viral transmission, which created more free time to spend on maintaining their outdoor spaces. With the pandemic waning and conditions normalizing, many consumers with the disposable income to do so are transitioning away from DIY lawn maintenance.Sales of lawn and garden robots in the consumer sector will be supported by those without the time or desire to maintain their own lawns but who do not want to employ a landscaper, especially consumers who have smaller lawns that can be easily maintained by a lawn mower robot. While the high price point of robot lawn mowers in general will limit sales in unit terms to those with enough disposable income to buy them, these products offer long-term cost savings over landscaping services and some traditional gas-powered models, even though the initial cost of the robotic mower may be higher:
- Charging a robotic mower costs less per year than paying for services or fuel.
- Maintenance costs are lower than gas- or electric-powered units, as robotic mowers require less care than traditional models.
The return to DIFM has created an increased demand for professional landscapers. This increasing use of landscaping services, especially amid the current labor shortage, will boost unit sales in the commercial sector, as landscaping businesses and turf management companies turn to robotic equipment to meet the needs of their customers.
Historical Market Trends
The market for lawn and garden robots is dependent on key factors that affect both the consumer and commercial markets, such as the health of the economy and construction activity. With regard to consumer applications – which account for the majority of lawn and garden robot demand – sales of these products are sensitive to fluctuations in:
- personal income levels
- consumer spending
- housing completions
In addition to economic factors, demand for lawn and garden robots can also be significantly impacted by weather patterns and climate change. For example:
- Snow blowers see higher market penetration in regions with colder weather.
- Regions that experience less rainfall and/or see adoption of water-saving landscaping techniques, such as xeriscaping, are less likely to require lawn mowers to maintain grass.
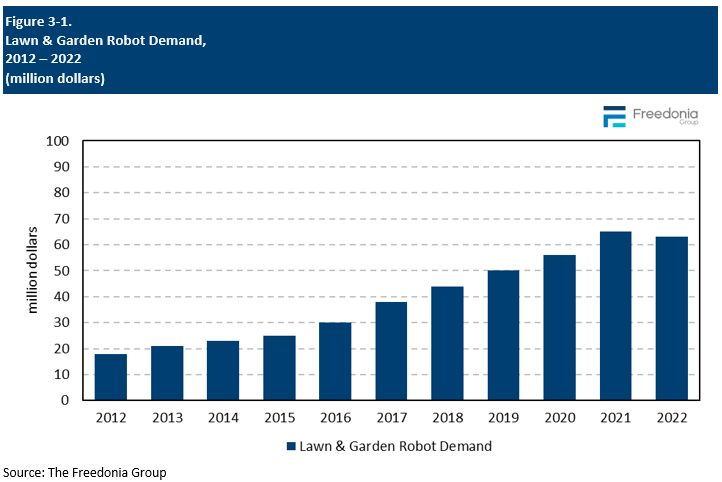
In 2020, demand remained consistent with prior years despite the pandemic, as consumers focused their time, energy, and funds on improving their outdoor spaces, supporting demand gains in the consumer market. In 2021, consumers continued to purchase lawn robots, whether to upgrade existing equipment or buy their first robotic mower as part of the surge in home sales during this time. The commercial segment also saw strong gains as a full year of more normal operations spurred demand from consumers wanting better looking yards.
Pricing Trends
The growing availability of lawn and garden robots and increased competition among suppliers will continue to depress prices. Additionally, manufacturers will continue to look for efficiencies in order to reach competitive price points that can pull customers away from more traditional power lawn and garden equipment.
However, the average prices of lawn and garden robots will remain high compared to traditional lawn and garden equipment due to a number of factors, including:
- innovations in navigation technology, such as units that do not require a boundary wire to function
- the implementation of high-value, crossover technologies from developments in other sectors that use autonomous sensors and equipment, such as home appliances (e.g., vacuums) and self-driving automobiles
- continued development of high-value smart features and robots that have increased connectivity
- advances in battery life and energy efficiency, which increase the range of robotic lawn mowers
Benefits of Lawn & Garden Robots
Considering the current state of technology employed by lawn and garden robots, the products available today have a number of benefits that help distinguish them from competing products.Most importantly, once lawn and garden robot units are installed, they function autonomously, with little human interaction required in most cases. This is beneficial to consumers, like those with a DIFM mentality, who prefer not to spend significant amounts of time or effort on yardwork and, typically, have additional money to spend on helping with these tasks. The ease of use provided by lawn and garden robots is particularly beneficial to older populations and those with busy schedules. Furthermore, as many lawn and garden robots are weatherproof, they can work while the consumer remains dry indoors.
Long-term cost savings is another benefit of lawn and garden robots over more traditional lawn equipment. For example, while the price tag on a robotic mower may be higher than an electric- or gas-powered unit, there are no fuel costs associated with a robotic model. Maintenance costs are also quite a bit lower, and for homeowners, there is no recurring cost for landscaping services.
Moreover, a number of innovations in lawn and garden robots are providing additional benefits, including:
- connectivity to smartphones and other devices, allowing the robots to be controlled and monitored remotely
- rain sensors and weather monitoring that allow the unit to only mow during ideal conditions, avoiding potential jams from wet grass or mowing during periods of low grass growth
- grass sensors that can detect if grass needs to be mowed or if an adjustment to the mowing pattern is needed, saving energy and improving mow quality
- better environmental profile, including reduced air emissions and the elimination of yard clippings
- lower operating costs
- ease of use
- lighter weight
Read the blog: Futuristic Lawncare
US sales of lawn and garden robots are forecast to grow at an average rate of 24% per year to roughly 170,000 units in 2027 – valued at $207 million – due to:
- increased adoption in the commercial sector to mitigate labor shortages
- continued innovations that address common challenges in the US market
- a return to the “Do It for Me” (DIFM) lawn service trend following elevated levels of DIY activity during the initial years of the pandemic
Labor Shortages & High-Value Features Spur Rapid Adoption in Commercial Market
The consumer segment will remain the larger market for lawn and garden robots through 2027 as the technology continues to gain popularity among homeowners. However, the commercial market will become increasingly prominent and become the leading market for lawn care robots by 2032. This shift will result from a number of factors:- Recent innovations, including the use of AI technology, advanced vision systems, and wireless boundaries make lawn and garden robots increasingly attractive to commercial landscapers looking to alleviate labor shortages.
- Although there are more units sold in the consumer segment than in the commercial market, professional users are more likely to purchase high-end, advanced models that carry a high price tag.
Return to “Do It for Me” Services to Boost Sales in All Sectors
The COVID-19 pandemic initially curbed consumer interest in hiring professional lawn care due to a combination of stay-at-home orders, telecommuting, and concerns over viral transmission, which created more free time to spend on maintaining their outdoor spaces. With the pandemic waning and conditions normalizing, many consumers with the disposable income to do so are transitioning away from DIY lawn maintenance.Sales of lawn and garden robots in the consumer sector will be supported by those without the time or desire to maintain their own lawns but who do not want to employ a landscaper, especially consumers who have smaller lawns that can be easily maintained by a lawn mower robot. While the high price point of robot lawn mowers in general will limit sales in unit terms to those with enough disposable income to buy them, these products offer long-term cost savings over landscaping services and some traditional gas-powered models, even though the initial cost of the robotic mower may be higher:
- Charging a robotic mower costs less per year than paying for services or fuel.
- Maintenance costs are lower than gas- or electric-powered units, as robotic mowers require less care than traditional models.
The return to DIFM has created an increased demand for professional landscapers. This increasing use of landscaping services, especially amid the current labor shortage, will boost unit sales in the commercial sector, as landscaping businesses and turf management companies turn to robotic equipment to meet the needs of their customers.
Historical Market Trends
The market for lawn and garden robots is dependent on key factors that affect both the consumer and commercial markets, such as the health of the economy and construction activity. With regard to consumer applications – which account for the majority of lawn and garden robot demand – sales of these products are sensitive to fluctuations in:
- personal income levels
- consumer spending
- housing completions
In addition to economic factors, demand for lawn and garden robots can also be significantly impacted by weather patterns and climate change. For example:
- Snow blowers see higher market penetration in regions with colder weather.
- Regions that experience less rainfall and/or see adoption of water-saving landscaping techniques, such as xeriscaping, are less likely to require lawn mowers to maintain grass.
In 2020, demand remained consistent with prior years despite the pandemic, as consumers focused their time, energy, and funds on improving their outdoor spaces, supporting demand gains in the consumer market. In 2021, consumers continued to purchase lawn robots, whether to upgrade existing equipment or buy their first robotic mower as part of the surge in home sales during this time. The commercial segment also saw strong gains as a full year of more normal operations spurred demand from consumers wanting better looking yards.

Pricing Trends
The growing availability of lawn and garden robots and increased competition among suppliers will continue to depress prices. Additionally, manufacturers will continue to look for efficiencies in order to reach competitive price points that can pull customers away from more traditional power lawn and garden equipment.
However, the average prices of lawn and garden robots will remain high compared to traditional lawn and garden equipment due to a number of factors, including:
- innovations in navigation technology, such as units that do not require a boundary wire to function
- the implementation of high-value, crossover technologies from developments in other sectors that use autonomous sensors and equipment, such as home appliances (e.g., vacuums) and self-driving automobiles
- continued development of high-value smart features and robots that have increased connectivity
- advances in battery life and energy efficiency, which increase the range of robotic lawn mowers
Benefits of Lawn & Garden Robots
Considering the current state of technology employed by lawn and garden robots, the products available today have a number of benefits that help distinguish them from competing products.Most importantly, once lawn and garden robot units are installed, they function autonomously, with little human interaction required in most cases. This is beneficial to consumers, like those with a DIFM mentality, who prefer not to spend significant amounts of time or effort on yardwork and, typically, have additional money to spend on helping with these tasks. The ease of use provided by lawn and garden robots is particularly beneficial to older populations and those with busy schedules. Furthermore, as many lawn and garden robots are weatherproof, they can work while the consumer remains dry indoors.
Long-term cost savings is another benefit of lawn and garden robots over more traditional lawn equipment. For example, while the price tag on a robotic mower may be higher than an electric- or gas-powered unit, there are no fuel costs associated with a robotic model. Maintenance costs are also quite a bit lower, and for homeowners, there is no recurring cost for landscaping services.
Moreover, a number of innovations in lawn and garden robots are providing additional benefits, including:
- connectivity to smartphones and other devices, allowing the robots to be controlled and monitored remotely
- rain sensors and weather monitoring that allow the unit to only mow during ideal conditions, avoiding potential jams from wet grass or mowing during periods of low grass growth
- grass sensors that can detect if grass needs to be mowed or if an adjustment to the mowing pattern is needed, saving energy and improving mow quality
- better environmental profile, including reduced air emissions and the elimination of yard clippings
- lower operating costs
- ease of use
- lighter weight
- Executive Summary
- Figure 1-1. Lawn & Garden Robots Market Outlook
- About This Report
- Report Details
- Study Scope & Product Description
- Short Term Lawn & Garden Robot Trends
- Table | Annual Lawn & Garden Robot Demand by Product, 2019 - 2023
- Figure 2-1. Lawn & Garden Robot Demand, 2018 - 2024
- Overview
- Historical Market Trends
- Table | Lawn & Garden Robot Demand, 2012 - 2022
- Figure 3-1. Lawn & Garden Robot Demand, 2012 - 2022
- Demand by Product
- Table | Lawn & Garden Robot Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Lawn & Garden Robot Demand by Product, 2019 - 2026
- Figure 3-2. Lawn & Garden Robot Demand by Product, 2012, 2017, 2022, 2027, &2032
- Demand by Market
- Overview
- Table | Lawn & Garden Robot Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Lawn & Garden Robot Demand by Market, 2019 - 2026
- Figure 3-3. Lawn & Garden Robot Demand by Market, 2012, 2017, 2022, 2027, &2032
- Consumer
- Table | Consumer Lawn & Garden Robot Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Consumer Lawn & Garden Robot Demand by Product, 2019 - 2026
- Commercial
- Table | Commercial Lawn & Garden Robot Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Commercial Lawn & Garden Robot Demand by Product, 2019 - 2026
- Overview
- Pricing Trends
- Table | Lawn & Garden Robot Pricing by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Lawn & Garden Robot Pricing by Product, 2019 - 2026
- Competitive Products
- Riding Mowers
- Walk-Behind Mowers
- Turf & Grounds Mowers
- Figure 3-4. Comparative Growth: Lawn & Garden Robots & Competitive Products, 2022 - 2027
- Remote-Controlled Lawn & Garden Equipment
- Global Perspective
- Benefits of Lawn & Garden Robots
- Concerns About Lawn & Garden Robots
- Historical Market Trends
- Technology
- What Is a Lawn & Garden Robot?
- Navigation Technologies
- Current Technology & Expected Innovation
- Boundary Wire
- Radio Frequency Identification (RFID)
- GPS
- Ultrasonic Sensors
- LiDAR
- GPS-RTK
- Vision Systems
- Aerial Drones
- Product Development: Features & Innovations
- Improved Batteries
- Solar Power
- Theft Control
- Weatherproof Features
- Modular Features
- Safety Features
- Evolving Control Technologies (Smartphone, Voice, Smartwatch)
- Software & Component Development
- Factors Impacting Lawn & Garden Equipment Demand
- Climate & Weather (Drought & Water Shortages)
- Regulations & Product Standards
- Air Pollution & Emissions Regulations
- Noise Pollution
- Consumer Safety
- Sustainability Initiatives
- Recycling & Recycled Content
- Energy Efficiency
- Consumer Insights
- Consumer Disposable Income & Spending Patterns
- Consumer Awareness of Lawn & Garden Robots
- Consumer Ownership of Lawn & Garden Robots Versus Power Equipment
- Consumer Planned Purchases of Lawn & Garden Robots
- Homeownership Trends
- Ownership vs. Rentals
- Table | US Homeownership & Rental Rates, 2012 - 2022
- Annual Household Income
- Table | US Homeownership & Rental Rates by Household Income Bracket, 2022
- Age of Head of Household
- Table | US Homeownership & Rental Rates by Age of Head of Household, 2012 - 2022
- Ownership vs. Rentals
- Average Lot Size & Outdoor Space Trends
- Lot Size Over Time
- Table | US Homeownership Rates by Property Size, 2012 - 2022
- Lot Size by Locations
- Table | Lot Size Owned by Urban vs. Rural Setting, 2022
- Table | Lot Size Owned by Geographic Region, 2022
- Lot Size Over Time
- Consumer Lawn & Garden Practices
- The Importance of Lawn & Garden Care to Consumers
- Table | "I Enjoy Caring For My Lawn & Garden" by Gender, Age Group, &Household Income Bracket, 2022
- Table | Lawn Maintenance & Gardening Participation Insights, 2022
- Consumer Lawn Mowing Practices
- Table | "Does Your Household Have a Grass Lawn That Needs Mowing?" by Urban vs. Rural Setting, Geographic Re
- Table | Lawn Mowing Consumer Insight by Gender & Age Group, 2022
- Who Performs Lawn & Garden Work at Home?
- Table | Who Performs Lawn & Garden Maintenance Tasks by Age Group, Urban vs. Rural Setting, &Household Incom
- Landscaping Service Preferences
- Table | Consumer Insights on Select Landscaping Services Options by Gender, Age Group, &Household Income Bra
- The Importance of Lawn & Garden Care to Consumers
- Robotic Lawn Mowers
- Timeline of Product Development
- Table | Robotic Lawn Mowers: Timeline of Key Market Developments
- Market Potential
- Product Demand
- Table | Robotic Lawn Mower Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Robotic Lawn Mower Demand by Market, 2019 - 2026
- Figure 6-1. Robotic Lawn Mower Demand by Market, 2012, 2017, 2022, 2027, &2032
- Key Products
- Automower by Husqvarna
- Figure 6-2. Automower by Husqvarna
- WORX Landroid by Positec Technology
- Figure 6-3. WORX Landroid by Positec Technology
- Miimo by Honda Motor
- Figure 6-4. Miimo by Honda Motor
- Robomow by MTD Products
- Figure 6-5. Robomow by MTD Products
- Automower by Husqvarna
- Timeline of Product Development
- Other Lawn & Garden Robots
- Timeline of Product Development
- Table | Other Lawn Care Robots: Timeline of Key Market Developments
- Market Potential
- Product Demand
- Table | Other Lawn & Garden Robot Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Other Lawn & Garden Robot Demand by Market, 2019 - 2026
- Figure 7-1. Other Lawn & Garden Robot Demand by Market, 2012, 2017, 2022, 2027, &2032
- Key Products
- Tertill Weeding Robot by Tertill
- Figure 7-2. Tertill Weeding Robot
- Dandy DT-01 & Dandy DT-01XL Weeding Robots by Dandy Technology
- Figure 7-3. Dandy DT-01XL Weeding Robot
- FarmBot Genesis by FarmBot
- Figure 7-4. FarmBot Genesis
- Yarbo Snow Blower S1 by Yarbo
- Figure 7-5. Yarbo Snow Blower S1
- Tertill Weeding Robot by Tertill
- Timeline of Product Development
- Keys to Future Market Growth
- Key Findings
- Table | Keys to Future Market Growth
- Increase Consumer Awareness
- Consumer Awareness of Lawn & Garden Robots Remains Low
- Grow Awareness Through Marketing Initiatives
- Target Marketing at High-Potential Demographics
- Continue Product Development
- Potential Developments
- Improve Mowing Range & Efficiency
- Improved Mowing Capabilities
- Innovate Navigation Technologies
- Expand Product Offerings Beyond Lawn Mowers
- Robots That Perform Other Lawn & Garden Functions Need Development
- Crowdfunding for Start-Up Robot Manufacturers
- Consider Crossover Products That Can Be Used by a Range of Markets
- Integrated Garden Systems Help Broaden Product Lines
- Compete Against Traditional Mowers & Services
- Competition from Traditional Mowers & Services Restrains Robot Sales
- Offer More Entry-Level Units
- Multifunctional & Modular Robots
- Build Service Programs & Work with Service Providers
- Design Products for Commercial Applications
- Commercial Market for Lawn & Garden Robots Remains Underdeveloped
- Create Products with Landscapers in Mind
- Continue to Innovate Robotic Lawn Mowers for Golf Courses & Recreational Spaces
- Key Findings
- Key Suppliers & Market Share
- Key Findings
- Industry Composition
- Market Share/Market Participants
- Mergers & Acquisitions
- Table | Selected Mergers & Acquisitions
- Appendix
- Scope
- Table | Relevant Industry Codes
- Table | Relevant HS Codes
- Definitions
- Freedonia Methodology
- Study-Specific Methodology
- Sources
- Associations & Agencies
- Related Studies & Reports
- Macroeconomic Assumptions
- Economic Environment
- Table | Macroeconomic Indicators, 2012, 2017, 2022, 2027, &2032
- Demographic Trends
- Table | Population & Households, 2012, 2017, 2022, 2027, &2032
- Housing Stock
- Table | Housing Stock by Type, 2012, 2017, 2022, 2027, &2032
- Figure 10-1. Housing Stock: Share by Year of Construction, 2022
- Economic Environment
- Scope
Unlike other industries, the COVID-19 pandemic had a positive effect on the lawn and garden robots industry in 2020. While initial financial uncertainty counteracted some trends seen in the pre-pandemic years, such as the increasing use of DIFM landscaping, stay-at-home orders soon spurred more consumers to invest in their outdoor spaces.
Looking forward to 2023, sales of lawn and garden robots are expected to rise to $76 million as supply chain problems ease and inflation is tamed.
Sales of lawn and garden robots are expected to grow to $207 million in 2027 or around 170,000 units.
The main outlets for lawn and garden robots are consumer users, who represented 84% of sales in 2022.