US Converted Flexible Packaging Report
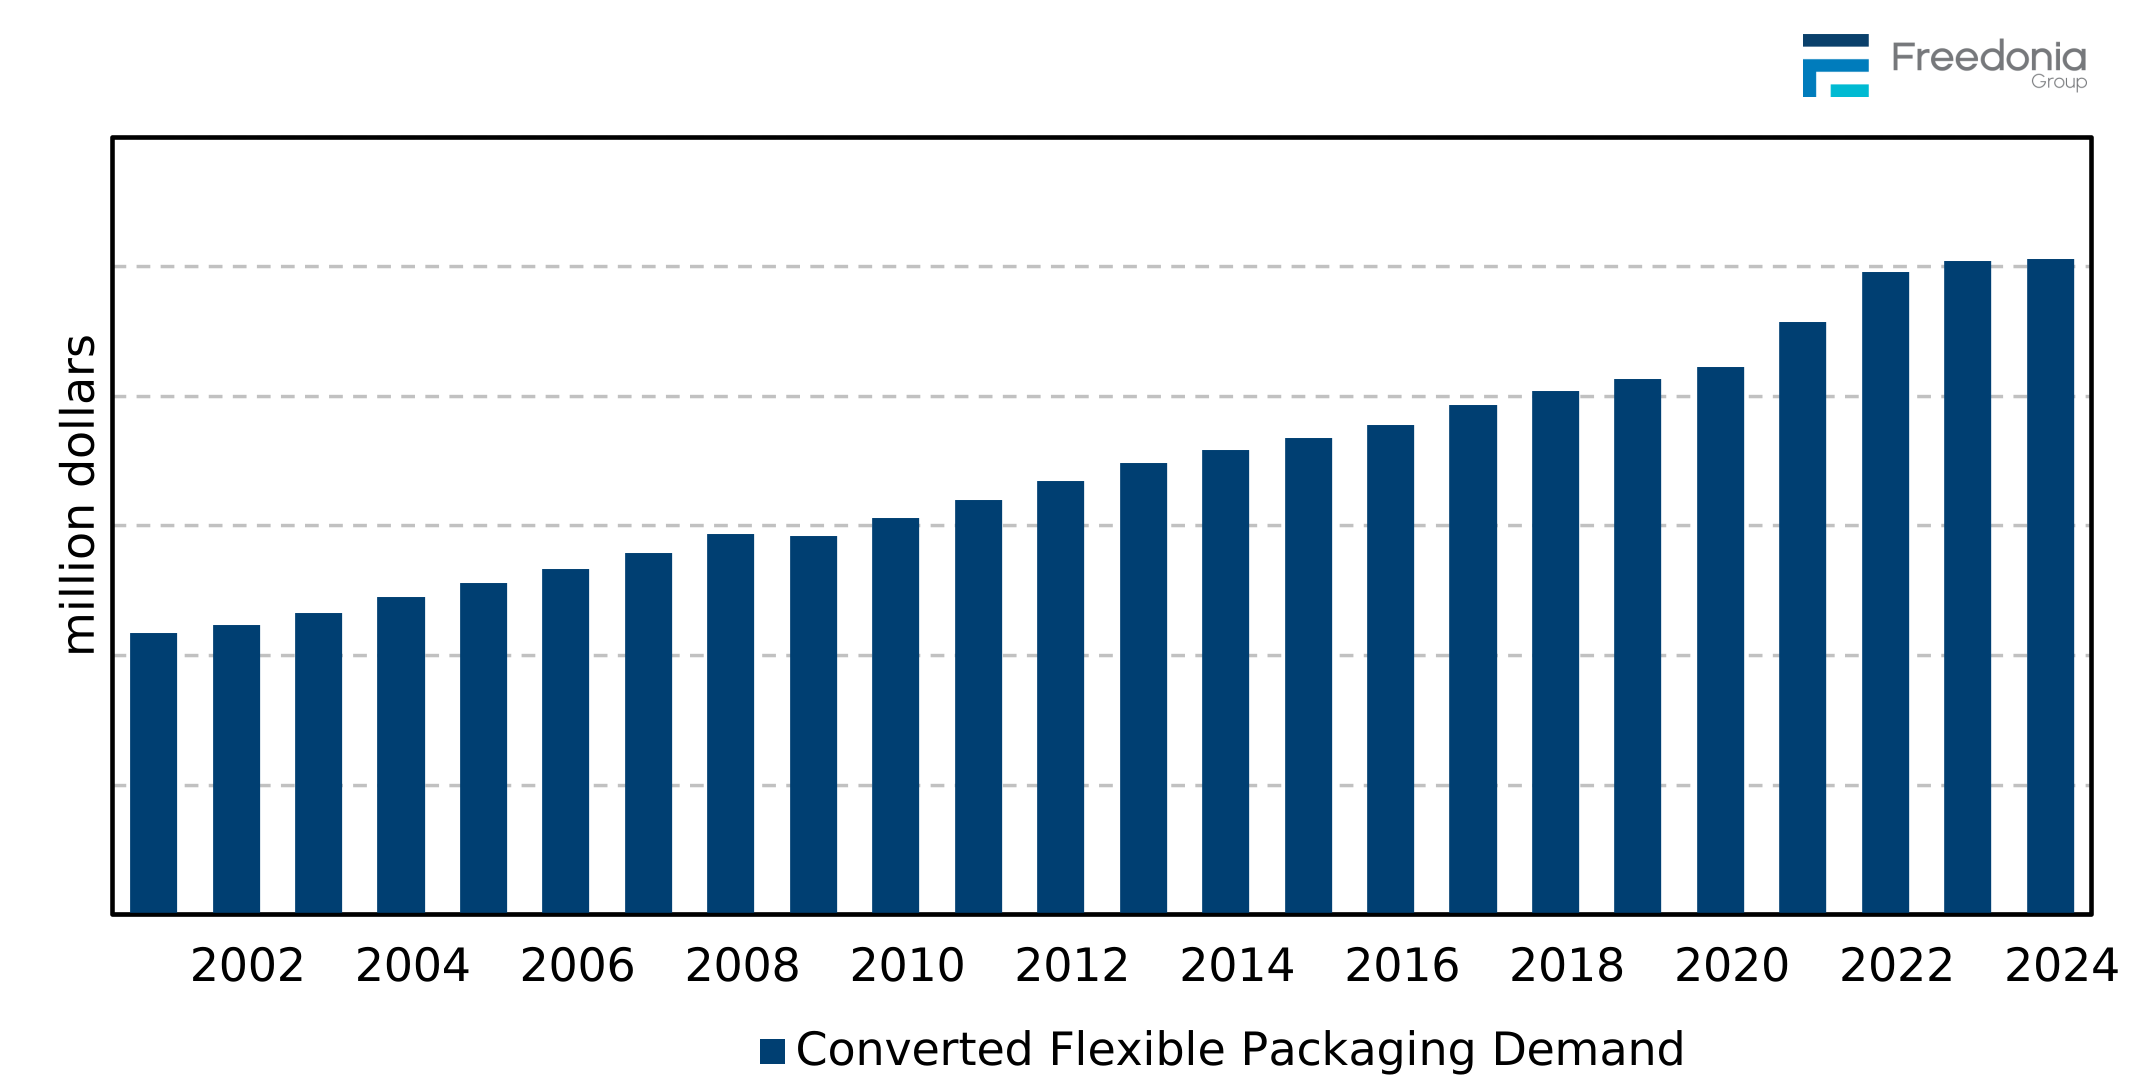
The US Converted Flexible Packaging market is expected to grow from $25.3 billion in 2024 to $29.2 billion by 2029, driven by sustainability trends, premium features, and expanding nonfood applications. Key industry shifts include a move towards recyclable and compostable materials and the increasing demand for high-barrier and resealable packaging
Free Sample Report
Request a free sample of this report and our team will email it to you.
Report Overview
US Flexible Packaging Market Advances Amid Cost, Equipment, and Sustainability Pressures
High upfront equipment investments, evolving material requirements, and consumer scrutiny of plastic waste are reshaping strategies in key growth categories such as pouches and skin packaging
Key Themes Covered in this Report:
- How sustainability mandates and consumer expectations are accelerating the shift to recyclable, compostable, and monomaterial flexible packaging
- Why growth in ready-to-eat meals, on-the-go snacking, and e-commerce is boosting demand for lightweight, resealable, and high-barrier flexible packaging formats
- The evolving role of flexible packaging in food, beverage, and pharmaceutical markets—balancing performance advantages with equipment investment needs and competition from alternative formats
Featuring 112 Tables & 73 Figures
Demand for converted flexible packaging reached $25.3 billion in 2024 and is forecast to increase 2.9% per year to $29.2 billion in 2029. Growth will be driven by:
- sustainability pressures, which are driving a shift to higher-value recyclable and compostable materials to meet EPR mandates and reduce regulatory costs
- the increasing popularity of premium features, such as high-barrier and resealable products
- faster growth in nonfood markets as flexible packaging gains share in household, pet care, and durable goods applications
Sustainability Pressures Are Accelerating Material Redesign
Extended Producer Responsibility (EPR) laws and rising retailer expectations are forcing a shift away from non-recyclable, multi-material laminates. Flexible packaging producers are responding by developing recyclable monomaterials and compostable formats that align with real-world recovery systems. While there will be steady growth across all product types, future competitiveness will depend on how successfully producers pivot to monomaterial and compostable options – particularly for pouches and bags, which make up the bulk of market demand. The regulatory environment is not only a risk factor but also a driver of long-term product transformation.
Value Over Volume: Premium Features Power Flexible Packaging Revenue
While volume gains will be steady, much of the industry’s recent revenue growth has come from higher per-pound pricing. This reflects rising input costs, but also greater use of value-added features such as resealability, high-quality graphics, and eco-friendly materials. As market expansion slows, packaging producers will need to differentiate not through scale alone but through functional and sustainable enhancements that justify premium pricing.
Nonfood Markets Offer New Growth Opportunities
As packaging requirements evolve, flexible packaging continues to expand beyond its traditional base in food markets. While food will remain the largest outlet for converted flexible packaging, nonfood applications are expected to increase their share of the market. Growth will be supported by greater use of flexible formats in household products, pet food, and consumer durables, where light weight, durability, and shipping efficiency are valued, particularly in e-commerce and omnichannel distribution. Products like chubs and skin packaging are also gaining popularity due to their protective properties and ability to enhance product presentation.
US Converted Flexible Packaging Report Details
| Current Total Market Size | $36.4 billion |
| Forecast Total Market Growth Rate | 2.9% CAGR from 2024-2029 |
| Historical Period | 2014-2024 |
| Forecast Period | 2024-2034 |
| Units Covered | Revenue in million USD (inflation-adjusted) and million units |
| Regions | United States |
| Countries Individually Covered | United States |
| Products | Pouches, bags, wrap |
| Markets | Food, nonfood |
| Materials | Plastic, paper, aluminum foil |
| Point Where Data is Measured | Manufacturer’s Level |
| Additional Elements | Market Share in Total, Near Term Trend Analysis, Regulatory Trends, Mergers & Acquisitions, Sustainability Initiatives |
Leading Companies Driving Trends in the US ConvertedFlexible Packaging Industry
| Amcor | Novolex |
| American Packaging | PPC Flexible Packaging |
| Bryce Corporation | Printpack |
| C-P Flexible | ProAmpac |
| CDF Corporation | Sealed Air |
| Constantia Flexibles | Sigma Plastics Group |
| Five Star | TC Transcontinental |
| Hood Companies | Tekni-Plex |
| Toppan | Winpak |
| Mondi Group |
What Drives Flexible Packaging Demand in the US?
Demand for converted flexible packaging on a year-to-year basis is determined by a number of factors, primarily those related to the production and marketing of packaged goods. These activities, in turn, are influenced by:
- demographic trends such as age, average household size, and levels of disposable income
- the health of the overall economy
- changes in consumer incomes and spending on retail products
- changes in industrial production, especially in key sectors that rely on packaging for safety or product protection such as pesticides, construction materials, adhesives or coatings
In addition, a number of competitive variables determine the mix of packaging types used and their costs, including:
- competition from rigid packaging
- raw material costs and availability
- changes in the mix of products being packaged
- trends in packaging size and format, such as shifts toward smaller, single-use packages; family size units; or multipacks
- sustainability initiatives, including source reduction, the use of recycled content, and recyclability
- growth in e-commerce and packaging requirements for direct-to-consumer shipping
- consumer preferences based on factors such as convenience or functionality
- regulations such as extended producer liability (EPR) laws or restrictions on the use of certain types of packaging
- technological innovations making certain types of packaging more competitive
Converted Flexible Packaging Report Scope
This report analyzes the US converted flexible packaging market.
- Flexible packaging is defined as packaging made of flexible or easily yielding materials that can readily change shape – even when filled or closed.
- Flexible packaging is produced from paper, plastic film, aluminum foil, textiles, mesh, cellulose, or any combination of these materials.
- Products made from mixed materials are categorized by their primary material. For instance, a foil-lined plastic bag would be considered a plastic bag.
Nearly all flexible packaging is converted in some way from basic film, paper, or foil raw materials to create finished, functional packaging solutions. Converting operations include:
- cutting or slitting into individual units
- coating
- waxing
- laminating
- printing
- fabrication of bags, pouches, and other preformed packages
Flexible packaging products covered in the scope of this report include:
- bags and sacks, including liners
- pouches
- wrap
- other flexible packaging (such as skin packaging, chubs, lidding, strip packs, interleaving, flexible baking, candy and pastry cups and liners, and a variety of other flexible packages)
This study focuses on primary and secondary packaging and excludes most bulk and transit packaging. Other products excluded from the scope of this report include:
- foodservice disposable packaging, such as sandwich wrap or stretch wrap
- grocery store bags on a roll used in deli, produce or bakery departments
- household and institutional plastic storage bags
- flexible intermediate bulk containers (FIBCs)
- labels including shrink sleeve labels
- mailing envelopes (mailers)
- money bags
- novelty bags
- pallet wrap
- paper yard waste and refuse sacks
- protective packaging, such as bubble packaging or paper fill
- retail bags, also known as shopping bags, grocery bags, or merchandise bags
- rollstock
- sausage casings
- semi-rigid packaging
- stretch and shrink film for transport packaging
- tape
- trash bags
For packaging products that contain both flexible and rigid components, only the flexible portion of the package is counted in the scope of this report. For example, for bag-in-box systems only the flexible bladder is included here and for vacuum skin packaging only the flexible film components would be included.
Market segments are segmented by food and nonfood.
Food markets include:
- meat, poultry, and seafood
- baked goods
- snack food
- fresh produce
- candy and confections
- dairy products
- other foods, such as processed fruits and vegetables, grain mill products, baby food, coffee and tea, sauces and condiments, dry mixes, sugar, energy bars, spices, soups meal replacements and protein shakes, cannabis-infused foods, and meat alternatives
Nonfood markets include:
- pharmaceuticals
- medical products
- agricultural and horticultural
- pet food
- beverages
- chemicals
- paper and textile products
- rack and counter
- other nonfood (includes building materials, personal care products, auto chemicals, plastic and rubber products, tobacco products, leather goods, furniture, military supplies, and books)
Materials are segmented by:
- plastic
- paper
- aluminum foil
- other materials, including textiles, mesh, and cellophane
| NAICS 2017 North American Industry Classification System | SIC Standard Industrial Classification | ||
|---|---|---|---|
| 322220 | Paper Bag and Coated and Treated Paper Manufacturing | 2671 | Packaging Paper and Plastics Film, Coated and Laminated |
| 326111 | Plastics Bag and Pouch Mfg | 2672 | Coated and Laminated Paper, NEC |
| 326112 | Plastics Packaging Film and Sheet (including Laminated) Mfg | 2673 | Plastics, Foil, and Coated Paper Bags |
| 2674 | Uncoated Paper and Multiwall Bags | ||
| 3497 | Metal Foil and Leaf | ||
- Executive Summary
- Figure 1-1. US Converted Flexible Packaging Market
- Short-Term US Flexible Packaging Market Analysis (2022-2026)
- Economic Forecast
- Table | Macroeconomic Indicators, 2023, 2024, 2025, &2026 (billion 2017 dollars & billion dollars)
- Recent Market Growth in the Flexible Packaging Industry
- Figure 2-1. Annual Converted Flexible Packaging Demand, 2022 - 2026 (% annual change)
- Converted Flexible Packaging Products & Markets (2022-2026)
- Table | Annual Converted Flexible Packaging Demand by Product & Market, 2022 - 2026 (million dollars & milli
- Figure 2-2. Converted Flexible Packaging Demand by Product, 2022 - 2026 (million dollars)
- Economic Forecast
- Overview & Key Findings
- Study Scope: What is Converted Flexible Packaging?
- Figure 3-1. Converted Flexible Packaging: Product Examples
- Historical Market Trends & Growth Drivers
- What Drives Flexible Packaging Demand in the US?
- Converted Flexible Packaging Market Growth 2014-2024
- Table | Converted Flexible Packaging Demand, 2014 - 2024 (million dollars & million pounds)
- Figure 3-2. Converted Flexible Packaging Demand, 2001 - 2024 (million dollars)
- Flexible Packaging Product Summary
- What Factors Impact the Type of Flexible Packaging Used?
- Growth Outlook for Flexible Packaging in the US: Market Drivers & Restraints
- Table | Converted Flexible Packaging Demand by Product, 2014, 2019, 2024, 2029, &2034 (million dollars & mil
- Table | Annual Converted Flexible Packaging Demand by Product, 2021 - 2028 (million dollars & million pounds
- Comparative Growth Outlook for Flexible Packaging Products
- Figure 3-3. Comparative Value Demand Growth for Flexible Packaging Products, 2024 - 2029 (% CAGR)
- Flexible Packaging Markets Overview
- Table | Converted Flexible Packaging Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars & mill
- Table | Annual Converted Flexible Packaging Demand by Market, 2021 - 2028 (million dollars & million pounds)
- Figure 3-4. Converted Flexible Packaging Demand by Market, 2014, 2019, 2024, 2029, &2034 (million do
- Pricing & Inflation
- Factors that Impact Converted Flexible Packaging Pricing
- Impact of Recent Price Inflation on the Flexible Packaging Industry
- Forecast Growth in Converted Flexible Packaging Prices by Product
- Table | Converted Flexible Packaging Prices for Select Products, 2014, 2019, 2024, 2029, &2034 (dollars per
- Table | Annual Converted Flexible Packaging Prices for Select Products, 2021 - 2028 (dollars per pound & cen
- Figure 3-5. Selected Converted Flexible Packaging Pricing, 2014 - 2029 (cents per unit)
- Study Scope: What is Converted Flexible Packaging?
- Factors Impacting Flexible Packaging Demand
- Economic & Manufacturing Outlook in the US
- Figure 4-1. US Manufacturers’ Shipments, 2014 - 2029 (billion 2017 dollars)
- Competition with Rigid Packaging: A Constant Cycle of Innovation
- Technology & Product Innovation Key to Market Success
- Barrier Properties & Challenge to Reduce Mixed Material Use
- Aqueous Barrier Solutions
- Convenience & Performance Remain Key Features
- Machinery Investment & Production Innovation Key to Profitability
- Customization & Industrial Internet of Things (IIoT) Automation
- Growth in E-Commerce Impacting Packaging Product Mix
- Turning Compliance into Competitive Advantage for Flexible Packaging
- Sustainability Initiatives Drive Market Change
- Source Reduction
- Recycling & Recycled Content: Can Flexible Packaging Meet New Goals?
- Biodegradable Packaging Development Continues to be a Challenge
- Compostable Packaging Is Key Opportunity but Faces Roadblocks
- Extended Producer Responsibility (EPR)
- Consumer Preferences and Packaging Choice: Survey Trends
- Packaging is Important to Grocery Shopping Consumers
- Table | Attitudes About the Importance of Packaging When Making Grocery Shopping Choices by Gender & Age Gro
- Reclosable Packaging Preferences
- Table | Packaging Features: Consumer Preference for Reclosable Packaging by Gender & Age Group, 2024 (percen
- Eco-Friendly Packaging Preferences
- Table | Packaging Features: Consumer Opinions on Eco-Friendly Packaging by Gender, Age Group, &Income Level
- Table | Packaging Features: Consumer Opinions on the Priority of Eco-Friendly Packaging Features, 2024 (perc
- Microwavable or Cook-In Packaging Options: Consumers are Conflicted
- Table | Packaging Features: Consumer Use of Microwavable Packaging by Gender & Age Group, 2024 (percent of r
- Protection of Package Contents Important to Consumers
- Table | Packaging Features: Consumer Opinion on Protection Offered by Rigid vs. Flexible Packaging: by Gende
- Consumer Attitudes Toward Recycling & Environmental Responsibility
- Table | Consumer Insights: Attitudes on Recycling & Waste by Gender & Age Group, 2024 (percent of respondent
- How Consumers Rate Material Sustainability
- Table | Consumer Insights: Sustainability Views by Material, 2024 (percent of respondents)
- Packaging is Important to Grocery Shopping Consumers
- Economic & Manufacturing Outlook in the US
- Pouches
- Scope & Product Description
- Flat vs. Stand-Up Pouches: What’s the Difference?
- Figure 5-1. Pouches: Product Examples
- Value-Added Features Enhance Functionality
- Flat vs. Stand-Up Pouches: What’s the Difference?
- Materials Trends
- Competition Intensifies Among Pouch Materials
- Table | Pouch Demand by Material, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Figure 5-2. Pouch Demand by Material, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Plastic Pouch Demand Dependent on Performance & New Barrier Solutions
- Paper Pouches & the Sustainability Opportunity
- Rethinking Barriers: The Rise of Monomaterial Pouches
- Competition Intensifies Among Pouch Materials
- Markets Overview
- Demand by Market
- Table | Pouch Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars & million units)
- Figure 5-3. Pouch Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Food Markets for Pouches
- Table | Food Pouch Demand by Application, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Nonfood Markets for Pouches
- Table | Nonfood Pouch Demand by Application, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Demand by Market
- Leading Suppliers
- Scope & Product Description
- Bags, Sacks, &Liners
- Scope & Product Description
- Figure 6-1. Bags, Sacks, &Liners: Product Examples
- Materials Trends
- Paper vs. Plastic
- Table | Bag Demand by Material, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Figure 6-2. Bag Demand by Material, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Plastic Bags: Sustained Dominance Amid Sustainability Pressure
- The Role of Paper Bags in a Changing Market
- Mesh, Textile & Cellophane Bags: Niche Applications Sustain Demand
- Paper vs. Plastic
- Markets Overview
- Demand by Market
- Table | Bag Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars & million units)
- Figure 6-3. Bag Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Food Markets
- Table | Food Bag Demand, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Nonfood Markets
- Table | Nonfood Bag Demand, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Demand by Market
- Leading Suppliers
- Scope & Product Description
- Wrap
- Scope & Product Description
- Figure 7-1. Packaging Wrap: Product Examples
- Materials Trends
- Table | Wrap Demand by Material, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Figure 7-2. Wrap Demand by Material, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Markets Overview
- Demand by Market
- Table | Wrap Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Figure 7-3. Wrap Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Food Markets
- Table | Food Wrap Demand, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Nonfood Markets
- Table | Nonfood Wrap Demand, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Demand by Market
- Leading Suppliers
- Scope & Product Description
- Small Volume Flexible Packaging Formats
- Scope & Product Description
- Figure 8-1. Small Volume Converted Flexible Packaging: Product Examples
- Materials Trends
- Table | Small Volume Converted Flexible Packaging Demand by Material, 2014, 2019, 2024, 2029, &2034 (million
- Figure 8-2. Small Volume Converted Flexible Packaging Demand by Material, 2014, 2019, 2024, 2029, &2
- Markets Overview
- Table | Small Volume Converted Flexible Packaging Demand by Market, 2014, 2019, 2024, 2029, &2034 (million d
- Table | Food Markets for Small Volume Converted Flexible Packaging, 2014, 2019, 2024, 2029, &2034 (million d
- Table | Nonfood Markets for Other Converted Flexible Packaging, 2014, 2019, 2024, 2029, &2034 (million dolla
- Figure 8-3. Small Volume Flexible Packaging Product Demand by Market, 2014, 2019, 2024, 2029, &2034
- Product Trends
- Demand by Product
- Table | Small Volume Converted Flexible Packaging Demand by Product, 2014, 2019, 2024, 2029, &2034 (million
- Figure 8-4. Small Volume Converted Flexible Packaging Demand by Product, 2014, 2019, 2024, 2029, &20
- Lidding
- Table | Flexible Lidding Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Figure 8-5. Lidding Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Strip Packs
- Table | Strip Pack Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Figure 8-6. Strip Pack Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Chubs
- Table | Chub Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Figure 8-7. Chub Demand by Market, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Skin Packaging
- All Other Converted Flexible Packaging
- Table | All Other Converted Flexible Packaging Demand by Market, 2014, 2019, 2024, 2029, &2034 (million doll
- Figure 8-8. All Other Converted Flexible Packaging Demand by Market, 2014, 2019, 2024, 2029, &2034 (
- Demand by Product
- Leading Suppliers
- Scope & Product Description
- Food Markets for Flexible Packaging
- Market Scope
- Materials Trends
- Table | Converted Flexible Food Packaging by Material, 2014, 2019, 2024, 2029, &2034 (million pounds)
- Figure 9-1. Converted Flexible Food Packaging by Material, 2014, 2019, 2024, 2029, &2034 (million po
- Product Trends
- Table | Converted Flexible Food Packaging by Packaging Type, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Figure 9-2. Converted Flexible Food Packaging by Packaging Type, 2014, 2019, 2024, 2029, &2034 (mill
- Demand by Market
- Table | Converted Flexible Food Packaging by Market, 2014, 2019, 2024, 2029, &2034 (million dollars)
- Figure 9-3. Converted Flexible Food Packaging by Market, 2014, 2019, 2024, 2029, &2034 (million doll
- Meat, Poultry, &Seafood
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Meat, Poultry, &Seafood
- Table | Advantages & Disadvantages of Flexible Packaging for Meat, Poultry, &Seafood
- Figure 9-4. Meat, Poultry, &Seafood: Flexible Packaging Examples
- Market Outlook & Product Trends
- Table | Meat, Poultry, &Seafood: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 20
- Figure 9-5. Meat, Poultry, &Seafood: Converted Flexible Packaging Demand by Packaging, 2014, 2019, 2
- Suppliers
- Table | Selected Meat, Poultry, &Seafood Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Baked Goods
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Baked Goods
- Table | Baked Goods: Converted Flexible Packaging Products Used
- Figure 9-6. Baked Goods: Packaging Examples
- Market Outlook & Product Trends
- Table | Baked Goods: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &2034 (m
- Figure 9-7. Baked Goods: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 20
- Suppliers
- Table | Selected Baked Goods Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Snack Foods
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Snack Foods
- Table | Snack Foods: Converted Flexible Packaging Products Used
- Figure 9-8. Snack Foods: Packaging Examples
- Market Outlook & Product Trends
- Table | Snack Food: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &2034 (mi
- Figure 9-9. Snack Food: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 202
- Suppliers
- Table | Selected Snack Foods Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Fresh Produce
- Market Scope & Packaging Requirements
- Table | Advantages & Disadvantages of Flexible Packaging for Fresh Produce
- Figure 9-10. Fresh Produce: Packaging Examples
- Market Outlook & Product Trends
- Table | Fresh Produce: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &2034
- Figure 9-11. Fresh Produce: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024,
- Suppliers
- Table | Selected Fresh Produce Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Candy & Confections
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Candy & Confections
- Table | Candy & Confections: Converted Flexible Packaging Products Used
- Figure 9-12. Candy & Confections: Packaging Examples
- Market Outlook & Product Trends
- Table | Candy & Confections: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029,
- Figure 9-13. Candy & Confections: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019,
- Suppliers
- Table | Selected Candy & Confections Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Dairy Products
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Dairy Products
- Table | Dairy Products: Converted Flexible Packaging Products Used
- Figure 9-14. Dairy Products: Packaging Examples
- Market Outlook & Product Trends
- Table | Dairy Products: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &2034
- Figure 9-15. Dairy Products: Converted Flexible Packaging Demand by Packaging Type,, 2014, 2019, 202
- Suppliers
- Table | Selected Dairy Foods Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Other Foods
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Other Foods
- Table | Other Food: Applications for Converted Flexible Packaging Products
- Figure 9-16. Other Food Markets: Flexible Packaging Examples
- Market Outlook & Product Trends
- Table | Other Foods: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &2034 (m
- Figure 9-17. Other Foods: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2
- Suppliers
- Table | Selected Other Food Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Nonfood Markets for Flexible Packaging
- Market Scope
- Materials Trends
- Table | Nonfood Markets for Converted Flexible Packaging by Material, 2014, 2019, 2024, 2029, &2034 (million
- Figure 10-1. Converted Flexible Nonfood Packaging Demand by Material, 2014, 2019, 2024, 2029, &2034
- Product Trends
- Table | Converted Flexible Nonfood Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &2034 (millio
- Figure 10-2. Converted Flexible Nonfood Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029,
- Demand by Application
- Table | Converted Flexible Nonfood Packaging Demand by Application, 2014, 2019, 2024, 2029, &2034 (million d
- Pharmaceuticals
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Pharmaceuticals
- Table | Pharmaceuticals: Characteristics & Advantages of Converted Flexible Packaging Products
- Figure 10-3. Pharmaceuticals: Packaging Examples
- Market Outlook & Product Trends
- Table | Pharmaceuticals: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &203
- Figure 10-4. Pharmaceuticals: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 202
- Suppliers
- Table | Selected Pharmaceutical Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Medical Products
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Medical Products
- Table | Medical Products: Characteristics & Applications of Converted Flexible Packaging Products
- Figure 10-5. Medical Products: Packaging Examples
- Market Outlook & Product Trends
- Table | Medical Products: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &20
- Figure 10-6. Medical Products: Converted Flexible Packaging Demand by Packaging Type 2014, 2019, 202
- Suppliers
- Table | Selected Medical Product Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Agriculture & Horticulture
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Agriculture & Horticulture
- Table | Agriculture & Horticulture: Characteristics & Applications of Converted Flexible Packaging Products
- Figure 10-7. Agriculture & Horticulture: Packaging Examples
- Market Outlook & Product Trends
- Table | Agriculture & Horticulture: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024,
- Figure 10-8. Agriculture & Horticulture: Converted Flexible Packaging Demand by Packaging Type, 2014
- Suppliers
- Table | Selected Agriculture & Horticulture Product Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Pet Food
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Pet Food
- Table | Pet Food: Characteristics, Advantages & Disadvantages of Converted Flexible Packaging
- Figure 10-9. Pet Food: Packaging Examples
- Market Outlook & Product Trends
- Table | Pet Food: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &2034 (mill
- Figure 10-10. Pet Food: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 202
- Suppliers
- Table | Selected Pet Product Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Paper & Textiles
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Paper & Textile Products
- Table | Paper & Textile Products: Characteristics & Applications of Converted Flexible Packaging Products
- Figure 10-11. Paper & Textiles: Packaging Examples
- Market Outlook & Product Trends
- Table | Paper & Textiles: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &20
- Figure 10-12. Paper & Textiles: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2
- Suppliers
- Table | Selected Paper & Textiles Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Beverages
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Beverages
- Figure 10-13. Beverages: Packaging Examples
- Market Outlook & Product Trends
- Table | Beverages: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &2034 (mil
- Figure 10-14. Beverages: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 20
- Suppliers
- Table | Selected Beverage Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Chemicals
- Market Scope & Packaging Requirements
- Table | Industry Codes Related to Chemicals
- Table | Chemicals: Characteristics of Converted Flexible Packaging Products
- Figure 10-15. Chemicals: Packaging Examples
- Market Outlook & Product Trends
- Table | Chemicals: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &2034 (mil
- Figure 10-16. Chemicals: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 20
- Suppliers
- Table | Selected Chemical Packaging Producers & Flexible Product Offerings
- Market Scope & Packaging Requirements
- Rack & Counter
- Market Scope & Packaging Requirements
- Table | Rack & Counter: Competition from Rigid Packaging Formats
- Figure 10-17. Rack & Counter: Packaging Examples
- Market Outlook & Product Trends
- Table | Rack & Counter: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 2024, 2029, &2034
- Figure 10-18. Rack & Counter: Converted Flexible Packaging Demand by Packaging Type, 2014, 2019, 202
- Suppliers
- Market Scope & Packaging Requirements
- Other Nonfood
- Market Scope & Packaging Requirements
- Table | Other Nonfood Markets: Advantages of Converted Flexible Packaging Products
- Figure 10-19. Other Nonfood Markets: Packaging Examples
- Market Outlook & Product Trends
- Table | Other Nonfood Products: Converted Flexible Packaging Demand by Packaging Type & Application, 2014, 2
- Figure 10-20. Other Nonfood Products: Converted Flexible Packaging Demand by Product, 2014, 2019, 20
- Suppliers
- Market Scope & Packaging Requirements
- Flexible Packaging Raw Materials
- Key Raw Materials Used in Flexible Packaging
- Raw Materials Consumption: Volume Trends through 2029
- Table | Converted Flexible Packaging Demand by Material, 2014, 2019, 2024, 2029, &2034 (million pounds)
- Figure 11-1. Converted Flexible Packaging Demand by Material, 2014, 2019, 2024, 2029, &2034 (million
- Plastic Film
- Figure 11-2. Plastic Film Raw Material Volume Growth, 2014 - 2034 (% CAGR)
- Paper
- Figure 11-3. Paper Raw Material Volume Growth, 2014 - 2034 (% CAGR)
- Aluminum Foil
- Figure 11-4. Aluminum Foil Raw Material Volume Growth, 2014 - 2034 (% CAGR)
- Other Materials (Textiles, Mesh, &Cellophane)
- Figure 11-5. Other Raw Materials Volume Growth, 2014 - 2034 (% CAGR)
- Industry Structure
- Key Findings & Industry Composition
- Table | US Converted Flexible Packaging Sales by Company, 2024 (million dollars)
- Market Share
- Figure 12-1. US Converted Flexible Packaging Market Share by Company, 2024 (billion dollars)
- Figure 12-2. US Converted Flexible Packaging Market: Leading Supplier, 2024
- Figure 12-3. US Converted Flexible Packaging Market: Second Leading Supplier, 2024
- Figure 12-4. US Converted Flexible Packaging Market: Third Leading Supplier, 2024
- Figure 12-5. US Converted Flexible Packaging Market: Fourth Leading Supplier, 2024
- Mergers & Acquisitions
- Table | Selected Mergers & Acquisitions
- List of Industry Participants
- Table | Selected Industry Participants
- Key Findings & Industry Composition
- Appendix
- Report Details
- Table | Relevant Industry Codes
- Definitions
- Abbreviations
- Table | Abbreviations & Acronyms Used in Study
- Freedonia Methodology
- Study-Specific Methodology
- Sources
- Associations & Agencies
- Related Studies & Reports
- Macroeconomic Assumptions
- Economic Environment
- Table | Macroeconomic Indicators, 2014, 2019, 2024, 2029, &2034 (billion 2017 dollars)
- Demographic Trends
- Table | Population & Households, 2014, 2019, 2024, 2029, &2034 (million persons)
- Personal Consumption Expenditures
- Table | Personal Consumption Expenditures, 2014, 2019, 2024, 2029, &2034 (billion dollars)
- Manufacturers’ Shipments
- Table | Manufacturers’ Shipments 2014, 2019, 2024, 2029, &2034 (billion dollars)
- Economic Environment
- Report Details
The US flexible packaging industry is expected to grow nearly 3% per year through 2029
The most widely used flexible packaging products in the United States include pouches, bags, and wrap
Some of the leading flexible packaging converters in the United States include Amcor, Constantia Flexibles, Novolex, Printpack, ProAmpac, and Sealed Air.