Frozen Food Packaging
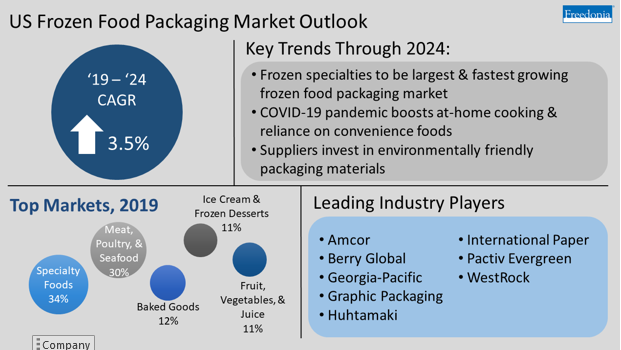
Demand for frozen food packaging is forecast to increase 3.5% per year to $8.8 billion in 2024.
Free Sample Report
Request a free sample of this report and our team will email it to you.
Report Overview
Featuring 91 tables and 50 figures – now available in Excel and Powerpoint! Learn More
This study analyzes the market for frozen food packaging. Historical (2009, 2014 and 2019) data and forecasts to 2024 are presented in current dollars.
Shifts in demand for frozen food packaging from year to year are determined by a number of factors, primarily:
- the production of and demand for frozen food, which in turn are driven by:
- consumer spending and food preferences (e.g., demand for enhanced convenience)
- demographic trends such as age, average household size, and levels of disposable income
- restaurant and other foodservice industry revenues
- competitive variables determining the mix of packaging types used, including raw material and conversion costs and trends toward smaller portions such as single-servings and multipacks
- environmental and regulatory factors, including a growing emphasis on source reduction and recyclability
Applications covered include:
- frozen specialty foods:
- appetizers
- breakfast foods such as waffles, pancakes, French toast, and toaster pastries
- breakfast sandwiches
- entrées
- frozen dinners
- hand-held entrées
- plant-based meat alternative products
- pizzas such as pizza pies, slices, flatbreads, pizza pockets, and pizza rolls,
- side dishes
- soups
- whipped toppings
- meat, poultry, and seafood, including fresh, unprepared item as well as further processed types, such as breaded poultry and seafood:
- meat (including beef and veal, pork, and lamb) as well as meat products marketed as breakfast meats
- poultry (chicken, turkey, and other products such as goose and duck)
- seafood (all fish and shellfish)
- frozen baked goods, including:
- bagels
- biscuits
- bread rolls and loaves
- cakes, cheesecakes, and cake bites
- cheese and sweet rolls
- cinnamon rolls
- cookies and brownies
- dough and batters (cookie, pastry, filo)
- eclairs and other pastries
- flan, custard, crème brûlée
- muffins
- pie and pizza crusts
- pies
- rolls
- tarts
- tortillas
- fruit, vegetables, and juice:
- plain vegetables and fruit products
- prepared frozen vegetables, such as breaded onion rings, mushrooms and eggplant, veggie pastas, and mashed cauliflower
- juice concentrates – including 100% juice concentrates and juice drink concentrates (e.g., lemonade and fruit punch)
- French fries, which are considered a potato product
- ice cream and other frozen desserts:
- hard and soft ice cream
- hard and soft frozen yogurt
- sherbet
- sorbet
- gelato
- frozen custard
- flavored ices
- ice cream cakes
- ice cream novelties (i.e., single-serve units of any of the above)
- other frozen foods, including (e.g., sauces, baby food, pet food, cocktail mixers, nondairy creamers, liquid eggs, herbs, drink mixes)
For the purposes of this study, entrées are distinguished from dinners in that they do not generally contain a complete meal. Excluded from this segment are hand-held entrées, which are included in the Other Frozen Specialties segment.
Excluded from the scope of this study are:
- packaged ice
- frozen carryout
- meal delivery program foods
- shelf-stable products that are frozen after purchase
Packaging product segments covered include:
- aluminum foil packaging:
- including containers as well as lidding
- excluding laminated foil and paper bags – such as those used for frozen bread—which are in the paper segment
- bags
- boxes (e.g., folding cartons – also known as folding paperboard boxes – corrugated boxes, gable top cartons)
- chubs
- lidding film:
- including plastic film lidding (typically made from one or more layers of plastics such as PET or PP), paper lidding, and aluminum foil lidding
- excluding paper and plastic lids sold together with accompanying paper or plastic containers as well as plastic overwrap and shrink wrap
- paperboard sleeves, including paperboard sleeves used as outer packaging and paperboard susceptor sleeves
- plastic containers:
- including clamshells, domed containers, two-piece plastic containers, cans, pails, bottles, and jars as well as lids sold with the container
- excluding composite cans (which are considered a rigid paper and paperboard product for the purposes of this study) as well as plastic tubs, cups, bowls, and separately sold lids
- pouches, including:
- flat (e.g., pillow, four-side seal, and three-side seal)
- stand-up, including round-bottom/Doyen, K-seal, corner-bottom, flat-bottom
- trays:
- rigid plastic trays, made from such resins as polypropylene, polyethylene terephthalate (PET), and crystallized polyethylene terephthalate (CPET)
- trays produced via thermoforming plastic film
- trays made from paperboard or molded pulp (i.e., molded fiber)
- tubs, cups, and bowls:
- including round and square-round tubs, cups, and bowls for retail packaging as well as larger tubs, such as those used to package ice cream for foodservice establishments
- including lids that are sold with the unit, but excluding those sold separately
- vacuum skin packaging (VSP)
- wrap:
- including foil wrap, paper wrap and overwrap, as well as plastic film wrap and overwrap, including stretch and shrink film/wrap and thermoforming film
- excluding lidding films, chubs, brick packs, vacuum seal packaging (VSP), and vacuum sealed bags
- other packaging formats, including cans made of materials other than plastic, paper interleaving, corrugated circles for pizza and baked goods, and paperboard tubes for ice cream novelties
Corrugated boxes used as primary packaging are included; however, corrugated boxes for secondary packaging with case quantities are excluded, as are shipping containers and retail-ready packaging.
Also excluded are separately sold lids, caps, and closures.
Demand for frozen food packaging is forecast to increase 3.5% per year to $8.8 billion in 2024, driven by:
- strong consumer demand for convenience foods
- frozen food product innovations and a continuously expanding range of healthy and premium options, which often use different and higher value packaging
- a continued reliance on frozen foods in the foodservice industry due to their longer shelf life, lower cost, and ease of preparation
- the use of higher value packaging – including stand-up pouches, susceptor trays, and folding cartons with high-quality graphics – to help differentiate products
- expanded availability of products in portion-controlled sizes, with smaller servings resulting in higher packaging use per product
Frozen Specialty Foods & Frozen Meat to See Fastest Growth for Packaging
Frozen specialties (e.g., dinners, pizza, breakfast foods, and entrées) are expected to remain the largest market for frozen food packaging – and see the fastest annual growth – through 2024. Sales growth in this category will be driven by increased at-home meal preparation as well as by an expanded range of available specialty foods and packaging innovations, which improve the quality of the final product and increase the value of packaging demand.
Demand for packaging of frozen meat, poultry, and seafood is also expected to increase at a healthy pace, supported by rising production volumes, the popularity of new convenience products, and the favorable price and quality of frozen meats. In addition, gains will result from high volume requirements in the foodservice sector as restaurants recover from closures and capacity restrictions during the COVID-19 pandemic.
COVID-19 Pandemic Boosts At-Home Cooking & Reliance on Convenience Foods
Increased work-at-home and remote learning activities during the COVID-19 pandemic led to a rapid expansion of at-home meal preparation, which, in turn, prompted consumers to stock up on convenient, long-lasting frozen foods. In addition, panic buying and supply chain issues for fresh and shelf-stable foods encouraged increased purchases from the freezer aisle. Heightened sales of frozen foods are expected to carry forward – supporting related packaging demand – as consumers become increasingly accustomed to the convenience of frozen foods and as they become more familiar with the quality and variety of frozen dinners, entrées, and other available items.
Frozen Food Packaging Suppliers Invest in More Sustainable Alternatives to Plastic
Negative perceptions about the sustainability of plastic have increased interest in alternative packaging materials with environmental profiles that are perceived to be more environmentally friendly, including paper, molded pulp, and bioplastics. In addition, many companies have pledged to meet specific sustainability goals through the increased use of recycled post-consumer content in their packaging products.
- Executive Summary
- Figure 1-1 | US Frozen Food Packaging Market Outlook
- Overview
- Study Scope
- Historical Trends
- Table | Frozen Food Packaging Market, 2009 – 2019
- Figure 2-1 | Frozen Food Packaging Demand, 2009 – 2019
- Impact of COVID-19 Pandemic
- Table | Annual Frozen Food Packaging Demand by Product, 2019 – 2021
- Table | Annual Frozen Food Packaging Demand by Application, 2019 – 2021
- Figure 2-2 | Frozen Food Packaging Value Demand, 2018 – 2024
- Demand by Application
- Table | Frozen Food Packaging Demand by Application, 2009 – 2024
- Figure 2-3 | Frozen Food Packaging Demand by Application, 2009 – 2024
- Fastest Growing Frozen Food Packaging Applications
- Figure 2-4 | Fastest Growing Frozen Food Packaging Applications
- Demand by Format (Rigid vs. Flexible)
- Table | Frozen Food Packaging Demand by Format, 2009 – 2024
- Fastest Growing Frozen Food Packaging Products
- Figure 2-5 | Fastest Growing Frozen Food Packaging Products
- Pricing Trends
- Table | Selected Frozen Food Packaging Average Prices, 2009 – 2024
- Global Market Size & Trends
- Table | Global Frozen Food Packaging Demand, 2009 – 2024
- Factors Impacting Packaging Demand
- Frozen Food Industry Trends
- Figure 3-1 | Frozen Food Shipments by Market, 2009 – 2024
- Consumer Preferences
- Coronavirus Frozen Food Trends
- Table | "Because of the coronavirus, I am buying more frozen…" by Gender & Age Group, 2020
- Preferred Food Formats For Produce
- Table | Types of Produce Purchased by Format, 2020
- Table | Types of Frozen Produce Purchased by Gender & Age Group, 2020
- Supplemental/Free-Standing Freezer Ownership & Purchases
- Table | Supplemental or Free-Standing Home Freezer Ownership & Purchases by Gender & Age Group, 2020
- Packaging Insights
- Table | Packaging Consumer Insights by Gender & Age Group, 2020
- Coronavirus Frozen Food Trends
- Sustainability Initiatives
- Recycling & Recycled Content
- Source Reduction (Weight Reduction)
- Alternative Materials
- Frozen Food Industry Trends
- Flexible Packaging for Frozen Food
- Scope & Product Description
- Figure 4-1 | Flexible Packaging for Frozen Foods: Product Examples
- Demand by Product
- Table | Flexible Frozen Food Packaging Demand by Product, 2009 – 2024
- Figure 4-2 | Flexible Frozen Food Packaging Demand by Product, 2009 – 2024
- Bags
- Product Description
- Figure 4-3 | Bags for Frozen Food: Product Examples
- Demand by Application
- Table | Frozen Food Bag Demand by Application, 2009 – 2024
- Demand by Material
- Table | Frozen Food Bag Demand by Material, 2009 – 2024
- Suppliers
- Table | Selected Frozen Food Bag Suppliers
- Product Description
- Pouches (Flat & Stand-Up)
- Product Description
- Figure 4-4 | Pouches for Frozen Food: Product Examples
- Demand by Type & Application
- Table | Frozen Food Pouch Demand by Type & Application, 2009 – 2024
- Suppliers
- Table | Selected Frozen Food Pouch Suppliers
- Product Description
- Wrap
- Product Description
- Figure 4-5 | Wrap for Frozen Food: Product Examples
- Demand by Application
- Table | Frozen Food Wrap Demand by Application, 2009 – 2024
- Demand by Material
- Table | Frozen Food Wrap Demand by Material, 2009 – 2024
- Suppliers
- Table | Selected Frozen Food Wrap Suppliers
- Product Description
- Lidding
- Product Description
- Figure 4-6 | Lidding for Frozen Foods: Product Examples
- Demand by Application
- Table | Frozen Food Lidding Demand by Application, 2009 – 2024
- Demand by Material
- Table | Frozen Food Lidding Demand by Material, 2009 – 2024
- Suppliers
- Table | Selected Frozen Food Lidding Suppliers
- Product Description
- Other Flexible Packaging
- Demand by Product
- Table | Other Flexible Frozen Food Packaging Demand by Product & Application, 2009 – 2024
- Interleaving
- Figure 4-7 | Interleaving for Frozen Foods: Product Examples
- Chubs
- Figure 4-8 | Chub Packaging for Frozen Foods: Product Examples
- Vacuum Skin Packaging
- Figure 4-9 | Vacuum Skin Packaging for Frozen Foods: Product Examples
- Brick Packs
- Figure 4-10 | Brick Packs for Frozen Foods: Product Examples
- Demand by Product
- Flexible Packaging Market Share & Key Suppliers
- Figure 4-11 | Flexible Frozen Food Packaging Market Share, 2019
- Scope & Product Description
- Rigid Packaging for Frozen Food
- Scope & Product Description
- Figure 5-1 | Rigid Packaging for Frozen Food: Product Examples
- Demand by Product
- Table | Rigid Frozen Food Packaging Demand by Product, 2009 – 2024
- Figure 5-2 | Rigid Frozen Food Packaging Demand by Product, 2009 – 2024
- Boxes & Cartons
- Scope & Product Description
- Figure 5-3 | Boxes & Cartons for Frozen Food: Product Examples
- Demand by Application
- Table | Frozen Food Box & Carton Demand by Application, 2009 – 2024
- Demand by Box Type
- Table | Frozen Food Box & Carton Demand by Type, 2009 – 2024
- Folding Cartons
- Table | Frozen Food Folding Carton Demand by Application, 2009 – 2024
- Corrugated Boxes
- Table | Frozen Food Corrugated Box Demand by Application, 2009 – 2024
- Gable Top Cartons
- Table | Frozen Food Gable Top Carton Demand by Application, 2009 – 2024
- Box & Carton Suppliers
- Table | Selected Frozen Food Box & Carton Suppliers
- Scope & Product Description
- Trays
- Scope & Product Description
- Figure 5-4 | Trays for Frozen Food Products: Product Examples
- Demand by Application
- Table | Frozen Food Tray Demand by Application, 2009 – 2024
- Demand by Material
- Table | Frozen Food Tray Demand by Material, 2009 – 2024
- Suppliers
- Table | Selected Frozen Food Tray Suppliers
- Scope & Product Description
- Tubs, Cups, &Bowls
- Scope & Product Description
- Figure 5-5 | Tubs, Cups, &Bowls for Frozen Food: Product Examples
- Demand by Application
- Table | Frozen Food Tub, Cup, &Bowl Demand by Application, 2009 – 2024
- Demand by Material
- Table | Frozen Food Tub, Cup, &Bowl Demand by Material, 2009 – 2024
- Suppliers
- Table | Selected Frozen Food Cup, Tub, &Bowl Suppliers
- Scope & Product Description
- Plastic Containers
- Scope & Product Description
- Figure 5-6 | Plastic Containers for Frozen Food: Product Examples
- Demand by Type & Application
- Table | Frozen Food Plastic Container Demand by Product & Application, 2009 – 2024
- Suppliers
- Table | Selected Frozen Food Plastic Container Suppliers
- Scope & Product Description
- Paperboard Sleeves
- Scope & Product Description
- Figure 5-7 | Paperboard Sleeves for Frozen Food: Product Examples
- Demand by Application
- Table | Frozen Food Paperboard Sleeve Demand by Application, 2009 – 2024
- Suppliers
- Scope & Product Description
- Foil Packaging
- Scope & Product Description
- Figure 5-8 | Aluminum Foil Packaging for Frozen Food: Product Examples
- Demand by Application
- Table | Rigid Foil Frozen Food Packaging Demand by Application, 2009 – 2024
- Suppliers
- Table | Selected Frozen Food Foil Packaging Suppliers
- Scope & Product Description
- Other Rigid Packaging
- Scope & Product Description
- Figure 5-9 | Other Rigid Packaging for Frozen Food: Product Examples
- Demand by Application
- Table | Other Rigid Frozen Food Packaging Demand by Application, 2009 – 2024
- Scope & Product Description
- Rigid Packaging Market Share & Key Suppliers
- Figure 5-10 | Rigid Frozen Food Packaging Market Share, 2019
- Scope & Product Description
- Packaging Materials
- Demand by Material
- Table | Frozen Food Packaging Demand by Material, 2009 – 2024
- Figure 6-1 | Outlook for Packaging Materials by Type & Frozen Food Application, 2019 – 2024
- Plastic
- Demand by Product
- Table | Plastic Frozen Food Packaging Demand by Product, 2009 – 2024
- Figure 6-2 | Plastic Frozen Food Packaging Demand by Product, 2009 – 2024
- Flexible Plastic
- Table | Flexible Plastic Frozen Food Packaging Demand by Product, 2009 – 2024
- Rigid Plastic
- Table | Rigid Plastic Frozen Food Packaging Demand by Product, 2009 – 2024
- Demand by Product
- Paper & Paperboard
- Table | Paper & Paperboard Frozen Food Packaging Demand by Product, 2009 – 2024
- Figure 6-3 | Paper & Paperboard Frozen Food Packaging Demand by Product, 2009 – 2024
- Aluminum Foil
- Table | Aluminum Frozen Food Packaging Demand by Product, 2009 – 2024
- Figure 6-4 | Aluminum Foil Frozen Food Packaging Demand by Product, 2009 – 2024
- Molded Pulp & Other Materials
- Table | Molded Pulp & Other Frozen Food Packaging Demand by Material & Product, 2009 – 2024
- Demand by Material
- Frozen Specialty Food Packaging
- Application Scope & Description
- Figure 7-1 | Frozen Specialty Foods: Product Examples
- Demand by Product
- Table | Frozen Specialty Food Packaging Demand by Product, 2009 – 2024
- Demand by Material
- Table | Frozen Specialty Food Packaging Demand by Material, 2009 – 2024
- Figure 7-2 | Frozen Specialty Food Packaging Demand by Material, 2009 – 2024
- Demand by Application
- Table | Frozen Specialty Food Packaging Demand by Application, 2009 – 2024
- Frozen Dinners
- Table | Frozen Dinner Packaging Demand by Product, 2009 – 2024
- Frozen Pizza
- Table | Frozen Pizza Packaging Demand by Product, 2009 – 2024
- Frozen Breakfast Foods
- Table | Frozen Breakfast Food Packaging Demand by Product, 2009 – 2024
- Frozen Entrées & Side Dishes
- Table | Frozen Entrée & Side Dish Packaging Demand by Product, 2009 – 2024
- Other Frozen Specialty Foods
- Table | Other Frozen Specialty Food Packaging Demand by Product, 2009 – 2024
- Application Scope & Description
- Frozen Meat, Poultry, &Seafood Packaging
- Application Scope & Description
- Figure 8-1 | Frozen Meat, Poultry, &Seafood: Product Examples
- Demand by Product
- Table | Frozen Meat, Poultry, &Seafood Packaging Demand by Product, 2009 – 2024
- Demand by Material
- Table | Frozen Meat, Poultry, &Seafood Packaging Demand by Material, 2009 – 2024
- Demand by Application
- Table | Frozen Meat, Poultry, &Seafood Packaging Demand by Application, 2009 – 2024
- Frozen Poultry
- Table | Frozen Poultry Packaging Demand by Product, 2009 – 2024
- Frozen Meat
- Table | Frozen Meat Packaging Demand by Product, 2009 – 2024
- Frozen Seafood
- Table | Frozen Seafood Packaging Demand by Product, 2009 – 2024
- Application Scope & Description
- Frozen Baked Goods Packaging
- Application Scope & Description
- Figure 9-1 | Frozen Baked Goods: Product Examples
- Demand by Product
- Table | Frozen Baked Good Packaging Demand by Product, 2009 – 2024
- Demand by Material
- Table | Frozen Baked Goods Packaging Demand by Material, 2009 – 2024
- Demand by Application
- Table | Frozen Baked Goods Packaging Demand by Application, 2009 – 2024
- Frozen Baked Desserts (Pies, Cakes, &Pastries)
- Table | Frozen Baked Dessert Packaging Demand by Product, 2009 – 2024
- Breads, Rolls, &Bagels
- Table | Frozen Bread, Roll, &Bagel Packaging Demand by Product, 2009 – 2024
- Application Scope & Description
- Frozen Fruit, Vegetable, &Juice Packaging
- Application Scope & Description
- Figure 10-1 | Frozen Fruit, Vegetables, &Juice: Product Examples
- Demand by Product
- Table | Frozen Fruit, Vegetable, &Juice Packaging Demand by Product, 2009 – 2024
- Demand by Material
- Table | Frozen Fruit, Vegetable, &Juice Packaging Demand by Material, 2009 – 2024
- Demand by Application
- Table | Frozen Fruit, Vegetable, &Juice Packaging Demand by Application, 2009 – 2024
- Frozen Vegetables
- Table | Frozen Vegetable Packaging Demand by Application & Product, 2009 – 2024
- Frozen Fruit
- Table | Frozen Fruit Packaging Demand by Product, 2009 – 2024
- Frozen Juice
- Table | Frozen Juice Packaging Demand by Product, 2009 – 2024
- Application Scope & Description
- Ice Cream & Frozen Dessert Packaging
- Application Scope & Description
- Figure 11-1 | Ice Cream & Frozen Desserts: Product Examples
- Demand by Product
- Table | Ice Cream & Frozen Dessert Packaging Demand by Product, 2009 – 2024
- Demand by Material
- Table | Ice Cream & Frozen Dessert Packaging Demand by Material, 2009 – 2024
- Figure 11-2 | Ice Cream & Frozen Dessert Packaging Demand by Material, 2009 – 2024
- Demand by Application
- Table | Ice Cream & Frozen Dessert Packaging Demand by Application, 2009 – 2024
- Ice Cream & Frozen Yogurt
- Table | Ice Cream & Frozen Yogurt Packaging Demand by Application & Product, 2009 – 2024
- Frozen Novelties
- Table | Frozen Novelties Packaging Demand by Product, 2009 – 2024
- Sherbet, Sorbet, &Other Frozen Desserts
- Table | Sherbet, Sorbet, &Other Frozen Dessert Packaging Demand by Product, 2009 – 2024
- Application Scope & Description
- Suppliers & Market Share
- Key Findings & Industry Composition
- Table | US Frozen Food Packaging Sales by Company, 2019
- Market Share
- Figure 12-1 | US Frozen Food Packaging Market Share, 2019
- Figure 12-2 | US Frozen Food Packaging Market, 2019: Leading Supplier
- Figure 12-3 | US Frozen Food Packaging Market, 2019: Second Leading Supplier
- Figure 12-4 | US Frozen Food Packaging Market, 2019: Third Leading Supplier
- Figure 12-5 | US Frozen Food Packaging Market, 2019: Fourth Leading Supplier
- Figure 12-6 | US Frozen Food Packaging Market, 2019: Fifth Leading Supplier
- Figure 12-7 | US Frozen Food Packaging Market, 2019: Sixth Leading Supplier
- Figure 12-8 | US Frozen Food Packaging Market, 2019: Seventh Leading Supplier
- Figure 12-9 | US Frozen Food Packaging Market, 2019: Eighth Leading Supplier
- Mergers & Acquisitions
- Table | Selected Mergers & Acquisitions
- List of Industry Participants
- Table | Selected Industry Participants
- Key Findings & Industry Composition
- Appendix
- Scope
- Table | Industry Codes Related to Frozen Food Packaging
- Table | Relevant HS Codes
- Definitions
- Abbreviations
- Table | Abbreviations & Acronyms Used in the Study
- Freedonia Methodology
- Study-Specific Methodology
- Sources
- Associations & Agencies
- Related Studies & Reports
- Macroeconomic Assumptions
- Economic Environment
- Table | Macroeconomic Indicators, 2009 – 2024
- Figure 13-1 | Annual Growth in Real GDP, 2000 – 2019, Compared to 1980 – 2005 Average
- Demographics
- Table | Population & Households, 2009 – 2024
- Figure 13-2 | Annual Population Growth, 2004 – 2019
- Consumer Spending
- Table | Personal Consumption Expenditures, 2009 – 2024
- Economic Environment
- Scope
Demand for frozen food packaging is forecast to increase 3.5% per year to $8.8 billion in 2024.
Frozen specialties (e.g., dinners, pizza, breakfast foods, and entre es) are expected to remain the largest market for frozen food packaging – and see the fastest annual growth – through 2024.
Paper frozen food packaging will be increasingly competitive with plastic due to its sustainable image.