Frozen Meat, Poultry & Seafood Packaging
Free Sample Report
Request a free sample of this report and our team will email it to you.
Report Overview
Featuring 37 tables and 20 figures – now available in Excel and Powerpoint! Learn More
This study analyzes the US market for frozen food packaging. Historical (2009, 2014 and 2019) data and forecasts to 2024 are presented in current dollars
Applications covered include:
- meat, poultry, and seafood, including fresh, unprepared items as well as further processed types, such as breaded poultry and seafood:
- meat (including beef and veal, pork, and lamb) as well as meat products marketed as breakfast meats
- poultry (chicken, turkey, and other products such as goose and duck)
- seafood (all fish and shellfish)
Excluded from the scope of this study are:
- frozen carryout
- meal delivery program foods
- shelf-stable products that are frozen after purchase
Packaging product segments covered include:
- flexible packaging
- bags
- wrap:
- including foil wrap, paper wrap and overwrap, as well as plastic film wrap and overwrap, including stretch and shrink film/wrap and thermoforming film
- excluding lidding films, chubs, brick packs, vacuum seal packaging (VSP), and vacuum sealed bags
- pouches, including:
- flat (e.g., pillow, four-side seal, and three-side seal)
- stand-up, including round-bottom/Doyen, K-seal, corner-bottom, flat-bottom
- lidding and other plastic film:
- including plastic film lidding (typically made from one or more layers of plastics such as PET or PP), paper lidding, and aluminum foil lidding
- excluding paper and plastic lids sold together with accompanying paper or plastic containers as well as plastic overwrap and shrink wrap
- other flexible packaging (e.g., chubs, vacuum skin packaging, paper interleaving)
- rigid packaging
- boxes (e.g., folding cartons – also known as folding paperboard boxes – corrugated boxes, gable top cartons)
- trays:
- rigid plastic trays, made from such resins as polypropylene, polyethylene terephthalate (PET), and crystallized polyethylene terephthalate (CPET)
- trays produced via thermoforming plastic film
- trays made from paperboard or molded pulp (i.e., molded fiber)
- paperboard sleeves, including paperboard sleeves used as outer packaging and paperboard susceptor sleeves
- other rigid packaging
Corrugated boxes used as primary packaging are included; however, corrugated boxes for secondary packaging with case quantities are excluded, as are shipping containers and retail-ready packaging.
Demand is also segmented by material:
- plastic
- paper and paperboard
- foil and other materials (e.g., molded pulp)
Also excluded are separately sold lids, caps, and closures.
Demand by Packaging Type
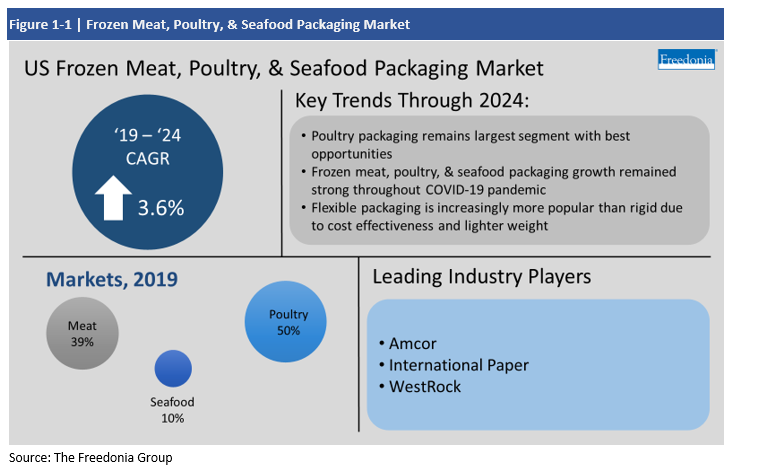
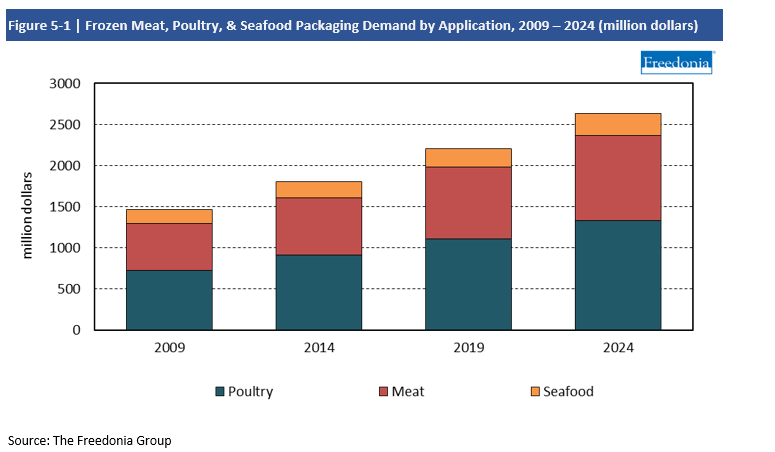
Demand for frozen meat, poultry and seafood packaging is projected to climb 3.6% per year to $2.6 billion in 2024, supported by:
- expanded production of meat, poultry, and seafood products
- the rising popularity of convenience-type items and the promotion of frozen meat, poultry, and seafood as economical protein options
- improving quality of frozen items and a wider range of frozen products available
- increased demand for individually portioned offerings – due to their convenience, smaller household sizes, and efforts to reduce food waste – which typically use more packaging per volume than larger sizes
In addition, gains will be aided by favorable prospects for limited-service restaurants, since these establishments rely heavily on frozen meat, poultry, and seafood products.
Flexible packaging is both larger and faster growing than rigid packaging. This is primarily due to the continued popularity of bags, wraps, and pouches in the frozen meat, poultry, and seafood market segment, due to their light weight and cost effectiveness.
Corrugated boxes, bags, wrap, and pouches are the leading packaging products for frozen meat, poultry, and seafood, accounting for a combined 77% of demand in 2019, with corrugated boxes alone accounting for 36%. The remainder of demand is generated by trays, lidding and plastic film, and other products such as paper interleaving, plastic containers, and paperboard sleeves.
Demand by Application
Poultry, which accounted for 50% of frozen meat, poultry, and seafood packaging demand in 2019, will remain the leading application based on:
- favorable production and consumption trends, including health trends supporting consumption of poultry over red meats
- the relatively large volume of poultry items shipped in frozen form to both consumer and foodservice outlets
Frozen seafood comprises a relatively small share of packaging sales, as most seafood consumed in the US is packaged overseas and imported (such packaging demand is excluded from the data in this report).
In all applications, packaging demand will be supported by the introduction of new frozen meat, poultry, and seafood products (e.g., with new flavors and marinades) that require packaging and by a continued focus on convenience (e.g., single-serve portions and resealable pouches). However, demand will be limited in each segment by strong competition from fresh and ready-to-eat items due to consumer preference for convenient prepared foods (e.g., rotisserie chicken).
Demand by Material
Frozen meat, poultry, and seafood packaging is composed primarily of paperboard and plastic products, although foil and molded pulp are also used to some extent.
Growth of plastic packaging for frozen meat, poultry, and seafood will be supported by:
- the increased popularity of pouches – particularly stand-up types
- the continued use of bags and wraps due to their cost effectiveness
- increased demand for individually portioned servings, which are often packaged in plastic
Despite the lackluster performance of folding cartons in the frozen meat, poultry, and seafood packaging market, growth for paperboard packaging will be supported primarily by the continued use of corrugated boxes in warehouse clubs and restaurants.
Other materials – such as aluminum foil – comprise a small proportion of overall frozen meat, poultry, and seafood packaging.
- Executive Summary
- Table | Frozen Meat, Poultry, &Seafood Packaging Market
- About This Report
- Report Details
- Application Scope & Product Description
- Table | Frozen Meat, Poultry, &Seafood: Product Examples
- Impact of the COVID-19 Pandemic
- Table | Annual Frozen Meat, Poultry, &Seafood Packaging Demand by Application, 2019 - 2021
- Table | Annual Frozen Meat, Poultry, &Seafood Packaging Demand, 2018 - 2022
- Overview
- Historical Market Trends
- Table | Frozen Meat, Poultry & Seafood Packaging Demand, 2009 - 2019
- Table | Frozen Meat, Poultry, &Seafood Packaging Demand, 2000 - 2020
- Packaging Types
- Demand by Type
- Table | Frozen Meat, Poultry, &Seafood Packaging Demand by Packaging Type, 2009 - 2024
- Flexible Packaging
- Table | Frozen Meat, Poultry, &Seafood Flexible Packaging Demand by Type, 2009 - 2024
- Rigid Packaging
- Table | Frozen Meat, Poultry, &Seafood Rigid Packaging Demand by Type, 2009 - 2024
- Demand by Type
- Pricing Trends
- Table | Frozen Meat, Poultry, &Seafood Packaging Pricing by Product, 2009 - 2024
- Historical Market Trends
- Factors Impacting Packaging Demand
- Frozen Food Industry Trends
- Table | Frozen Food Share of Food Manufacturing, 2009 - 2024
- Meat, Poultry, &Seafood Industry Trends
- Table | Meat, Poultry, &Seafood Consumption by Application, 2009 - 2024
- Table | Meat, Poultry, &Seafood Consumption by Application, 2009 - 2024
- Consumer Preferences
- Supplemental/Freestanding Freezer Ownership & Purchases
- Table | Supplemental or Freestanding Home Freezer Ownership & Purchases by Gender & Age Group, 2020
- Packaging Insights
- Table | Packaging Consumer Insights by Gender & Age Group, 2020
- Priorities for Packaging Features
- Table | Consumer Insights: Opinions on Meat & Poultry Packaging Features, 2019
- Safety & Handling Concerns
- Table | Consumer Insights: Opinions on Food Product Safety, 2019
- Recycling & the Environment
- Table | Consumer Insights: Opinions on Recycling Meat & Poultry Packaging, 2019
- Meat Buying Habits
- Table | Consumer Insights: Adherence to Different Eating Practices, 2020
- Supplemental/Freestanding Freezer Ownership & Purchases
- Sustainability Initiatives
- Frozen Food Industry Trends
- Applications
- Demand by Application
- Table | Frozen Meat, Poultry, &Seafood Packaging Demand by Application, 2009 - 2024
- Table | Frozen Meat, Poultry, &Seafood Packaging Demand by Application, 2009 - 2024
- Frozen Poultry
- Demand Forecast
- Table | Frozen Poultry Packaging Demand by Product Type, 2009 - 2024
- Flexible Packaging
- Table | Frozen Poultry Flexible Packaging Demand by Product, 2009 - 2024
- Rigid Packaging
- Table | Frozen Poultry Rigid Packaging Demand by Product, 2009 - 2024
- Demand by Material
- Table | Frozen Poultry Packaging Demand by Material, 2009 - 2024
- Table | Frozen Poultry Packaging Demand by Material, 2009 - 2024
- Demand Forecast
- Frozen Meat
- Demand Forecast
- Table | Frozen Meat Packaging Demand by Product, 2009 - 2024
- Table | Frozen Meat Packaging Demand by Product, 2009 - 2024
- Flexible Packaging
- Table | Frozen Meat Flexible Packaging Demand by Product, 2009 - 2024
- Rigid Packaging
- Table | Frozen Meat Rigid Packaging Demand by Product, 2009 - 2024
- Demand by Material
- Table | Frozen Meat Packaging Demand by Material, 2009 - 2024
- Table | Frozen Meat Packaging Demand by Material, 2009 - 2024
- Demand Forecast
- Frozen Seafood
- Demand Forecast
- Table | Frozen Seafood Packaging Demand by Product Type, 2009 - 2024
- Table | Frozen Seafood Packaging Demand by Product, 2009 - 2024
- Flexible Packaging
- Table | Frozen Seafood Flexible Packaging Demand by Product, 2009 - 2024
- Rigid Packaging
- Table | Frozen Seafood Rigid Packaging Demand by Product, 2009 - 2024
- Demand by Material
- Table | Frozen Seafood Packaging Demand by Material, 2009 - 2024
- Table | Frozen Seafood Packaging Demand by Material, 2009 - 2024
- Demand Forecast
- Demand by Application
- Materials
- Demand by Material
- Table | Frozen Meat, Poultry, &Seafood Packaging Demand by Material, 2009 - 2024
- Table | Frozen Meat, Poultry, &Seafood Packaging Demand by Material, 2009 - 2024
- Plastic
- Table | Frozen Meat, Poultry, &Seafood Plastic Packaging Demand by Application, 2009 - 2024
- Flexible Plastic
- Table | Flexible Plastic Packaging Demand by Application, 2009 - 2024
- Rigid Plastic
- Table | Rigid Plastic Packaging Demand by Application, 2009 - 2024
- Paper & Paperboard
- Table | Paper & Paperboard Packaging Demand by Application, 2009 - 2024
- Foil & Other Materials
- Table | Foil & Other Packaging Demand by Application, 2009 - 2024
- Demand by Material
- Key Suppliers & Industry Structure
- Industry Composition
- Market Share
- Table | Frozen Meat, Poultry, &Seafood Packaging Market Share by Company, 2019
- Table | US Frozen Meat, Poultry, &Seafood Packaging Market, 2019: Leading Supplier
- Table | US Frozen Meat, Poultry, &Seafood Packaging Market, 2019: Second Leading Supplier
- Table | US Frozen Meat, Poultry, &Seafood Packaging Market, 2019: Third Leading Supplier
- Mergers & Acquisitions
- Table | Selected Mergers & Acquisitions
- Appendix
- Scope
- Table | Relevant Industry Codes
- Table | Relevant HS Codes
- Definitions
- Freedonia Methodology
- Study-Specific Methodology
- Sources
- Associations & Agencies
- Related Studies & Reports
- Macroeconomic Assumptions
- Economic Environment
- Table | Macroeconomic Indicators, 2009 - 2024
- Table | Annual Growth in Real GDP, 2000 - 2019, Compared to 1980 - 2005
- Demographics
- Table | Population & Households, 2009 - 2024
- Table | Annual Population Growth, 2004 - 2019
- Consumer Spending
- Table | Personal Consumption Expenditures, 2009 - 2024
- Economic Environment
- Scope