Global Beverage Caps & Closures
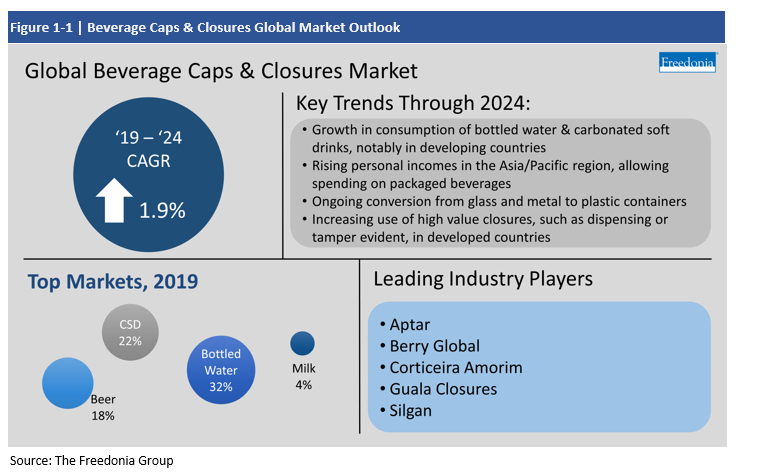
Global demand for caps and closures used in the beverage market is expected to grow 1.9% per year through 2024 to nearly 1.6 trillion units.
Free Sample Report
Request a free sample of this report and our team will email it to you.
Report Overview
Featuring 89 tables and 70 figures – now available in Excel and Powerpoint! Learn More
 This study analyzes the global market for beverage caps and closures. The closures included herein are those used on containers intended for disposal after use. A significant degree of overlap exists among product categories. For purposes of this report, a closure is categorized by the primary function of the closure
Demand by Region
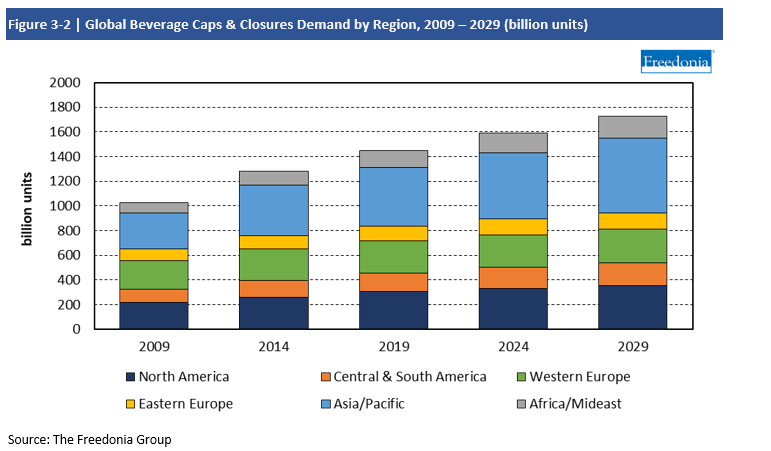
Global demand for caps and closures in beverage applications is projected to increase 1.9% annually to 1.6 trillion units in 2024. Growing demand for beverages that are convenient and healthy will support increases globally:
- The Asia/Pacific region will remain the most important regional market for caps and closures in beverage applications, accounting for 34% of global demand in 2024. Demand gains will be driven by China, which will account for nearly half of regional absolute gains.
- The fastest gains will be seen in the Africa/Mideast region, boosted by rising spending on beverages, although it will remain the second smallest regional market, accounting for less than 10% of global demand.
- Demand in Western Europe will stagnate through 2024, although opportunities will exist for bottled water closures and wine.
Demand by Material
Global demand for caps and closures in beverage applications is projected to increase 1.9% annually to 1.6 trillion units in 2024.
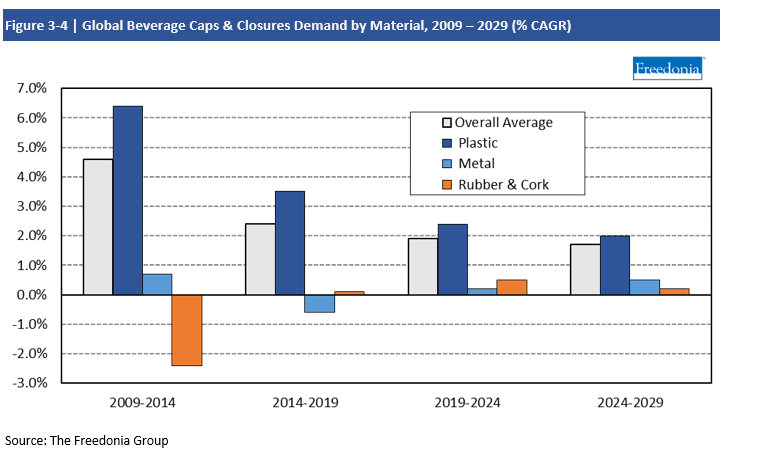
Plastic closures will experience gains, reflecting the continued penetration of PET bottles – which mainly utilize plastic closures – in many beverage applications, particularly the sizable bottled water and CSD segments. However, plastic bottles are expected to face competition from aluminum cans, which do not use closures.
Demand for metal caps and closures will be limited by slow growth in beer consumption and the increasing packaging of beer in aluminum cans.
Overall, product manufacturers will continue to seek packaging that adds value to their offerings. As a result, caps and closures in some markets have trended toward the adoption of more expensive, functional closure devices, such as tamper-evident and dispensing types. However, in higher volume beverage applications such as beer and bottled water, simple commodity closures have maintained a dominant market position.
Recycling & Recycled Content
Packaging is responsible for a large amount of plastic waste and is the leading industry for plastic waste generation in the US and the EU. Over 750 billion bottles of water and CSD were sold in 2019, a significant percentage of which were plastic. The majority of these bottles were either burned, disposed of in a landfill, or ended up in the environment. Growing concerns about the impact of plastic on the environment and on human health has spurred many manufacturers to investigate ways to reduce the amount of plastic waste generated by beverage packaging.
In addition to lightweighting and waste reduction initiatives, many manufacturers are looking to increase the amount of recycled content in their plastic packaging. PepsiCo has announced plans to use 25% recycled content in its plastic packaging by 2025, while Coca Cola is aiming for 50% recycled content by 2030. In addition, manufacturers are exploring ways to make plastic packaging more recyclable. In the US, 100% of the bottled water sold is recyclable, including the cap.
Demand by Application
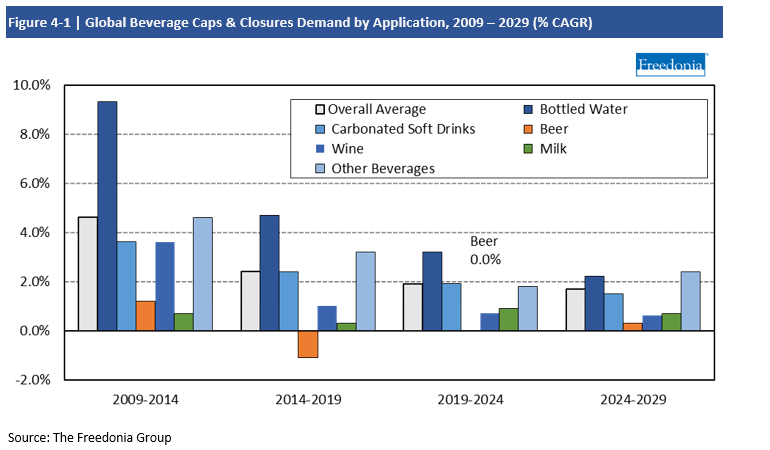
Global demand for caps and closures in the beverage market is projected to increase 1.9% annually to 1.6 trillion units in 2024. Among the most significant factors affecting the beverage industry overall is the shift in consumer preferences toward beverages that are low in sugar and that have additional health benefits, with bottled water the primary beneficiary in volume terms. In addition, premium beverages are seeing outsized gains in developed markets. Growth is expected in:
- the bottled water market, which will register the strongest gains among major beverage types especially in developing areas such as India and Indonesia, but also in the US and other developed markets
- the carbonated soft drink (CSD) market, boosted by growing demand in developing areas, with stronger gains limited by weakness in North America and Western Europe
- sports and energy drinks, ready-to-drink (RTD) coffee and tea, and other niche beverages, which are expected to register fast production gains worldwide and have a greater tendency to use premium or unique packaging as a marketing tool
Products covered include:
- plastic closures
- threaded closures, including standard threaded (screw caps), pressurized, and vacuum
- unthreaded closures (e.g., lids, overcaps, synthetic cork)
- other closures, such as dispensing closures (e.g., push-pull caps, twist-open closures, spigot closures)
- metal closures
- screw and lug (vacuum and nonvacuum)
- crowns
- roll-on pilfer proof (ROPP)
- other metal closures, such as aluminum vial seals, caps for composite cans, decorative metal container lids, aluminum seals, and shake and spout dispensers
- rubber
- cork
Excluded from the scope of this study are:
- caps and closures that are an integral part of the container (e.g., metal and composite can tops, peel-up aluminum lids)
- home canning and bottling closures
- glass and paperboard closures
- closures for industrial bulk containers
- flexible closures such as twist ties or foil lidding
- caps and closures used in nonbeverage nonpackaging applications (e.g., liquor decanter closures)
Beverage markets for these products include:
- bottled water (still and sparkling)
- carbonated soft drinks
- beer
- milk (dairy milk)
- wine
- other beverages (such as fruit drinks, ready-to-drink coffee and tea, and sports drinks, liquor and spirits, alternative milk products)
Historical data (2009, 2014, and 2019) and forecasts for 2024 and 2029 are presented for beverage caps and closures demand in units and current US dollars (including inflation) by product and market on a country-by-country and region-by-region basis. The terms “shipments”, “production”, and “output” are used interchangeably in the study, as are the terms “demand”, “sales”, and “market”, which are defined as domestic shipments, plus imports, minus exports.
Global demand for caps and closures used in the beverage market is expected to grow 1.9% per year through 2024 to nearly 1.6 trillion units. Gains will be driven by rising global demand for packaged beverage products:
- The Asia/Pacific region will see the greatest absolute gains, boosted by rising personal incomes and increasing consumption of bottled water and carbonated soft drinks (CSD).
- Demand for plastic closures will see the fastest gains globally, driven by the growing use of plastic beverage containers, while demand for metal closures will stagnate, restrained by declining numbers of glass bottles used for beer and CSD.
- Bottled water will remain the largest application for beverage caps and closures and will continue to take market share from CSD and beer.
Unlike many other industries, the global beverage caps and closures market was not negatively impacted by the COVID-19 pandemic in 2020, as beverages remain an essential product for consumers and are therefore less susceptible to events that can destabilize the global economy.
Bottled Water Will See the Fastest Growth in Most Global Markets
Bottled water will remain the largest market for beverage caps and closures, accounting for about a third of demand in 2024:
- Growth in developed regions will be supported by consumer demand for convenience and beverages that are perceived as being healthy.
- In developing regions, the lack of safe and accessible water sources, as well as growing consumer spending power, will support gains.
Alternative forms of packaging for water, such as aluminum cans and paperboard cartons, have been introduced in part due to sustainability campaigns, which seek to reduce plastic waste and preserve water sources. However, plastic bottled water will remain relatively resistant to sustainability efforts, causing these other types of containers to remain niche.
Plastic Will Continue to Gain Market Share; Metal Will Maintain Use in Some Applications
Demand for plastic caps and closures in the beverage market will be supported by the ongoing shift from glass to plastic containers due plastic’s advantages, including its light weight and ability to reduce product loss by preventing breakage. However, metal closures will continue to dominant the beer market, as they remain the preferred closure for beer bottles. Metal roll-on screw caps will gain share in the wine market as single-serve wine bottles increase in popularity.
Asia/Pacific Region to Offer the Best Opportunities
Over 40% of the global demand increases for beverage caps and closures will be in the Asia/Pacific region, already the largest regional market due to the presence of China, which will be responsible for 22% of all demand increases. Advances in the region will be fueled by healthy growth in beverage production and increasing personal spending. Caps and closures for bottled water will see the fastest gains, while demand in the beer market will decline, limited by decreasing beer production in China and Japan.
- Executive Summary
- About This Report
- Report Details
- Study Scope & Product Description
- Impact of COVID-19 Pandemic
- Overview
- Historical Market Trends
- Demand by Region
- Leading Country Markets
- Demand by Material
- Plastic
- Metal
- Cork & Rubber
- Sustainability Initiatives
- Source Reduction
- Recycling & Recycled Content
- Leading Producers
- Beverage Markets
- Demand by Application
- Bottled Water
- Bottled Water Consumption & Packaging Trends
- Demand by Region
- Demand by Material
- Carbonated Soft Drinks
- Carbonated Soft Drink Consumption & Packaging Trends
- Demand by Region
- Demand by Material
- Beer
- Beer Consumption & Packaging Trends
- Demand by Region
- Demand by Material
- Milk
- Milk Consumption & Packaging Trends
- Demand by Region
- Demand by Material
- Wine
- Wine Consumption & Packaging Trends
- Demand by Region
- Demand by Material
- Other Beverages
- Other Beverages Scope, Consumption, & Packaging Trends
- Demand by Region
- Demand by Material
- North America
- North America: Beverage Caps & Closures Market Size
- North America: Demand by Country
- North America: Demand by Material & Closure Type
- North America: Demand by Application
- United States
- United States: Beverage Caps & Closures Market Size
- United States: Demand by Material & Closure Type
- United States: Demand by Application
- Mexico
- Mexico: Beverage Caps & Closures Market Size
- Mexico Demand by Material & Closure Type
- Mexico: Demand by Application
- Canada
- Canada: Beverage Caps & Closures Market Size
- Canada: Demand by Material & Closure Type
- Canada: Demand by Application
- Central & South America
- Central & South America: Beverage Caps & Closures Market Size
- Central & South America: Demand by Country
- Central & South America: Demand by Material & Closure Type
- Central & South America: Demand by Application
- Brazil
- Brazil: Beverage Caps & Closures Market Size
- Brazil: Demand by Material & Closure Type
- Brazil: Demand by Application
- Other Central & South America
- Other Central & South America: Beverage Caps & Closures Market Size
- Other Central & South America: Demand by Material & Closure Type
- Other Central & South America: Demand by Application
- Western Europe
- Western Europe: Beverage Caps & Closures Market Size
- Western Europe: Demand by Country
- Western Europe: Demand by Material & Closure Type
- Western Europe: Demand by Application
- Germany
- Germany: Beverage Caps & Closures Market Size
- Germany: Demand by Material & Closure Type
- Germany: Demand by Application
- Italy
- Italy: Beverage Caps & Closures Market Size
- Italy: Demand by Material & Closure Type
- Italy: Demand by Application
- France
- France: Beverage Caps & Closures Market Size
- France: Demand by Material & Closure Type
- France: Demand by Application
- Spain
- Spain: Beverage Caps & Closures Market Size
- Spain: Demand by Material & Closure Type
- Spain: Demand by Application
- United Kingdom
- United Kingdom: Beverage Caps & Closures Market Size
- United Kingdom: Demand by Material & Closure Type
- United Kingdom: Demand by Application
- Other Western Europe
- Other Western Europe: Beverage Caps & Closures Market Size
- Other Western Europe: Demand by Material & Closure Type
- Other Western Europe: Demand by Application
- Eastern Europe
- Eastern Europe: Beverage Caps & Closures Market Size
- Eastern Europe: Demand by Country
- Eastern Europe: Demand by Material & Closure Type
- Eastern Europe: Demand by Application
- Russia
- Russia: Beverage Caps & Closures Market Size
- Russia: Demand by Material & Closure Type
- Russia: Demand by Application
- Other Eastern Europe
- Other Eastern Europe: Beverage Caps & Closures Market Size
- Other Eastern Europe: Demand by Material & Closure Type
- Other Eastern Europe: Demand by Application
- Asia/Pacific
- Asia/Pacific: Beverage Caps & Closures Market Size
- Asia/Pacific: Demand by Country
- Asia/Pacific: Demand by Material & Closure Type
- Asia/Pacific: Demand by Application
- China
- China: Beverage Caps & Closures Market Size
- China: Demand by Material & Closure Type
- China: Demand by Application
- India
- India: Beverage Caps & Closures Market Size
- India: Demand by Material & Closure Type
- India: Demand by Application
- Japan
- Japan: Beverage Caps & Closures Market Size
- Japan: Demand by Material & Closure Type
- Japan: Demand by Application
- Indonesia
- Indonesia: Beverage Caps & Closures Market Size
- Indonesia: Demand by Material & Closure Type
- Indonesia: Demand by Application
- Australia
- Australia: Beverage Caps & Closures Market Size
- Australia: Demand by Material & Closure Type
- Australia: Demand by Application
- South Korea
- South Korea: Beverage Caps & Closures Market Size
- South Korea: Demand by Material & Closure Type
- South Korea: Demand by Application
- Other Asia/Pacific
- Other Asia/Pacific: Beverage Caps & Closures Market Size
- Other Asia/Pacific: Demand by Material & Closure Type
- Other Asia/Pacific: Demand by Application
- Africa/Mideast
- Africa/Mideast: Beverage Caps & Closures Market Size
- Africa/Mideast: Demand by Material & Closure Type
- Africa/Mideast: Demand by Application
- Appendix
- Scope
- Definitions
- Freedonia Methodology
- Study-Specific Methodology
- Sources
- Associations & Agencies
- Related Studies & Reports
- Country Lists by Region
- Macroeconomic Assumptions
- Global Economic Outlook
- Global Population
- Global Personal Consumption Expenditures
Global demand for caps and closures used in the beverage market is expected to grow 1.9% per year through 2024 to nearly 1.6 trillion units.
Bottled water will remain the largest market for beverage caps and closures, accounting for about a third of demand in 2024.
The Asia/Pacific region will see the greatest absolute gains, boosted by rising personal incomes and increasing consumption of bottled water and carbonated soft drinks (CSD).