US Gutters & Downspouts
This Freedonia industry study analyzes the $8 billion US market for gutters and downspouts. It presents historical demand data (2012, 2017, and 2022) and forecasts (2027 and 2032) as well as annual data for years 2019-2026.
Free Sample Report
Request a free sample of this report and our team will email it to you.
Report Overview
-
Gutter guards will continue to grow in market share
-
Plastic gutter guards will continue to penetrate the market
This Freedonia industry study analyzes the $8 billion US market for gutters and downspouts. It presents historical demand data (2012, 2017, and 2022) and forecasts (2027 and 2032) as well as annual data for years 2019-2026. Unit demand and value demand data is shown for gutters and downspouts by material (steel, aluminum, plastic, copper), product type (gutters, downspouts, gutter guards, hardware & accessories) and market (new, improvement, and repair demand in both residential and commercial applications). The study also evaluates company market share and competitive analysis on industry competitors including Cornerstone, Leaf Home Solutions, OmniMax, Spectra Metals, and TopBuild.
Featuring 131 tables and 52 figures – available in Excel and Powerpoint! Learn about our Data Visualization Kit
Check out our recent discussion of Gutter Guards as well!
US demand for gutters and downspouts is forecast to rise less than 1.0% annually to 2.1 billion linear feet in 2027. While this rate of increase is not especially strong, it will represent a return to growth following the declines of the previous period, which were negatively impacted by a moderation in residential building construction in 2022. Rebounding commercial building construction will provide opportunities for gutter and downspout sales, as will an increase in single-family housing starts and improvement and repair activity in the latter part of the forecast period.
In value terms, demand is expected to grow 2.7% annually to $8.3 billion – a significant deceleration from the 2017-2022 period; market value in that span was boosted by price surges in 2021 and 2022, which resulted from a combination of supply chain issues and rising raw material costs.
Following Initial Weakness, Residential Market Will See Gains in Latter Part of Forecast Period
Following significantly elevated levels of gutter and downspout sales in 2020 and 2021, real demand in 2022 moderated as high interest rates and economic uncertainty began to weigh on the housing industry. Demand declined sharply in 2023 as housing starts fell and improvement and repair activity declined. However, these underlying indicators are expected to improve through the rest of the forecast period, with single-family housing starts returning to growth as interest rates ease and improvement and repair activity steadily rising, supporting the replacement of aging gutters and downspouts and the addition of gutter guards on existing homes.
Gutter Guards Will Grow in Popularity Among Homeowners
Demand for gutter guards – which are designed to keep leaves, pine needles, and other debris out of gutters – will rise as homeowners increasingly install these items to minimize the need to periodically clean gutters, a time-consuming and potentially dangerous task. Aluminum gutter guards will continue to account for the largest share of demand due to their light weight, which support their use among both professionals and DIYers. However, plastic gutter guards will continue to penetrate the market due to the wide variety of gutter guard options offered in plastic and the lower cost of these products compared to those made from aluminum and other metals.
Historical Market Trends
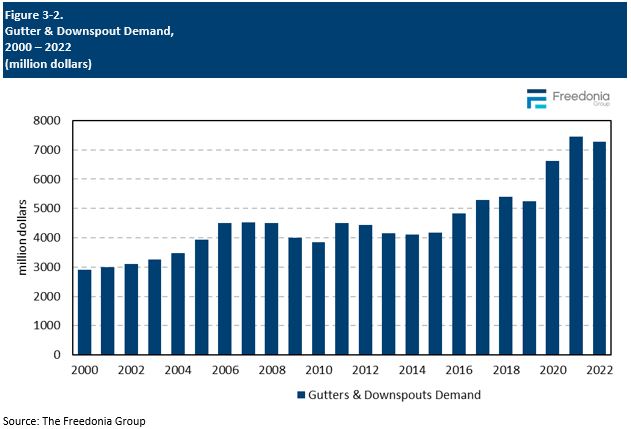
For the most part, sales of gutter and downspout products are dependent upon new building construction and a relatively predictable replacement cycle for existing buildings, with the residential aftermarket accounting for the vast majority of sales.
Demand tends to track changes in building construction activity although growth for gutters and downspouts is generally slower than that for overall construction, due primarily to the commodity nature of the products and the maturity of the market.
However, spending on gutter and downspout products can exceed growth in building construction during downturns due to:
-
the need to repair or replace gutters and downspouts in case of damage, which is not a discretionary expense for most homeowners
-
outbreaks of severe weather (such as hurricanes and tornadoes) that can cause damage to structures across a wide area, as demand for gutter systems may rise even if overall construction spending contracts
- the modest cost of gutter replacement compared to other home improvement projects can be attractive to homeowners who want to upgrade the appearance or function of their homes
Products Overview
Market Value
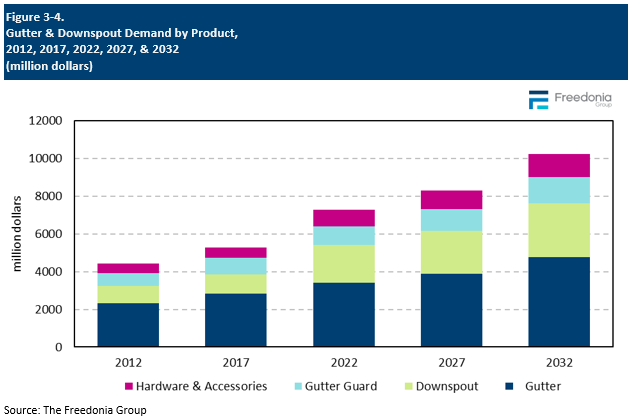
Market value for gutter system products – including gutters, downspouts, gutter guards, and related hardware and accessories – is projected to rise 2.7% per year to $8.3 billion in 2027. Advances will come from:
-
real growth in linear feet
-
increases in some raw material prices, notably aluminum and steel
Most rainware products are specified due to their durability and functionality, not for aesthetics; therefore, consumers generally choose gutters and downspouts based on price. This limits opportunities for value growth, as few consumers will opt for costly products like copper gutters and downspouts.
Demand for gutter guards does not necessarily track that of gutters. In fact, it is heavily dependent on residential applications because many homeowners add these products to existing gutters at a later date. This has fostered a secondary market; makers of gutter guard systems offer their products at premium prices, often having their own network of contractors who install their products to specification.. However, many gutter guards (especially those installed by DIY homeowners) are fairly inexpensive, which serves as a check on overall value demand advances.
Materials Overview
Gutter and downspout products are manufactured from a range of materials, including:
-
metals (aluminum, steel, copper, and zinc)
-
plastics (primarily polyvinyl chloride)
-
wood (mostly cedar and redwood)
-
fiberglass
-
concrete
Gutter and downspout materials must be rigid, corrosion, and impact resistant, and able to tolerate extremes of heat or cold.
Cost is among the most important factors that affects choice of rainware material. Materials are sold at a wide range of price points:
-
Plastics are the least expensive per foot.
-
Metals like aluminum and steel are mid-priced, though the cost of the latter has risen faster than the former over the last decade; that trend is currently intensified by higher tariffs on steel.
-
Copper, zinc, and wood are the most expensive (and least used) materials.
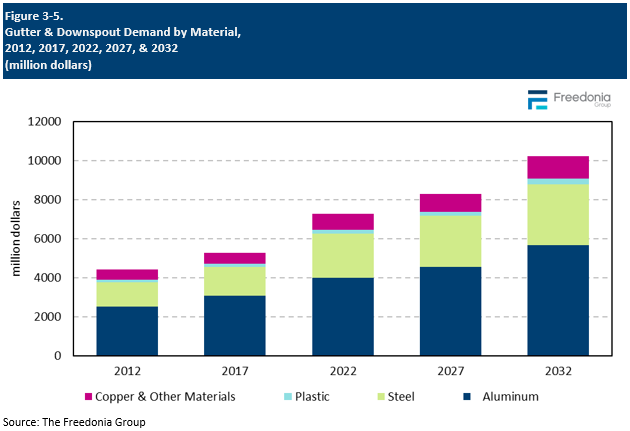
Aluminum will continue to be the most widely used gutter and downspout material. Steel products account for a smaller portion of demand, reflecting their low-volume use in the large residential market.
Use of plastic is limited by its low durability compared to metal, but cost-competitive vinyl rainware products are specified by some homeowners. Demand growth for plastic gutter and downspout products will come from the rising market penetration of gutter guards, a broad range of which – from the lowest priced types to costly proprietary systems – use plastic for its versatility and compatibility with all gutter types.
Gutter and downspout products made from copper and other materials account for a larger share of market value than volume because they are costly. Products made from these materials only account for a small share of total demand volume (and will continue to do so) due to both that expense and the fact that aluminum and steel can often provide the necessary performance.
Building Construction Outlook
For the most part, sales of gutter and downspout products are dependent upon new building construction and a relatively predictable replacement cycle for existing buildings. With the residential aftermarket accounting for the vast majority of sales.
Demand tends to track changes in building construction activity, although growth for gutters and downspouts is generally slower than overall construction. This is largely attributable to the commodity nature of the products and the maturity of the market.
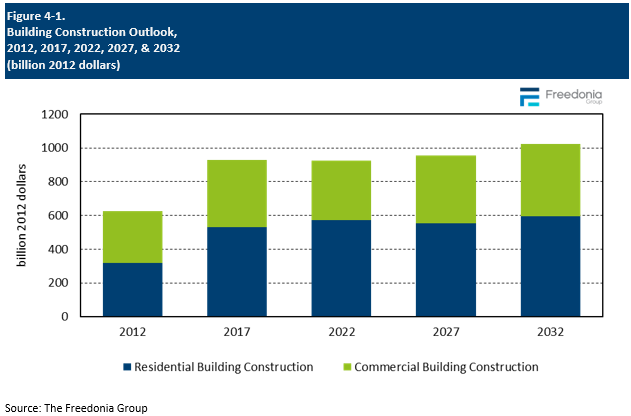
Real building construction activity is forecast to increase by an average of nearly 1.0% per year through 2027 to $954 billion. Residential building construction is expected to stagnate because expenditures declined again in 2023 following a sharp drop in 2022, which was the result of:
-
elevated interest rates and inflated material prices causing a decline in conventional housing starts
-
existing homeowners having already invested in renovation activities in 2020 and 2021
However, residential building construction will return to growth in 2024 as inflationary pressures retreat and the limited inventory of existing houses for sale will support demand for new single-family units. Elevated interest rates will remain an obstacle for residential construction in the near-term.
Commercial building construction is anticipated to rebound from the pandemic-induced losses incurred between 2017 and 2022, thereby supporting the construction of manufacturing and warehouse facilities and office, retail, and lodging sites. Building owners are also expected to engage in renovations that had been delayed during previous years.
Check out our recent discussion of Gutter Guards as well!
US demand for gutters and downspouts is forecast to rise less than 1.0% annually to 2.1 billion linear feet in 2027. While this rate of increase is not especially strong, it will represent a return to growth following the declines of the previous period, which were negatively impacted by a moderation in residential building construction in 2022. Rebounding commercial building construction will provide opportunities for gutter and downspout sales, as will an increase in single-family housing starts and improvement and repair activity in the latter part of the forecast period.
In value terms, demand is expected to grow 2.7% annually to $8.3 billion – a significant deceleration from the 2017-2022 period; market value in that span was boosted by price surges in 2021 and 2022, which resulted from a combination of supply chain issues and rising raw material costs.
Following Initial Weakness, Residential Market Will See Gains in Latter Part of Forecast Period
Following significantly elevated levels of gutter and downspout sales in 2020 and 2021, real demand in 2022 moderated as high interest rates and economic uncertainty began to weigh on the housing industry. Demand declined sharply in 2023 as housing starts fell and improvement and repair activity declined. However, these underlying indicators are expected to improve through the rest of the forecast period, with single-family housing starts returning to growth as interest rates ease and improvement and repair activity steadily rising, supporting the replacement of aging gutters and downspouts and the addition of gutter guards on existing homes.
Gutter Guards Will Grow in Popularity Among Homeowners
Demand for gutter guards – which are designed to keep leaves, pine needles, and other debris out of gutters – will rise as homeowners increasingly install these items to minimize the need to periodically clean gutters, a time-consuming and potentially dangerous task. Aluminum gutter guards will continue to account for the largest share of demand due to their light weight, which support their use among both professionals and DIYers. However, plastic gutter guards will continue to penetrate the market due to the wide variety of gutter guard options offered in plastic and the lower cost of these products compared to those made from aluminum and other metals.
Historical Market Trends
For the most part, sales of gutter and downspout products are dependent upon new building construction and a relatively predictable replacement cycle for existing buildings, with the residential aftermarket accounting for the vast majority of sales.
Demand tends to track changes in building construction activity although growth for gutters and downspouts is generally slower than that for overall construction, due primarily to the commodity nature of the products and the maturity of the market.
However, spending on gutter and downspout products can exceed growth in building construction during downturns due to:
-
the need to repair or replace gutters and downspouts in case of damage, which is not a discretionary expense for most homeowners
-
outbreaks of severe weather (such as hurricanes and tornadoes) that can cause damage to structures across a wide area, as demand for gutter systems may rise even if overall construction spending contracts
- the modest cost of gutter replacement compared to other home improvement projects can be attractive to homeowners who want to upgrade the appearance or function of their homes

Products Overview
Market Value
Market value for gutter system products – including gutters, downspouts, gutter guards, and related hardware and accessories – is projected to rise 2.7% per year to $8.3 billion in 2027. Advances will come from:
-
real growth in linear feet
-
increases in some raw material prices, notably aluminum and steel
Most rainware products are specified due to their durability and functionality, not for aesthetics; therefore, consumers generally choose gutters and downspouts based on price. This limits opportunities for value growth, as few consumers will opt for costly products like copper gutters and downspouts.
Demand for gutter guards does not necessarily track that of gutters. In fact, it is heavily dependent on residential applications because many homeowners add these products to existing gutters at a later date. This has fostered a secondary market; makers of gutter guard systems offer their products at premium prices, often having their own network of contractors who install their products to specification.. However, many gutter guards (especially those installed by DIY homeowners) are fairly inexpensive, which serves as a check on overall value demand advances.

Materials Overview
Gutter and downspout products are manufactured from a range of materials, including:
-
metals (aluminum, steel, copper, and zinc)
-
plastics (primarily polyvinyl chloride)
-
wood (mostly cedar and redwood)
-
fiberglass
-
concrete
Gutter and downspout materials must be rigid, corrosion, and impact resistant, and able to tolerate extremes of heat or cold.
Cost is among the most important factors that affects choice of rainware material. Materials are sold at a wide range of price points:
-
Plastics are the least expensive per foot.
-
Metals like aluminum and steel are mid-priced, though the cost of the latter has risen faster than the former over the last decade; that trend is currently intensified by higher tariffs on steel.
-
Copper, zinc, and wood are the most expensive (and least used) materials.
Aluminum will continue to be the most widely used gutter and downspout material. Steel products account for a smaller portion of demand, reflecting their low-volume use in the large residential market.
Use of plastic is limited by its low durability compared to metal, but cost-competitive vinyl rainware products are specified by some homeowners. Demand growth for plastic gutter and downspout products will come from the rising market penetration of gutter guards, a broad range of which – from the lowest priced types to costly proprietary systems – use plastic for its versatility and compatibility with all gutter types.
Gutter and downspout products made from copper and other materials account for a larger share of market value than volume because they are costly. Products made from these materials only account for a small share of total demand volume (and will continue to do so) due to both that expense and the fact that aluminum and steel can often provide the necessary performance.

Building Construction Outlook
For the most part, sales of gutter and downspout products are dependent upon new building construction and a relatively predictable replacement cycle for existing buildings. With the residential aftermarket accounting for the vast majority of sales.
Demand tends to track changes in building construction activity, although growth for gutters and downspouts is generally slower than overall construction. This is largely attributable to the commodity nature of the products and the maturity of the market.
Real building construction activity is forecast to increase by an average of nearly 1.0% per year through 2027 to $954 billion. Residential building construction is expected to stagnate because expenditures declined again in 2023 following a sharp drop in 2022, which was the result of:
-
elevated interest rates and inflated material prices causing a decline in conventional housing starts
-
existing homeowners having already invested in renovation activities in 2020 and 2021
However, residential building construction will return to growth in 2024 as inflationary pressures retreat and the limited inventory of existing houses for sale will support demand for new single-family units. Elevated interest rates will remain an obstacle for residential construction in the near-term.
Commercial building construction is anticipated to rebound from the pandemic-induced losses incurred between 2017 and 2022, thereby supporting the construction of manufacturing and warehouse facilities and office, retail, and lodging sites. Building owners are also expected to engage in renovations that had been delayed during previous years.

- Executive Summary
- Figure 1-1. US Gutters & Downspouts Market
- Short-Term Analysis
- Economic Forecast
- Table | Macroeconomic Indicators, 2020 - 2024
- Figure 2-1. Real GDP by Economic Sector, 2020 - 2023
- Short-Term Building Construction Outlook
- Table | Construction Expenditures, 2020 - 2024
- Short-Term Gutter & Downspout Industry Trends
- Table | Annual Gutter & Downspout Demand by Product, 2020 - 2024
- Table | Annual Gutter & Downspout Demand by Market, 2020 - 2024
- Figure 2-2. Gutter & Downspout Demand, 2020 - 2024
- Economic Forecast
- Overview
- Study Scope
- Figure 3-1. Gutters & Downspouts: Product Examples
- Historical Market Trends
- Table | Gutter & Downspout Demand, 2012 - 2022
- Figure 3-2. Gutter & Downspout Demand, 2000 - 2022
- Products Overview
- Linear Feet
- Table | Gutter, Downspout & Gutter Guard Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter, Downspout & Gutter Guard Demand by Product, 2019 - 2026
- Figure 3-3. Gutter, Downspout & Gutter Guard Demand by Product, 2012, 2017, 2022, 2027, &2032
- Market Value
- Table | Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter & Downspout Demand by Product, 2019 - 2026
- Figure 3-4. Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Linear Feet
- Materials Overview
- Table | Gutter & Downspout Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter & Downspout Demand by Material, 2019 - 2026
- Figure 3-5. Gutter & Downspout Demand by Material, 2012, 2017, 2022, 2027, &2032
- Markets Overview
- Table | Gutter & Downspout Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter & Downspout Demand by Market, 2019 - 2026
- Figure 3-6. Gutter & Downspout Demand by Market, 2012, 2017, 2022, 2027, &2032
- Inflation & Pricing Trends
- Table | Gutter & Downspout Prices, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter & Downspout Prices, 2019 - 2026
- Figure 3-7. Gutter & Downspout Pricing, 2012 - 2032
- Study Scope
- Factors Impacting Gutter & Downspout Demand
- Building Construction Outlook
- Figure 4-1. Building Construction Outlook, 2012, 2017, 2022, 2027, &2032
- Roofing Drainage Systems Overview
- Drainage Functions & Strategies
- Steep Slope Systems
- Low Slope Systems
- Labor Availability
- Regulatory Considerations
- Water Management Requirements
- ENERGY STAR Certification
- Wildfire Codes
- Sustainability Initiatives
- Recycling & Recycled Content
- Rainwater Harvesting Applications
- Building Construction Outlook
- Gutters
- Scope & Product Description
- Figure 5-1. Gutter Styles & Characteristics: K-Style, Half-Round, &Box
- Seamless vs. Preformed Gutters
- Table | Gutter Demand by Construction Method, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter Demand by Construction Method, 2019 - 2026
- Markets Overview
- Table | Gutter Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter Demand by Market, 2019 - 2026
- Materials Competition
- Table | Gutter Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter Demand by Material, 2019 - 2026
- Demand by Region
- Table | Gutter Demand by Region, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter Demand by Region, 2019 - 2026
- Leading Suppliers & Market Share
- Figure 5-2. Gutter Market Share by Company, 2022
- Scope & Product Description
- Downspouts
- Scope & Product Description
- Figure 6-1. Downspout Configurations by Material
- Seamless vs. Preformed Downspouts
- Table | Downspout Demand by Construction Method, 2012, 2017, 2022, 2027, &2032
- Table | Annual Downspout Demand by Construction Method, 2019 - 2026
- Markets Overview
- Table | Downspout Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Downspout Demand by Market, 2019 - 2026
- Materials Competition
- Table | Downspout Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Downspout Demand by Material, 2019 - 2026
- Demand by Region
- Table | Downspout Demand by Region, 2012, 2017, 2022, 2027, &2032
- Table | Annual Downspout Demand by Region, 2019 - 2026
- Leading Suppliers & Market Share
- Figure 6-2. Downspout Market Share by Company, 2022
- Scope & Product Description
- Gutter Guards
- Scope & Product Description
- Figure 7-1. Gutter Guard Types
- Markets Overview
- Table | Gutter Guard Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter Guard Demand by Market, 2019 - 2026
- Demand by Type (Meshes & Screens, Hoods & Covers, &Foams & Bristles)
- Table | Gutter Guard Demand by Type, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter Guard Demand by Type, 2019 - 2026
- Materials Competition
- Table | Gutter Guard Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter Guard Demand by Material, 2019 - 2026
- Demand by Region
- Table | Gutter Guard Demand by Region, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter Guard Demand by Region, 2019 - 2026
- Leading Suppliers & Market Share
- Figure 7-2. Gutter Guard Market Share by Company, 2022
- Scope & Product Description
- Hardware & Accessories
- Scope & Product Description
- Figure 8-1. Gutter & Downspout Hardware & Accessories
- Markets Overview
- Table | Gutter & Downspout Hardware & Accessories Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter & Downspout Hardware & Accessories Demand by Market, 2019 - 2026
- Materials Competition
- Table | Gutter & Downspout Hardware & Accessories Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter & Downspout Hardware & Accessories Demand by Material, 2019 - 2026
- Demand by Product
- Demand by Region
- Table | Gutter & Downspout Hardware & Accessories Demand by Region, 2012, 2017, 2022, 2027, &2032
- Table | Gutter & Downspout Hardware & Accessories Demand by Region, 2019 - 2026
- Leading Suppliers & Market Share
- Figure 8-2. Gutter & Downspout Hardware & Accessories Market Share by Company, 2022
- Scope & Product Description
- Aluminum Gutters & Downspouts
- Product Characteristics
- Table | Aluminum Gutter & Downspout Product Characteristics
- Figure 9-1. Aluminum Share of Gutter & Downspout Demand, 2022
- Demand by Product
- Table | Aluminum Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Aluminum Gutter & Downspout Demand by Product, 2019 - 2026
- Demand by Market
- Table | Aluminum Gutter & Downspout Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Aluminum Gutter & Downspout Demand by Market, 2019 - 2026
- Demand by Region
- Table | Aluminum Gutter & Downspout Demand by Region, 2012, 2017, 2022, 2027, &2032
- Table | Annual Aluminum Gutter & Downspout Demand by Region, 2019 - 2026
- Leading Suppliers
- Product Characteristics
- Steel Gutters & Downspouts
- Product Characteristics
- Table | Steel Gutter & Downspout Product Characteristics
- Figure 10-1. Steel Share of Gutter & Downspout Demand, 2022
- Demand by Product
- Table | Steel Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Steel Gutter & Downspout Demand by Product, 2019 - 2026
- Demand by Market
- Table | Steel Gutter & Downspout Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Steel Gutter & Downspout Demand by Market, 2019 - 2026
- Demand by Region
- Table | Steel Gutter & Downspout Demand by Region, 2012, 2017, 2022, 2027, &2032
- Table | Annual Steel Gutter & Downspout Demand by Region, 2019 - 2026
- Leading Suppliers
- Product Characteristics
- Plastic Gutters & Downspouts
- Product Characteristics
- Table | Plastic Gutter & Downspout Product Characteristics
- Figure 11-1. Plastic Share of Gutter & Downspout Demand, 2022
- Demand by Product
- Table | Plastic Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Gutter & Downspout Demand by Product, 2019 - 2026
- Demand by Market
- Table | Plastic Gutter & Downspout Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Gutter & Downspout Demand by Market, 2019 - 2026
- Demand by Region
- Table | Plastic Gutter & Downspout Demand by Region, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Gutter & Downspout Demand by Region, 2019 - 2026
- Leading Suppliers
- Product Characteristics
- Copper, Zinc, &Other Materials
- Product Characteristics
- Table | Copper, Zinc, &Other Materials Gutter & Downspout Product Characteristics
- Figure 12-1. Copper, Zinc & Other Materials Share of Gutter & Downspout Demand, 2022
- Demand by Product
- Table | Copper, Zinc, &Other Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Copper, Zinc, &Other Gutter & Downspout Demand by Product, 2019 - 2026
- Demand by Market
- Table | Copper, Zinc, &Other Gutter & Downspout Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Copper, Zinc, &Other Gutter & Downspout Demand by Market, 2019 - 2026
- Demand by Region
- Table | Copper, Zinc, &Other Gutter & Downspout Demand by Region, 2012, 2017, 2022, 2027, &2032
- Table | Annual Copper, Zinc, &Other Gutter & Downspout Demand by Region, 2019 - 2026
- Leading Suppliers
- Product Characteristics
- Residential Gutters & Downspouts
- Market Scope
- Demand by Application
- Table | Residential Gutter & Downspout Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Residential Gutter & Downspout Demand by Application, 2019 - 2026
- Figure 13-1. Residential Gutter & Downspout Demand by Application, 2009 - 2032
- New Residential
- Demand Outlook
- Figure 13-2. New Residential Gutter & Downspout Demand, 2009 - 2032
- Demand by Product
- Table | New Residential Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual New Residential Gutter & Downspout Demand by Product, 2019 - 2026
- Demand by Material
- Table | New Residential Gutter & Downspout Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual New Residential Gutter & Downspout Demand by Material, 2019 - 2026
- Demand Outlook
- Residential Improvement & Repair
- Demand Outlook
- Figure 13-3. Residential Improvement & Repair Gutter & Downspout Demand, 2009 - 2032
- Demand by Product
- Table | Residential Improvement & Repair Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Residential Improvement & Repair Gutter & Downspout Demand by Product, 2019 - 2026
- Demand by Material
- Table | Residential Improvement & Repair Gutter & Downspout Demand by Material, 2012, 2017, 2022, 2027, &203
- Table | Annual Residential Improvement & Repair Gutter & Downspout Demand by Material, 2019 - 2026
- Demand Outlook
- Demand by Product
- Table | Residential Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Residential Gutter & Downspout Demand by Product, 2019 - 2026
- Figure 13-4. Residential Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Demand by Material
- Table | Residential Gutter & Downspout Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Residential Gutter & Downspout Demand by Material, 2019 - 2026
- Demand by Region
- Table | Residential Gutter & Downspout Demand by Region, 2012, 2017, 2022, 2027, &2032
- Table | Annual Residential Gutter & Downspout Demand by Region, 2019 - 2026
- Commercial Gutters & Downspouts
- Market Scope
- Demand by Application
- Table | Commercial Gutter & Downspout Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Commercial Gutter & Downspout Demand by Application, 2019 - 2026
- Figure 14-1. Commercial Gutter & Downspout Demand by Application, 2009 - 2032
- New Commercial
- Demand Outlook
- Figure 14-2. New Commercial Gutter & Downspout Demand, 2009 - 2032
- Demand by Product
- Table | New Commercial Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual New Commercial Gutter & Downspout Demand by Product, 2019 - 2026
- Demand by Material
- Table | New Commercial Gutter & Downspout Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual New Commercial Gutter & Downspout Demand by Material, 2019 - 2026
- Demand Outlook
- Commercial Improvement & Repair
- Demand Outlook
- Figure 14-3. Commercial Improvement & Repair Gutter & Downspout Demand, 2009 - 2032
- Demand by Product
- Table | Commercial Improvement & Repair Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Commercial Improvement & Repair Gutter & Downspout Demand by Product, 2019 - 2026
- Demand by Material
- Table | Commercial Improvement & Repair Gutter & Downspout Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Commercial Improvement & Repair Gutter & Downspout Demand by Material, 2019 - 2026
- Demand Outlook
- Demand by Product
- Table | Commercial Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Commercial Gutter & Downspout Demand by Product, 2019 - 2026
- Figure 14-4. Commercial Gutter & Downspout Demand by Product, 2012, 2017, 2022, 2027, &2032
- Demand by Material
- Table | Commercial Gutter & Downspout Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Commercial Gutter & Downspout Demand by Material, 2019 - 2026
- Demand by Region
- Table | Commercial Gutter & Downspout Demand by Region, 2012, 2017, 2022, 2027, &2032
- Table | Annual Commercial Gutter & Downspout Demand by Region, 2019 - 2026
- Regional Trends
- Demand by Region
- Table | Gutter & Downspout Demand by Region, 2012, 2017, 2022, 2027, &2032
- Table | Annual Gutter & Downspout Demand by Region, 2019 - 2026
- Figure 15-1. Gutter & Downspout Demand by Region, 2012, 2017, 2022, 2027, &2032,
- Northeast
- Demand by Subregion & Market
- Table | Northeast: Gutter & Downspout Demand by Subregion & Market, 2012, 2017, 2022, 2027, &2032
- Table | Northeast: Annual Gutter & Downspout Demand by Subregion & Market, 2019 - 2026
- Figure 15-2. Northeast: Gutter & Downspout Market Position
- New England
- Figure 15-3. New England: Key Factors Impacting Demand for Gutter & Downspout Products
- Middle Atlantic
- Figure 15-4. Middle Atlantic: Key Factors Impacting Demand for Gutter & Downspout Products
- Demand by Subregion & Market
- Midwest
- Demand by Subregion & Market
- Table | Midwest: Gutter & Downspout Demand by Subregion & Market, 2012, 2017, 2022, 2027, &2032
- Table | Midwest: Annual Gutter & Downspout Demand by Subregion & Market, 2019 - 2026
- Figure 15-5. Midwest: Gutter & Downspout Market Position
- East North Central
- Figure 15-6. East North Central: Key Factors Impacting Demand for Gutter & Downspout Products
- West North Central
- Figure 15-7. West North Central: Key Factors Impacting Demand for Gutter & Downspout Products
- Demand by Subregion & Market
- South
- Demand by Subregion & Market
- Table | South: Gutter & Downspout Demand by Subregion & Market, 2012, 2017, 2022, 2027, &2032
- Table | South: Annual Gutter & Downspout Demand by Subregion & Market, 2019 - 2026
- Figure 15-8. South: Gutter & Downspout Market Position
- South Atlantic
- Figure 15-9. South Atlantic: Key Factors Impacting Demand for Gutter & Downspout Products
- East South Central
- Figure 15-10. East South Central: Key Factors Impacting Demand for Gutter & Downspout Products
- West South Central
- Figure 15-11. West South Central: Key Factors Impacting Demand for Gutter & Downspout Products
- Demand by Subregion & Market
- West
- Demand by Subregion & Market
- Table | West: Gutter & Downspout Demand by Subregion & Market, 2012, 2017, 2022, 2027, &2032
- Table | West: Annual Gutter & Downspout Demand by Subregion & Market, 2019 - 2026
- Figure 15-12. West Gutter & Downspout Market Position
- Mountain
- Figure 15-13. Mountain: Key Factors Impacting Demand for Gutter & Downspout Products
- Pacific
- Figure 15-14. Pacific: Key Factors Impacting Demand for Gutter & Downspout Products
- Demand by Subregion & Market
- Demand by Region
- Industry Structure
- Key Findings & Industry Composition
- Table | US Gutter & Downspout Sales by Company, 2022
- Market Share
- Figure 16-1. US Gutter & Downspout Market Share by Company, 2022
- Figure 16-2. US Gutter & Downspout Market: Leading Supplier, 2022
- Figure 16-3. US Gutter & Downspout Market: Second Leading Supplier, 2022
- Figure 16-4. US Gutter & Downspout Market: Third Leading Supplier, 2022
- Figure 16-5. US Gutter & Downspout Market: Fourth Leading Supplier, 2022
- Figure 16-6. US Gutter & Downspout Market: Co-Fifth Leading Supplier, 2022
- Figure 16-7. US Gutter & Downspout Market: Co-Fifth Leading Supplier, 2022
- Mergers & Acquisitions
- Table | Selected Mergers & Acquisitions
- List of Industry Participants
- Table | Selected Industry Participants
- Key Findings & Industry Composition
- Appendix
- Report Details
- Table | US Geographic Regions & Subregions
- Table | Relevant Industry Codes
- Table | Relevant HS/HTS Codes
- Definitions
- Abbreviations
- Table | Abbreviations & Acronyms Used in Study
- Freedonia Methodology
- Study-Specific Methodology
- Sources
- Associations & Agencies
- Related Studies & Reports
- Macroeconomic Assumptions
- Economic Environment
- Table | Macroeconomic Indicators, 2012, 2017, 2022, 2027, &2032
- Demographic Trends
- Table | Population & Households, 2012, 2017, 2022, 2027, &2032
- Building Construction
- Table | Building Construction Expenditures, 2012, 2017, 2022, 2027, &2032
- Residential Building Construction
- Table | Residential Building Construction Expenditures, 2012, 2017, 2022, 2027, &2032
- Residential Improvement & Repairs
- Table | Residential Improvement & Repair Expenditures, 2012, 2017, 2022, 2027, &2032
- Commercial Building Construction
- Table | Commercial Building Construction Expenditures, 2012, 2017, 2022, 2027, &2032
- Commercial Improvement & Repairs
- Table | Commercial Building Improvement & Repair Expenditures, 2012, 2017, 2022, 2027, &2032
- Housing Stock
- Table | Housing Stock by Type, 2012, 2017, 2022, 2027, &2032
- Consumer Spending
- Table | Personal Consumption Expenditures, 2012 - 2032
- Economic Environment
- Report Details
Gutters can be fabricated in one of two ways: Seamless gutters are made on a truck-mounted machine at the jobsite and installed by the contractor and preformed gutters are factory-made in certain widths and lengths and then shipped either to a retailer or contractor.
Demand for gutter guards in value terms is expected to rise 3.0% per year to $1.1 billion in 2027.
Rain harvesting is popular in dry areas of the West and South but is growing in popularity elsewhere in the US. While some homebuilders add rain harvesting equipment to create more environmentally friendly residences, in most cases these systems are installed by homeowners aiming to reduce water consumption or to be more self-sufficient. Nearly all states have active rainwater harvesting programs.
The leading suppliers of gutters and downspouts in the US include OmniMax International, Leaf Home Solutions, Gibraltar Industries, Spectra Metal (via its subsidiary Spectra Gutter Systems), TopBuild, and Cornerstone Building Brands.