US Plastic Packaging for Food
This study examines the US market for plastic food packaging, defined as primary and secondary packaging materials sold to food manufacturers, primarily for products targeted at retail or foodservice markets. Historical data are provided for 2012, 2017, and 2022, with forecasts through 2027 and 2032. Annual data is provided for 2018-2026.
Free Sample Report
Request a free sample of this report and our team will email it to you.
Report Overview
Featuring 96 tables and 49 figures – available in Excel and Powerpoint! Learn More
This study examines the US market for plastic food packaging, defined as primary and secondary packaging materials sold to food manufacturers, primarily for  products targeted at retail or foodservice markets. Historical data are provided for 2012, 2017, and 2022, with forecasts through 2027 and 2032. Annual data is provided for 2018-2026. Data are provided in current dollar value. Also provided is an analysis of key industry players.
See our discussion regarding Plastic Food Packaging
Sustainability Will Have Nuanced Effects on Plastic Packaging
The growing impact of sustainability on the packaging market will affect plastic in several distinct ways. Despite plastic being the leading target for sustainability conversions, end users continue to value plastic over other materials based on cost and performance. However, manufacturers have employed several techniques to improve the environmental profile of their products in recent years, including:
-
incorporating greater amounts of recycled content
-
ensuring their plastic packaging is recyclable, with a trend toward monomaterial packaging becoming more prevalent
-
light weighting and source reduction
Additionally, bioplastics will play a more significant role in the plastic food packaging market going forward. However, bioplastics must overcome price and scalability issues in order to become truly competitive with conventional plastics.
Flexible Packaging Will Continue to Gain Favor Among End Users
Demand for flexible plastic food packaging will be supported by both its performance benefits and favorable environmental profile compared to rigid packaging. Flexible plastic packaging is highly versatile, conforming to various product shapes, sizes, and applications, allowing for widespread market penetration. Moreover, it often requires fewer resources to manufacture and produces less waste.
Gains will also be driven by the increasing popularity of stand-up pouches, which are valued for their aesthetics and portability. Additionally, newer flexible packaging products, such as vacuum skin packaging and brick packs in meat packaging and bag-in-box formats (which use plastic bladders) for foodservice and retail, will support demand growth.
Healthy Growth in Prepared Foods and Candy & Confections Will Support Demand
While meat, poultry, and seafood will continue to account for most of plastic’s absolute gains, faster growing markets such as prepared foods and candy and confections will support even greater demand for plastic food packaging overall, driven by:
-
expanding availability of fresh/refrigerated prepared foods like grab-and-go complete meals, salads, and sandwiches at grocery and convenience stores
-
increasing sales of pre-packaged refrigerated meals (including prepared meats and pasta dishes) from leading food companies
-
the trend toward smaller individually wrapped versions of larger candies
- shift to higher-value packaging formats such as stand-up pouches and two-piece containers
Historical Market Trends
Shifts in demand for plastic food packaging from year to year are determined by a few factors, primarily related to the production and marketing of food products. These activities in turn are influenced by:
-
demographic trends such as age, average household size, and levels of disposable income
-
consumer spending on food and the balance between at-home and away-from-home meals
-
food preferences (e.g., demand for enhanced convenience or for organic products)
-
restaurant and other foodservice industry revenues
In addition, several competitive variables determine the mix of packaging types used and their cost, including:
-
raw material and conversion costs
-
changes in the mix of foods being packaged, particularly in terms of food format (canned, dried, frozen, fresh)
-
trends in packaging size and format, such as shifts toward smaller single-serving packages, family size units, or multipacks
-
the proportion of food that is sold via retail channels versus foodservice establishments
-
environmental and regulatory factors, including trends such as source reduction, the use of recycled content, and recyclability
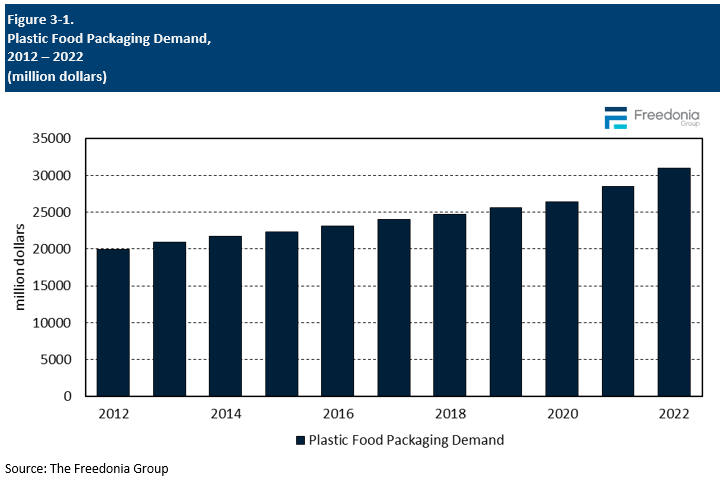
Plastic food packaging demand growth in 2021 and 2022 experienced a strong acceleration in value terms compared to previous years due to the significant inflation following supply chain issues caused by the 2020 pandemic.
Demand by Packaging Format (Rigid vs. Flexible)
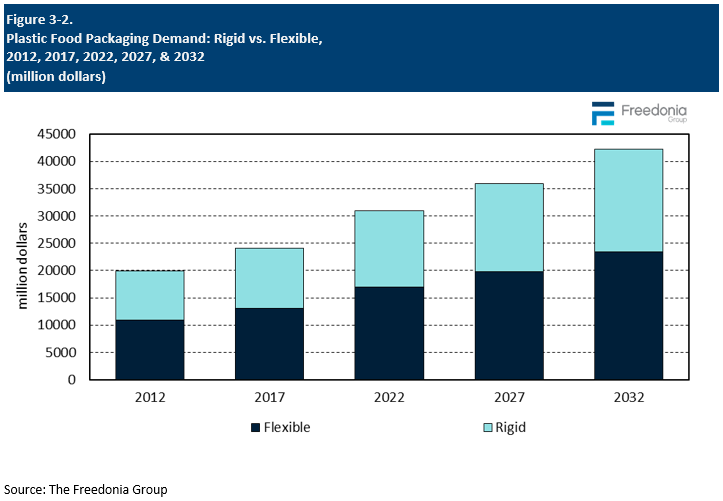
In the broadest terms, food packaging includes rigid and flexible products, with competition coming both between these two broad types and among the products within each of those categories. Factors that determine the mix of packaging at this level include cost and product performance, though sustainability initiatives are increasingly important.
Demand for plastic food packaging overall is forecast to rise 3.0% per year to $35.9 billion in 2027. In addition to overall growth in food production, the mix of foods produced, and trends in packaging end uses, other factors specifically driving growth in plastic packaging usage include:
-
sustainability initiatives, which promotes demand for plastic packaging seen as more environmentally friendly, such as bioplastics, which are more expensive than traditional products
-
the popularity of single-serving and snack sizes, which are more intensive users of packaging (in terms of packaging cost per volume of food produced)
-
the need for food product differentiation, which drives demand for higher priced packaging with value-added features or improved shelf-appeal
-
recent inflationary pressures, with some manufacturers taking to utilizing “shrinkflation” to cut costs rather than increase prices, increasing unit demand for these products
-
a general move toward higher-value packaging due to performance improvements, such as increasing shelf life or reducing leakage
-
the continued penetration of aseptic processing over more traditional processing methods, which elicits the need for certain higher-value packaging formats such as pouches and bag-in-box
Pricing Trends
Pricing is an important factor in selecting packaging for a particular food application. Price competition in the industry is intense, due to the prevalence of relatively low-technology, commodity-type products.
The cost of raw materials, such as plastic resins and petroleum, is the primary determinant of pricing for plastic food packaging, as they typically represent at least half of the final packaging price.
Other key factors influencing the price of plastic food packaging include:
-
the degree of lightweighting and downsizing activity – efforts that cut costs per unit by reducing the packaging size either through using lighter-weight packaging or marginally decreasing product volume
-
the presence of value-added features such as spouts and reclosable zippers
-
the packaging product mix, both in terms of package size and plastic composition
-
supply chain pressures that squeeze packaging producers between large raw material suppliers on one end and large food processors on the other, leaving them less options for pricing flexibility
-
pressure to improve sustainability, which can result in the use of higher cost materials such as bioplastics
In 2021, the price of raw material inputs used in the production of plastic food packaging increased dramatically due to shortages caused by supply chain issues, leading to a large increase in end pricing of food packaging products. These price increases continued through most of 2022, before mostly flattening in 2023. Bioplastics were less affected as their growing economies of scale helped offset the impact of increased raw material inputs.
Going forward, plastic packaging pricing is expected to normalize and is forecast to see price growth in line with historical trends beginning in 2024.
Sustainability in Packaging
While environmental concerns have impacted the choice of packaging in the food industry to some degree for decades, sustainability has recently become one of the most important trends in the global manufacturing industry. Plastic packaging is a high-profile target for those looking for sustainability improvements because it is:
-
used pervasively by most industries worldwide
-
is generally meant to be disposable
-
often finds its way into the environment
However, the pursuit of sustainability is not straightforward, as packaging must also continue to provide acceptable performance, especially in the food industry where it plays a key role in maintaining food quality and safety. In addition, for foods to remain affordable and food companies to remain profitable, packaging costs will remain a key variable in packaging choice.
To understand whether a specific type of packaging is truly sustainable, other factors must also be considered beyond the renewable nature of its raw materials and the final packaging’s levels of recyclability or compostability. These factors include:
-
how much energy or water is used in manufacturing processes
-
packaging’s impact on final product transportation costs
At present, there is no one perfect packaging choice for all applications. Most packaging materials currently on the market have advantages and disadvantages, and even newer products are being introduced primarily for their sustainability merits. Packaging end users must choose the product that provides the best balance of cost, performance, and environmental impact and then find a way to help customers understand the benefits of that packaging choice.
See our discussion regarding Plastic Food Packaging
Demand for food packaging made from plastic is forecast to increase 3.0% per year to $36 billion in 2027. Plastic will continue to be the largest and fastest growing of the major food packaging materials – thanks to its versatile nature, low cost, and excellent performance – although other, more sustainable materials like molded fiber will provide increasing competition going forward.Sustainability Will Have Nuanced Effects on Plastic Packaging
The growing impact of sustainability on the packaging market will affect plastic in several distinct ways. Despite plastic being the leading target for sustainability conversions, end users continue to value plastic over other materials based on cost and performance. However, manufacturers have employed several techniques to improve the environmental profile of their products in recent years, including:
-
incorporating greater amounts of recycled content
-
ensuring their plastic packaging is recyclable, with a trend toward monomaterial packaging becoming more prevalent
-
light weighting and source reduction
Additionally, bioplastics will play a more significant role in the plastic food packaging market going forward. However, bioplastics must overcome price and scalability issues in order to become truly competitive with conventional plastics.
Flexible Packaging Will Continue to Gain Favor Among End Users
Demand for flexible plastic food packaging will be supported by both its performance benefits and favorable environmental profile compared to rigid packaging. Flexible plastic packaging is highly versatile, conforming to various product shapes, sizes, and applications, allowing for widespread market penetration. Moreover, it often requires fewer resources to manufacture and produces less waste.
Gains will also be driven by the increasing popularity of stand-up pouches, which are valued for their aesthetics and portability. Additionally, newer flexible packaging products, such as vacuum skin packaging and brick packs in meat packaging and bag-in-box formats (which use plastic bladders) for foodservice and retail, will support demand growth.
Healthy Growth in Prepared Foods and Candy & Confections Will Support Demand
While meat, poultry, and seafood will continue to account for most of plastic’s absolute gains, faster growing markets such as prepared foods and candy and confections will support even greater demand for plastic food packaging overall, driven by:
-
expanding availability of fresh/refrigerated prepared foods like grab-and-go complete meals, salads, and sandwiches at grocery and convenience stores
-
increasing sales of pre-packaged refrigerated meals (including prepared meats and pasta dishes) from leading food companies
-
the trend toward smaller individually wrapped versions of larger candies
- shift to higher-value packaging formats such as stand-up pouches and two-piece containers
Historical Market Trends
Shifts in demand for plastic food packaging from year to year are determined by a few factors, primarily related to the production and marketing of food products. These activities in turn are influenced by:
-
demographic trends such as age, average household size, and levels of disposable income
-
consumer spending on food and the balance between at-home and away-from-home meals
-
food preferences (e.g., demand for enhanced convenience or for organic products)
-
restaurant and other foodservice industry revenues
In addition, several competitive variables determine the mix of packaging types used and their cost, including:
-
raw material and conversion costs
-
changes in the mix of foods being packaged, particularly in terms of food format (canned, dried, frozen, fresh)
-
trends in packaging size and format, such as shifts toward smaller single-serving packages, family size units, or multipacks
-
the proportion of food that is sold via retail channels versus foodservice establishments
-
environmental and regulatory factors, including trends such as source reduction, the use of recycled content, and recyclability
Plastic food packaging demand growth in 2021 and 2022 experienced a strong acceleration in value terms compared to previous years due to the significant inflation following supply chain issues caused by the 2020 pandemic.

Demand by Packaging Format (Rigid vs. Flexible)
In the broadest terms, food packaging includes rigid and flexible products, with competition coming both between these two broad types and among the products within each of those categories. Factors that determine the mix of packaging at this level include cost and product performance, though sustainability initiatives are increasingly important.
Demand for plastic food packaging overall is forecast to rise 3.0% per year to $35.9 billion in 2027. In addition to overall growth in food production, the mix of foods produced, and trends in packaging end uses, other factors specifically driving growth in plastic packaging usage include:
-
sustainability initiatives, which promotes demand for plastic packaging seen as more environmentally friendly, such as bioplastics, which are more expensive than traditional products
-
the popularity of single-serving and snack sizes, which are more intensive users of packaging (in terms of packaging cost per volume of food produced)
-
the need for food product differentiation, which drives demand for higher priced packaging with value-added features or improved shelf-appeal
-
recent inflationary pressures, with some manufacturers taking to utilizing “shrinkflation” to cut costs rather than increase prices, increasing unit demand for these products
-
a general move toward higher-value packaging due to performance improvements, such as increasing shelf life or reducing leakage
-
the continued penetration of aseptic processing over more traditional processing methods, which elicits the need for certain higher-value packaging formats such as pouches and bag-in-box

Pricing Trends
Pricing is an important factor in selecting packaging for a particular food application. Price competition in the industry is intense, due to the prevalence of relatively low-technology, commodity-type products.
The cost of raw materials, such as plastic resins and petroleum, is the primary determinant of pricing for plastic food packaging, as they typically represent at least half of the final packaging price.
Other key factors influencing the price of plastic food packaging include:
-
the degree of lightweighting and downsizing activity – efforts that cut costs per unit by reducing the packaging size either through using lighter-weight packaging or marginally decreasing product volume
-
the presence of value-added features such as spouts and reclosable zippers
-
the packaging product mix, both in terms of package size and plastic composition
-
supply chain pressures that squeeze packaging producers between large raw material suppliers on one end and large food processors on the other, leaving them less options for pricing flexibility
-
pressure to improve sustainability, which can result in the use of higher cost materials such as bioplastics
In 2021, the price of raw material inputs used in the production of plastic food packaging increased dramatically due to shortages caused by supply chain issues, leading to a large increase in end pricing of food packaging products. These price increases continued through most of 2022, before mostly flattening in 2023. Bioplastics were less affected as their growing economies of scale helped offset the impact of increased raw material inputs.
Going forward, plastic packaging pricing is expected to normalize and is forecast to see price growth in line with historical trends beginning in 2024.
Sustainability in Packaging
While environmental concerns have impacted the choice of packaging in the food industry to some degree for decades, sustainability has recently become one of the most important trends in the global manufacturing industry. Plastic packaging is a high-profile target for those looking for sustainability improvements because it is:
-
used pervasively by most industries worldwide
-
is generally meant to be disposable
-
often finds its way into the environment
However, the pursuit of sustainability is not straightforward, as packaging must also continue to provide acceptable performance, especially in the food industry where it plays a key role in maintaining food quality and safety. In addition, for foods to remain affordable and food companies to remain profitable, packaging costs will remain a key variable in packaging choice.
To understand whether a specific type of packaging is truly sustainable, other factors must also be considered beyond the renewable nature of its raw materials and the final packaging’s levels of recyclability or compostability. These factors include:
-
how much energy or water is used in manufacturing processes
-
packaging’s impact on final product transportation costs
At present, there is no one perfect packaging choice for all applications. Most packaging materials currently on the market have advantages and disadvantages, and even newer products are being introduced primarily for their sustainability merits. Packaging end users must choose the product that provides the best balance of cost, performance, and environmental impact and then find a way to help customers understand the benefits of that packaging choice.
- Executive Summary
- Figure 1-1. Plastic Packaging for Food: Market Outlook
- About This Report
- Report Details
- Study Scope & Product Description
- Figure 2-1. Plastic Food Packaging: Product Examples
- Short-Term Plastic Food Packaging Trends
- Table | Annual Plastic Food Packaging Demand by Application, 2020 - 2024
- Figure 2-2. Annual Plastic Food Packaging Demand, 2020 - 2024
- Overview
- Historical Market Trends
- Table | Plastic Food Packaging Demand, 2012 - 2022
- Figure 3-1. Plastic Food Packaging Demand, 2012 - 2022
- Demand by Packaging Format (Rigid vs. Flexible)
- Table | Plastic Food Packaging Demand: Rigid vs. Flexible, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Packaging Demand: Rigid vs. Flexible, 2019 - 2026
- Figure 3-2. Plastic Food Packaging Demand: Rigid vs. Flexible, 2012, 2017, 2022, 2027, &2032
- Demand by Application
- Table | Plastic Food Packaging Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Packaging Demand by Application, 2019 - 2026
- Figure 3-3. Plastic Food Packaging Demand by Application, 2012, 2017, 2022, 2027, &2032
- Demand by Food Format (Fresh/Refrigerated, Frozen, Canned, Dried)
- Table | Plastic Food Packaging Demand by Food Format, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Packaging Demand by Food Format, 2019 - 2026
- Figure 3-4. Plastic Food Packaging Demand by Food Format, 2012, 2017, 2022, 2027, &2032
- Conventional Resins vs. Bioplastics
- Figure 3-5. Bioplastics Share of Plastic Food Packaging Demand, 2012, 2017, 2022, &2027
- Pricing Trends
- Competitive Products
- Figure 3-6. Comparative Growth: Plastic Food Packaging & Competitive Products, 2022 - 2027
- Historical Market Trends
- Factors Impacting Food Packaging Demand
- Food Production Trends
- Figure 4-1. Food Shipments, 2022 - 2027
- Technology & Innovation
- Food Safety Issues
- Sustainability Initiatives
- Sustainability in Packaging
- Recycling & Recycled Content
- Compostability
- Food Waste
- Consumer Perspectives on Packaging Sustainability
- Packaging Materials Ranked by Perceived Eco-Friendliness
- Table | Consumer Perspectives of Eco-Friendliness of Packaging Materials, 2023
- Table | Features Consumers Especially Look for When Considering "Sustainable" or "Eco-Friendly" Packaging by
- Table | Consumer Attitudes About Recycled Plastics & Biodegradability; By Gender, Age Group, Urban vs. Rural
- Consumer Attitudes About Recycling
- Table | Consumer Attitudes About Recycling; By Gender, Age Group, Urban vs. Rural Setting, &Annual Household
- Consumer Attitudes About Recyclable & Compostable Packaging
- Table | Consumer Attitudes About Recyclable & Compostable Content in Packaging; By Gender, Age Group, Urban
- Priority of Features in Food Packaging
- Table | Consumer Attitudes About Priorities of Features in Packaging, 2023
- Packaging Materials Ranked by Perceived Eco-Friendliness
- Food Production Trends
- Flexible Plastic Packaging
- Scope & Product Description
- Figure 5-1. Flexible Plastic Food Packaging: Product Examples
- Demand by Product
- Table | Flexible Plastic Food Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Flexible Plastic Food Packaging Demand by Product, 2019 - 2026
- Figure 5-2. Flexible Plastic Food Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Pouches
- Table | Plastic Food Pouch Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Pouch Demand by Application, 2019 - 2026
- Bags & Liners
- Table | Plastic Food Bag & Liner Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Bag & Liner Demand by Application, 2019 - 2026
- Wrap
- Table | Plastic Food Wrap Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Wrap Demand by Application, 2019 - 2026
- Lidding
- Table | Plastic Food Lidding Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Lidding Demand by Application, 2019 - 2026
- Other Flexible Plastic Packaging
- Table | Other Flexible Plastic Food Packaging Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Other Flexible Plastic Food Packaging Demand by Application, 2019 - 2026
- Scope & Product Description
- Rigid Plastic Food Packaging
- Scope & Product Description
- Figure 6-1. Rigid Plastic Food Packaging: Product Examples
- Demand by Product
- Table | Rigid Plastic Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Annual Rigid Plastic Packaging Demand by Product, 2019 - 2026
- Figure 6-2. Rigid Plastic Food Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Tubs & Cups
- Table | Plastic Food Tub & Cup Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Tub & Cup Demand by Application, 2019 - 2026
- Bottles & Jugs
- Table | Plastic Food Bottle & Jug Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Bottle & Jug Demand by Application, 2019 - 2026
- Trays
- Table | Plastic Food Tray Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Tray Demand by Application, 2019 - 2026
- Clamshells
- Table | Plastic Food Clamshell Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Clamshell Demand by Application, 2019 - 2026
- Two-Piece Containers
- Table | Plastic Food Two-Piece Container Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Two-Piece Container Demand by Application, 2019 - 2026
- Jars
- Table | Plastic Food Jar Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Food Jar Demand by Application, 2019 - 2026
- Other Rigid Plastic Packaging
- Table | Other Rigid Plastic Food Packaging Demand by Application, 2012, 2017, 2022, 2027, &2032
- Table | Annual Other Rigid Plastic Food Packaging Demand by Application, 2019 - 2026
- Scope & Product Description
- Meat, Poultry, &Seafood
- Scope & Product Description
- Table | Industry Codes Related to Meat, Poultry, &Seafood
- Figure 7-1. Meat, Poultry, &Seafood Plastic Packaging: Product Examples
- Growth Drivers & Restraints
- Figure 7-2. Meat, Poultry, &Seafood: Plastic Packaging Demand by Packaging Format, 2012, 2017, 2022,
- Packaging Products
- Table | Meat, Poultry, &Seafood: Plastic Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Meat, Poultry, &Seafood: Annual Plastic Packaging Demand by Product, 2019 - 2026
- Figure 7-3. Meat, Poultry, &Seafood: Comparative Value Growth for Plastic Packaging Products, 2022 -
- Demand by Food Format
- Table | Meat, Poultry, &Seafood: Plastic Packaging Demand by Food Format, 2012, 2017, 2022, 2027, &2032
- Table | Meat, Poultry, &Seafood: Annual Plastic Packaging Demand by Food Format, 2019 - 2026
- New Product Development
- Key Suppliers
- Scope & Product Description
- Fresh Produce
- Scope & Product Description
- Figure 8-1. Fresh Produce Plastic Packaging: Product Examples
- Growth Drivers & Restraints
- Figure 8-2. Fresh Produce: Plastic Packaging Demand by Packaging Format, 2012, 2017, 2022, &2027
- Packaging Products
- Table | Fresh Produce: Plastic Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Fresh Produce: Annual Plastic Packaging Demand by Product, 2019 - 2026
- Figure 8-3. Fresh Produce: Comparative Growth for Plastic Packaging Products, 2022 - 2027
- Demand by Food Format
- New Product Development
- Key Suppliers
- Scope & Product Description
- Dairy Products
- Scope & Product Description
- Table | Industry Codes Related to Dairy Products
- Figure 9-1. Dairy Product Plastic Packaging: Product Examples
- Growth Drivers & Restraints
- Figure 9-2. Dairy Products: Plastic Packaging Demand by Packaging Format, 2012, 2017, 2022, &2027
- Packaging Products
- Table | Dairy Products: Plastic Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Dairy Products: Annual Plastic Packaging Demand by Product, 2019 - 2026
- Figure 9-3. Dairy Products: Comparative Growth for Plastic Packaging Products, 2022 - 2027
- Demand by Food Format
- Table | Dairy Products: Plastic Packaging Demand by Food Format, 2012, 2017, 2022, 2027, &2032
- Table | Dairy Products: Annual Plastic Packaging Demand by Food Format, 2019 - 2026
- New Product Development
- Key Suppliers
- Scope & Product Description
- Sauces & Condiments
- Scope & Product Description
- Table | Industry Codes Related to Sauces & Condiments
- Figure 10-1. Sauce & Condiment Plastic Packaging: Product Examples
- Growth Drivers & Restraints
- Figure 10-2. Sauces & Condiments: Plastic Packaging Demand by Packaging Format, 2012, 2017, 2022, &2
- Packaging Products
- Table | Sauces & Condiments: Plastic Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Sauces & Condiments: Annual Plastic Packaging Demand by Product, 2019 - 2026
- Figure 10-3. Sauces & Condiments: Comparative Growth for Plastic Packaging Products, 2022 - 2027
- Demand by Food Format
- Table | Sauces & Condiments: Plastic Packaging Demand by Food Format, 2012, 2017, 2022, 2027, &2032
- Table | Sauces & Condiments: Annual Plastic Packaging Demand by Food Format, 2019 - 2026
- New Product Development
- Key Suppliers
- Scope & Product Description
- Prepared Foods
- Scope & Product Description
- Table | Industry Codes Related to Prepared Foods
- Figure 11-1. Prepared Foods Plastic Packaging: Product Examples
- Growth Drivers & Restraints
- Figure 11-2. Prepared Foods: Plastic Packaging Demand by Packaging Format, 2012, 2017, 2022, &2027
- Packaging Products
- Table | Prepared Foods: Plastic Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Prepared Foods: Annual Plastic Packaging Demand by Product, 2019 - 2026
- Figure 11-3. Prepared Foods: Comparative Growth for Plastic Packaging Products, 2022 - 2027
- Demand by Food Format
- Table | Prepared Foods: Plastic Packaging Demand by Food Format, 2012, 2017, 2022, 2027, &2032
- Table | Prepared Foods: Annual Plastic Packaging Demand by Food Format, 2019 - 2026
- New Product Development
- Key Suppliers
- Scope & Product Description
- Baked Goods
- Scope & Product Description
- Table | Industry Codes Related to Baked Goods
- Figure 12-1. Baked Goods Plastic Packaging: Product Examples
- Growth Drivers & Restraints
- Figure 12-2. Baked Goods: Plastic Packaging Demand by Packaging Format, 2012, 2017, 2022, &2027
- Packaging Products
- Table | Baked Goods: Plastic Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Baked Goods: Annual Plastic Packaging Demand by Product, 2019 - 2026
- Figure 12-3. Baked Goods: Comparative Growth for Plastic Packaging Products, 2022 - 2027
- Demand by Food Format
- Table | Baked Goods: Plastic Packaging Demand by Food Format, 2012, 2017, 2022, 2027, &2032
- Table | Baked Goods: Annual Plastic Packaging Demand by Food Format, 2019 - 2026
- New Product Development
- Key Suppliers
- Scope & Product Description
- Savory Snack Foods
- Scope & Product Description
- Table | Industry Codes Related to Savory Snack Foods
- Figure 13-1. Savory Snack Foods Plastic Packaging: Product Examples
- Growth Drivers & Restraints
- Figure 13-2. Savory Snack Foods: Plastic Packaging Demand by Packaging Format, 2012, 2017, 2022, &20
- Packaging Products
- Table | Savory Snack Foods: Plastic Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Savory Snack Foods: Annual Plastic Packaging Demand by Product, 2019 - 2026
- Figure 13-3. Savory Snack Foods: Comparative Growth for Plastic Packaging Products, 2022 - 2027
- Demand by Food Format
- Table | Savory Snack Foods: Plastic Packaging Demand by Food Format, 2012, 2017, 2022, 2027, &2032
- Table | Savory Snack Foods: Annual Plastic Packaging Demand by Food Format, 2019 - 2026
- New Product Development
- Key Suppliers
- Scope & Product Description
- Candy & Confections
- Scope & Product Description
- Table | Industry Codes Related to Candy & Confections
- Figure 14-1. Candy & Confections Plastic Packaging: Product Examples
- Growth Drivers & Restraints
- Figure 14-2. Candy & Confections: Plastic Packaging Demand by Packaging Format, 2012, 2017, 2022, &2
- Packaging Products
- Table | Candy & Confections: Plastic Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Candy & Confections: Annual Plastic Packaging Demand by Product, 2019 - 2026
- Figure 14-3. Candy & Confections: Comparative Growth for Plastic Packaging Products, 2022 - 2027
- Demand by Food Format
- Table | Candy & Confections: Plastic Packaging Demand by Food Format, 2012, 2017, 2022, 2027, &2032
- Table | Candy & Confections: Plastic Packaging Demand by Food Format, 2019 - 2026
- New Product Development
- Key Suppliers
- Scope & Product Description
- Processed Fruits & Vegetables
- Scope & Product Description
- Table | Industry Codes Related to Processed Fruits & Vegetables
- Figure 15-1. Processed Fruits & Vegetables Plastic Packaging: Product Examples
- Growth Drivers & Restraints
- Figure 15-2. Processed Fruits & Vegetables: Plastic Packaging Demand by Packaging Format, 2012, 2017
- Packaging Products
- Table | Processed Fruits & Vegetables: Plastic Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Processed Fruits & Vegetables: Annual Plastic Packaging Demand by Product, 2019 - 2026
- Figure 15-3. Processed Fruits & Vegetables: Comparative Growth for Plastic Packaging Products, 2022
- Demand by Food Format
- Table | Processed Fruits & Vegetables: Plastic Packaging Demand by Food Format, 2012, 2017, 2022, 2027, &203
- Table | Processed Fruits & Vegetables: Annual Plastic Packaging Demand by Food Format, 2019 - 2026
- New Product Development
- Key Suppliers
- Scope & Product Description
- Other Foods
- Scope & Product Description
- Table | Industry Codes Related to Other Foods
- Figure 16-1. Other Foods Plastic Packaging: Product Examples
- Packaging Products
- Table | Other Foods: Plastic Packaging Demand by Product, 2012, 2017, 2022, 2027, &2032
- Table | Other Foods: Annual Plastic Packaging Demand by Product, 2019 - 2026
- Figure 16-2. Other Foods: Comparative Growth for Plastic Packaging Products, 2012, 2017, 2022, &2027
- Demand by Food Format
- Table | Other Foods: Plastic Packaging Demand by Food Format, 2012, 2017, 2022, 2027, &2032
- Table | Other Foods: Annual Plastic Packaging Demand by Food Format, 2019 - 2026
- New Product Development
- Key Suppliers
- Scope & Product Description
- Key Suppliers & Market Share
- Industry Composition
- Market Share
- Figure 17-1. US Plastic Food Packaging Market Share by Company, 2022
- Figure 17-2. US Plastic Food Packaging Market: Leading Supplier, 2022
- Figure 17-3. US Plastic Food Packaging Market: Second Leading Supplier, 2022
- Figure 17-4. US Plastic Food Packaging Market: Third Leading Supplier, 2022
- Figure 17-5. US Plastic Food Packaging Market: Fourth Leading Supplier, 2022
- Figure 17-6. US Plastic Food Packaging Market: Fifth Leading Supplier, 2022
- List of Industry Participants
- Table | Selected Industry Participants
- Appendix
- Scope
- Table | Industry Codes Related to Food Packaging
- Table | Relevant HS Codes
- Definitions
- Freedonia Methodology
- Study-Specific Methodology
- Sources
- Related Studies & Reports
- Macroeconomic Assumptions
- Economic Environment
- Table | Macroeconomic Indicators, 2012, 2017, 2022, &2027
- Demographic Trends
- Table | Population & Households, 2012, 2017, 2022, &2027
- Consumer Spending
- Table | Personal Consumption Expenditures & Retail Sales, 2012, 2017, 2022, &2027
- Retail Sales
- Table | Nondurable Goods Retail Sales, 2012, 2017, 2022, &2027
- Economic Environment
- Scope
New plastic food packaging innovations continue to emerge, most with a focus on improving performance, protective, barrier, or sustainability properties.
The most important factor in plastic food packaging demand is the outlook for food production, both in terms of the volume produced and the popularity of food types.
Food shipments, including fresh produce, are forecast to rise 2.6% per year to $746 billion in 2027, with real growth of 2.4% annually to $584 billion, adjusted for inflation.
The top companies overall for plastic food packaging in the US include– Amcor, Berry Global, SEE, Pactiv Evergreen, and Sonoco Products.