US Retail Bags
This Freedonia industry study analyzes the $4.5 billion US retail bag industry. It presents historical demand data (2012, 2017, and 2019 through 2022) and forecasts (2023 through 2027 and 2032) by type (single-use and reusable), material (plastic, paper, and natural fabric) and market (grocery stores, foodservice, and other retail stores).
Free Sample Report
Request a free sample of this report and our team will email it to you.
Report Overview
The market for single-use and reusable bags has seen a lot of shifts over the past few years. Need a study that accurately assesses bag usage?
-
Gain insights into the popularity of single-use plastic bags and if reusable bags or bags made from other materials are gaining market share.
 forecasts (2023 through 2027 and 2032) by type (single-use and reusable), material (plastic, paper, and natural fabric) and market (grocery stores, foodservice, and other retail stores). The study also evaluates company market share and competitive analysis on key industry competitors including Novolex, Inteplast Group, Advance Polybag, International Paper, and Sigma Plastics Group.
Featuring 100 tables and 53 figures – available in Excel and Powerpoint! Learn More
Read the blog on Evolving Bag Policies
Demand for retail bags in the US is forecast to grow 2.5% per year to $4.5 billion in 2027, with regulations targeted at single-use products and growing environmental concerns among consumers leading to significant changes in industry composition and outlook:
-
Growth in market value will come almost entirely from a shift in the product mix toward higher-priced bags that meet regulatory requirements.
-
The number of bags used will stagnate, with strong growth in the foodservice market offsetting unit losses in grocery and other retail stores.
-
Strong growth in paper and heavier-gauge reusable plastic bags will somewhat offset losses in the single-use HDPE t-shirt bag segment.
New Retail Bag Regulations May be Slowing
In the past decade, 12 states and hundreds of municipalities in the US have passed retail bag regulations. These typically ban the distribution of single-use plastic bags, and they can also include fees for paper bags. Such regulations have impacted the retail bag market tremendously; consumers and producers alike face increasing uncertainty about the future of bag bans in the US, as well as which bags will be allowed in the future.
Many large markets (e.g., California, New York, Baltimore) have already enacted bans, while a steady contingent have passed bag ban preemption laws. This leaves a dwindling number of jurisdictions where new bag bans can be passed to further shakeup the retail bag market. However, there is potential for regulations to be revised or enhanced following controversy surrounding the efficacy of thickness-based bans; 2.25 mil bags, in particular, face growing scrutiny as a legitimate solution to curbing plastic waste.
Foodservice Trends will Act as a Boon to Retail Bag Use
Historically, the foodservice market has been a relatively minor component of bag demand compared to grocery and other retail stores. However, a strong increase in the popularity of takeout and delivery orders will continue to drive the use of retail bags at many foodservice establishments.
These trends are particularly evident in full-service and fast casual restaurants, which increasingly see takeout and delivery as an important revenue stream. Such establishments often use larger, higher-value bags compared to fast food restaurants, thereby supporting demand growth in both units and value.
Strong Demand for Paper Continues, Along with Growing Interest in High Gauge Plastic
Bans on thin, single-use plastic bags have caused a significant increase in demand for paper retail bags, especially where regulations have not included paper bag fees. Paper is now preferred in foodservice applications, as well as in key retail segments like apparel stores.
Additionally, many bans only pertain to single-use plastic bags that are thinner than 2.25 mil. This fact has generated significant demand for thicker bags in recent years, but it has also stirred controversy regarding the efficacy of bans from environmental and consumer behavior perspectives.
Historical Trends
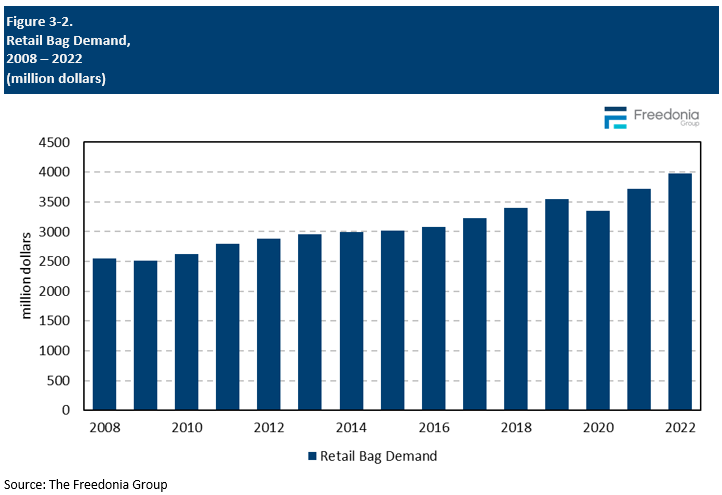
Demand for retail bags depends primarily on trends in retail sales, particularly at establishments that sell smaller items. The outlook for retail sales, in turn, can be influenced by a variety of factors, both internal and external, that affect consumer behavior, economic conditions, and overall market dynamics, including:
-
the overall state of the economy, including factors like GDP growth, employment rates, inflation, and consumer confidence (during periods of economic expansion and low unemployment, consumers tend to have more disposable income and are more likely to spend on retail goods).
-
demographic factors such as population growth, age distribution, and changes in household composition can influence consumer preferences and spending patterns
-
consumer sentiment and confidence in the economy (high levels of confidence typically lead to increased consumer spending, while low confidence may result in reduced discretionary spending).
-
household income levels, which directly affect consumers' purchasing power (higher disposable income often leads to increased spending on retail products).
-
unemployment rates, which indicate the strength of the job market and impact consumer spending
Outside of overall retail sales levels, other key factors impacting retail bag demand include:
-
the share of retail sales held by e-commerce retailers, as merchandise purchased online does not require a retail bag
-
the share of retail sales held by club stores or discount stores that do not provide bags for customers or use alternatives for carrying merchandise such as boxes
-
regulations and changes in government policies, including bans, taxes, or other restrictions on the use of single-use bags
- consumer use of reusable bags, which limit unit demand for retail bags
Production Trends
Production of retail bags in the US is expected to increase 3.0% per year to $3.6 billion in 2027.
Most of the growth in production will come from paper bags, which have seen increased demand across all markets due to their perceived sustainability and the impact of plastic ban bans. As paper bag manufacturers seek to increase production capacity, more plastic bag manufacturers will continue to transition from low gauge HDPE bags to high gauge LDPE bags that better comply with single-use bag bans and restrictions.
The changing regulatory environment is having a significant impact on US producers:
-
To replace conventional, thin, HDPE t-shirt bags that have come under increasing regulatory scrutiny, polyethylene producers are quickly shifting production to bags that are 2.25 mil or thicker.
-
Paper producers have been operating near capacity, as they are less able to quickly ramp up production to meet new demand due to long lead times for equipment.
Regulatory uncertainty is making it difficult for both plastic and paper bag producers to plan future capacity needs. Regulations continue to evolve, varying by state and locality. Most producers feel they can accomplish what is needed but are looking for national standards to be put in place so they have a clearer understanding of future market movement before making any large investments.
Pricing Patterns
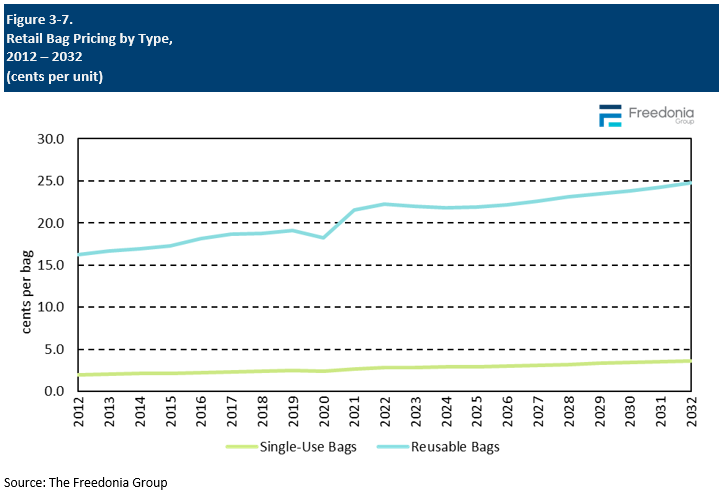
The retail bag industry is competitive, and product pricing is a significant factor in customer purchasing decisions, especially among large foodservice chains and grocery stores which may use thousands of bags per day. Factors influencing average prices for retail bags include:
-
raw material and labor costs
-
shipping and transportation costs
-
supply and demand balances
-
customization, design, and printing costs
-
preference in bag size and the use of value added features such as coatings and handles
-
the prevalence of bag fees and taxes
Raw material price fluctuations tend to have the greatest effect on pricing although product mix can also be important:
-
The price of plastic bags is largely determined by the price of polyethylene resin, which, in turn, is affected by crude oil and natural gas prices.
- Paper bags are linked to the price of unbleached and bleached kraft paper.
Retail Sales Trends
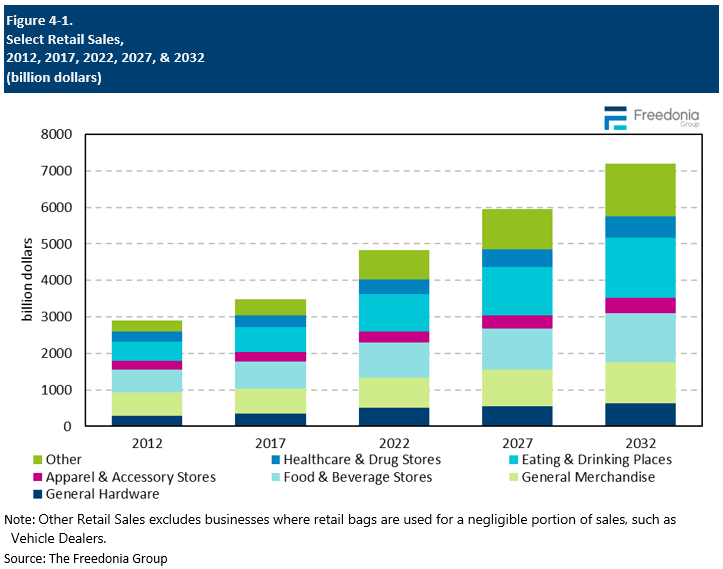
Demand for retail bags is driven both by the level of retail sales and growth trends in the different types of retail establishments.
Through 2027, retail sales are projected to increase at a more measured pace of 3.2% as inflation returns to historically normal levels. The strong growth of e-commerce relative to traditional retail stores will continue to be a major trend impacting retail bag demand, with the largest impact being felt in non-grocery retail stores.
Sales of nondurable goods, the primary uses of retail bags, will decelerate. Key trends will vary across the main markets.
-
Grocery stores, the largest market for retail bags, are expected to return to historically normal annual sales growth patterns following the strong pandemic-induced demand spike. Additionally, the growth of discount food stores and club stores will hinder retail bag demand as these establishments are less likely to offer free bags at checkout.
-
The quickest advances will be seen in eating and drinking places, as the demand for dining away from home continues to grow.
Other retail stores will provide a mixed bag of trends, with sales varying across the different segments.
-
Retail sales at healthcare and drug stores, a major market for single-use bags, will grow in correlation with the pharmaceutical industry’s outlook combined with an aging population.
-
Apparel and accessory stores will return to more moderate growth rates following volatility 2020 and 2021.
-
Some niche retail stores such as beauty stores will post strong growth.
- General hardware stores will post the weakest growth among the major retail sectors amid competition from large home improvement chains and online retailers.
Read the blog on Evolving Bag Policies
Demand for retail bags in the US is forecast to grow 2.5% per year to $4.5 billion in 2027, with regulations targeted at single-use products and growing environmental concerns among consumers leading to significant changes in industry composition and outlook:
-
Growth in market value will come almost entirely from a shift in the product mix toward higher-priced bags that meet regulatory requirements.
-
The number of bags used will stagnate, with strong growth in the foodservice market offsetting unit losses in grocery and other retail stores.
-
Strong growth in paper and heavier-gauge reusable plastic bags will somewhat offset losses in the single-use HDPE t-shirt bag segment.
New Retail Bag Regulations May be Slowing
In the past decade, 12 states and hundreds of municipalities in the US have passed retail bag regulations. These typically ban the distribution of single-use plastic bags, and they can also include fees for paper bags. Such regulations have impacted the retail bag market tremendously; consumers and producers alike face increasing uncertainty about the future of bag bans in the US, as well as which bags will be allowed in the future.
Many large markets (e.g., California, New York, Baltimore) have already enacted bans, while a steady contingent have passed bag ban preemption laws. This leaves a dwindling number of jurisdictions where new bag bans can be passed to further shakeup the retail bag market. However, there is potential for regulations to be revised or enhanced following controversy surrounding the efficacy of thickness-based bans; 2.25 mil bags, in particular, face growing scrutiny as a legitimate solution to curbing plastic waste.
Foodservice Trends will Act as a Boon to Retail Bag Use
Historically, the foodservice market has been a relatively minor component of bag demand compared to grocery and other retail stores. However, a strong increase in the popularity of takeout and delivery orders will continue to drive the use of retail bags at many foodservice establishments.
These trends are particularly evident in full-service and fast casual restaurants, which increasingly see takeout and delivery as an important revenue stream. Such establishments often use larger, higher-value bags compared to fast food restaurants, thereby supporting demand growth in both units and value.
Strong Demand for Paper Continues, Along with Growing Interest in High Gauge Plastic
Bans on thin, single-use plastic bags have caused a significant increase in demand for paper retail bags, especially where regulations have not included paper bag fees. Paper is now preferred in foodservice applications, as well as in key retail segments like apparel stores.
Additionally, many bans only pertain to single-use plastic bags that are thinner than 2.25 mil. This fact has generated significant demand for thicker bags in recent years, but it has also stirred controversy regarding the efficacy of bans from environmental and consumer behavior perspectives.
Historical Trends
Demand for retail bags depends primarily on trends in retail sales, particularly at establishments that sell smaller items. The outlook for retail sales, in turn, can be influenced by a variety of factors, both internal and external, that affect consumer behavior, economic conditions, and overall market dynamics, including:
-
the overall state of the economy, including factors like GDP growth, employment rates, inflation, and consumer confidence (during periods of economic expansion and low unemployment, consumers tend to have more disposable income and are more likely to spend on retail goods).
-
demographic factors such as population growth, age distribution, and changes in household composition can influence consumer preferences and spending patterns
-
consumer sentiment and confidence in the economy (high levels of confidence typically lead to increased consumer spending, while low confidence may result in reduced discretionary spending).
-
household income levels, which directly affect consumers' purchasing power (higher disposable income often leads to increased spending on retail products).
-
unemployment rates, which indicate the strength of the job market and impact consumer spending
Outside of overall retail sales levels, other key factors impacting retail bag demand include:
-
the share of retail sales held by e-commerce retailers, as merchandise purchased online does not require a retail bag
-
the share of retail sales held by club stores or discount stores that do not provide bags for customers or use alternatives for carrying merchandise such as boxes
-
regulations and changes in government policies, including bans, taxes, or other restrictions on the use of single-use bags
- consumer use of reusable bags, which limit unit demand for retail bags

Production Trends
Production of retail bags in the US is expected to increase 3.0% per year to $3.6 billion in 2027.
Most of the growth in production will come from paper bags, which have seen increased demand across all markets due to their perceived sustainability and the impact of plastic ban bans. As paper bag manufacturers seek to increase production capacity, more plastic bag manufacturers will continue to transition from low gauge HDPE bags to high gauge LDPE bags that better comply with single-use bag bans and restrictions.
The changing regulatory environment is having a significant impact on US producers:
-
To replace conventional, thin, HDPE t-shirt bags that have come under increasing regulatory scrutiny, polyethylene producers are quickly shifting production to bags that are 2.25 mil or thicker.
-
Paper producers have been operating near capacity, as they are less able to quickly ramp up production to meet new demand due to long lead times for equipment.
Regulatory uncertainty is making it difficult for both plastic and paper bag producers to plan future capacity needs. Regulations continue to evolve, varying by state and locality. Most producers feel they can accomplish what is needed but are looking for national standards to be put in place so they have a clearer understanding of future market movement before making any large investments.
Pricing Patterns
The retail bag industry is competitive, and product pricing is a significant factor in customer purchasing decisions, especially among large foodservice chains and grocery stores which may use thousands of bags per day. Factors influencing average prices for retail bags include:
-
raw material and labor costs
-
shipping and transportation costs
-
supply and demand balances
-
customization, design, and printing costs
-
preference in bag size and the use of value added features such as coatings and handles
-
the prevalence of bag fees and taxes
Raw material price fluctuations tend to have the greatest effect on pricing although product mix can also be important:
-
The price of plastic bags is largely determined by the price of polyethylene resin, which, in turn, is affected by crude oil and natural gas prices.
- Paper bags are linked to the price of unbleached and bleached kraft paper.

Retail Sales Trends
Demand for retail bags is driven both by the level of retail sales and growth trends in the different types of retail establishments.
Through 2027, retail sales are projected to increase at a more measured pace of 3.2% as inflation returns to historically normal levels. The strong growth of e-commerce relative to traditional retail stores will continue to be a major trend impacting retail bag demand, with the largest impact being felt in non-grocery retail stores.
Sales of nondurable goods, the primary uses of retail bags, will decelerate. Key trends will vary across the main markets.
-
Grocery stores, the largest market for retail bags, are expected to return to historically normal annual sales growth patterns following the strong pandemic-induced demand spike. Additionally, the growth of discount food stores and club stores will hinder retail bag demand as these establishments are less likely to offer free bags at checkout.
-
The quickest advances will be seen in eating and drinking places, as the demand for dining away from home continues to grow.
Other retail stores will provide a mixed bag of trends, with sales varying across the different segments.
-
Retail sales at healthcare and drug stores, a major market for single-use bags, will grow in correlation with the pharmaceutical industry’s outlook combined with an aging population.
-
Apparel and accessory stores will return to more moderate growth rates following volatility 2020 and 2021.
-
Some niche retail stores such as beauty stores will post strong growth.
- General hardware stores will post the weakest growth among the major retail sectors amid competition from large home improvement chains and online retailers.

- Executive Summary
- Figure 1-1. Retail Bags Market
- Short-Term Analysis
- Economic Forecast
- Table | Macroeconomic Indicators, 2020 - 2024
- Figure 2-1. Real GDP by Economic Sector, 2020 - 2023
- Short-Term Retail Sales Outlook
- Table | Retail Sales, 2020 - 2024
- Short-Term Retail Bag Industry Trends
- Table | Annual Retail Bag Demand by Material, 2020 - 2024
- Table | Annual Retail Bag Demand by Market, 2020 - 2024
- Figure 2-2. Annual Retail Bag Demand, 2020 - 2024
- Economic Forecast
- Overview
- Study Scope
- Figure 3-1. Retail Bags: Product Examples
- Historical Trends
- Table | Retail Bag Demand, 2012 - 2022
- Figure 3-2. Retail Bag Demand, 2008 - 2022
- Supply & Demand
- Market Value & Unit Growth Trends
- Table | Retail Bag Demand, 2012, 2017, 2022, 2027, &2032
- Table | Annual Retail Bag Demand, 2019 - 2026
- Figure 3-3. Retail Bag Value Demand Growth, 2013 - 2022
- Foreign Trade
- Table | Retail Bag Supply & Demand, 2012, 2017, 2022, 2027, &2032
- Table | Annual Retail Bag Supply & Demand, 2019 - 2026
- Figure 3-4. Retail Bag Imports by Source & Material, 2022
- Figure 3-5. Retail Bag Exports by Destination & Material, 2022
- Production Trends
- Table | Retail Bag Production by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Retail Bag Production by Material, 2019 - 2026
- Market Value & Unit Growth Trends
- Product Trends & Outlook
- Demand by Type
- Table | Retail Bag Demand by Type: Single-Use vs. Reusable, 2012, 2017, 2022, 2027, &2032
- Table | Annual Retail Bag Demand by Type: Single-Use vs. Reusable, 2019 - 2026
- Figure 3-6. Retail Bag Demand by Type: Single-Use vs. Reusable, 2012, 2017, 2022, 2027, &2032
- Single-Use Bags
- Table | Single-Use Retail Bag Demand by Material & Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Single-Use Retail Bag Demand by Material & Market, 2019 - 2026
- Reusable Bags
- Table | Reusable Retail Bag Demand by Material & Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Reusable Retail Bag Demand by Material & Market, 2019 - 2026
- Demand by Type
- Materials Trends (Plastic, Paper, Natural Fabric)
- Material Choice Considerations
- Demand by Material
- Table | Retail Bag Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Retail Bag Demand by Material, 2019 - 2026
- Pricing Patterns
- Table | Retail Bag Prices by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Retail Bag Prices by Material, 2019 - 2026
- Figure 3-7. Retail Bag Pricing by Type, 2012 - 2032
- Study Scope
- Factors Impacting Retail Bag Demand
- Retail Sales Trends
- Figure 4-1. Select Retail Sales, 2012, 2017, 2022, 2027, &2032
- The Impact of E-Commerce
- Figure 4-2. E-Commerce Sales & Share of Relevant Retail Sales, 2012, 2017, 2022, 2027, &2032
- Club Stores & Discount Stores
- Foodservice Industry Trends
- Figure 4-3. Off-Premises Share of Restaurant Revenues by Restaurant Type (Limited & Full-Service), 2
- The Litter Problem
- Regulations & Product Sales Restrictions Impact
- Summary & Future Direction
- Bans
- Taxes & Fees
- Preemptions
- State Trends
- Table | State Bag Regulations by Year Implemented & Type
- Figure 4-4. Retail Bag Regulations by State, 2023
- Local Trends
- Figure 4-5. Municipalities Enacting Bans by State, 2023
- Sustainability Initiatives
- Strategies for Achieving Sustainability
- Recycling & Recycled Content
- Composting/Biodegradability
- Bag Reusability
- Reuse of Bags for Non-Shopping Purposes
- Health & Hygiene Considerations for Reusable Bags
- Consumer Attitudes
- Consumer Attitudes About Recycling & Minimizing Waste
- Table | Consumer Attitudes About Recycling; By Gender, Age Group, Urban vs. Rural Setting, &Annual Household
- Consumer Attitudes About Recyclable & Compostable Packaging
- Table | Consumer Attitudes About Recyclable & Compostable Content in Packaging; By Gender, Age Group, Urban
- Attitudes About the Eco-Friendliness of Recyclable vs. Biodegradable Materials
- Table | Consumer Attitudes About Eco-Friendliness With Regard to Recyclable Plastics & Biodegradable Materia
- Curbside Recycling Services: Consumer Access
- Table | Access To Curbside Recycling at Home for Paper v. Plastic Film & Bags, by Gender, Age Group, Urban v
- Drop-Off Recycling Services: Consumer Usage
- Table | Usage of Drop-Off Recycling Services (at a Store, Community Bin, Waste Management Facility, etc.) in
- Availability of Retail Shopping Bags & Boxes
- Table | "In My Home Area, Grocery/Convenience Stores Offer Which of the Following Items to Carry Goods Out O
- Table | Consumers Who Report Being Able to Get Shopping Bags For Free, by Gender, Age Group, Area, &Annual H
- Usage of Various Types of Bag & Bag-Alternatives: Frequency
- Table | "When Shopping, I Carry My Goods Out of the Store In…" by Product Type, 2022
- Usage of Various Types of Bag & Bag-Alternatives: Demographics
- Table | "When Shopping, I Carry My Goods Out of the Store In…" by Gender, Age Group, Area, &Annual Household
- Habits for Bags After Use: by Bag Type
- Table | "When I am Done Transporting My Items In Single-Use Plastic or Paper Bags, I Do This With My Bags" b
- Habits for Plastic Bags After Use
- Table | "When I am Done Transporting My Items In Single-Use Plastic Bags, I Do This With My Bags" by Gender,
- Table | "When I am Done Transporting My Items In Single-Use Plastic Bags, I Do This With My Bags" by Age Gro
- Table | "When I am Done Transporting My Items In Single-Use Plastic Bags, I Do This With My Bags" by Urban v
- Table | "When I am Done Transporting My Items In Single-Use Plastic Bags, I Do This With My Bags" by Househo
- Habits for Paper Bags After Use
- Table | "When I am Done Transporting My Items In Paper Bags, I Do This With My Bags" by Gender, 2022
- Table | "When I am Done Transporting My Items In Paper Bags, I Do This With My Bags" by Age Group, 2022
- Table | "When I am Done Transporting My Items In Paper Bags, I Do This With My Bags" by Urban vs. Rural Sett
- Table | "When I am Done Transporting My Items In Paper, I Do This With My Bags" by Household Income Bracket,
- Consumer Attitudes About Recycling & Minimizing Waste
- Retailer Trends in Bag Use
- Retail Sales Trends
- Markets
- Demand by Market
- Table | Retail Bag Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Retail Bag Demand by Market, 2019 - 2026
- Figure 5-1. Retail Bag Demand by Market, 2012, 2017, 2022, 2027, &2032
- Grocery Stores
- Table | Grocery Store Bag Demand by Type & Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Grocery Store Bag Demand by Type & Material, 2019 - 2026
- Figure 5-2. Grocery Store Retail Bags: Product Examples
- Foodservice
- Demand by Establishment Type
- Table | Foodservice Bag Demand by Establishment Type, Bag Type, &Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Foodservice Bag Demand by Establishment Type, Bag Type, &Material, 2019 - 2026
- Figure 5-3. Foodservice Retail Bags: Product Examples
- Limited Service Restaurants
- Table | Limited Service Restaurant Bag Demand by Type & Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Limited Service Restaurant Bag Demand by Type & Material, 2019 - 2026
- Figure 5-4. Limited Service Restaurant Bag Demand by Material, 2012, 2017, 2022, 2027, &2032
- Full-Service Restaurants
- Table | Full-Service Restaurant Bag Demand by Type & Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Full-Service Restaurant Bag Demand by Type & Material, 2019 - 2026
- Figure 5-5. Full-Service Restaurant Bag Demand by Material, 2012, 2017, 2022, 2027, &2032
- Non-commercial Foodservice
- Table | Non-Commercial Foodservice Bag Demand by Type & Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Non-Commercial Foodservice Bag Demand by Type & Material, 2019 - 2026
- Figure 5-6. Non-Commercial Foodservice Bag Demand by Material, 2012, 2017, 2022, 2027, &2032
- Demand by Establishment Type
- Other Retail Stores
- Demand by Establishment Type
- Table | Demand for Retail Bags in Other Markets by Establishment Type, Bag Type, &Material, 2012, 2017, 2022
- Table | Annual Demand for Retail Bags in Other Markets by Establishment Type, Bag Type, &Material, 2019 - 20
- Figure 5-7. Other Retail Bags: Product Examples
- General Merchandise Stores
- Table | General Merchandise Store Bag Demand by Type & Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual General Merchandise Store Bag Demand by Type & Material, 2019 - 2026
- Figure 5-8. General Merchandise Store Bag Demand by Material, 2012, 2017, 2022, 2027, &2032
- Healthcare Stores & Pharmacies
- Table | Healthcare Store/Pharmacy Bag Demand by Type & Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Healthcare Store/Pharmacy Bag Demand by Type & Material, 2019 - 2026
- Figure 5-9. Healthcare Store/Pharmacy Bag Demand by Material, 2012, 2017, 2022, 2027, &2032
- Apparel & Accessories Stores
- Table | Apparel & Accessory Store Bag Demand by Type & Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Apparel & Accessory Store Bag Demand by Type & Material, 2019 - 2026
- Figure 5-10. Apparel & Accessory Store Bag Demand by Material, 2012, 2017, 2022, 2027, &2032
- All Other Retail Stores
- Table | All Other Retail Store Bag Demand by Type & Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual All Other Retail Store Bag Demand by Type & Material, 2019 - 2026
- Figure 5-11. All Other Retail Store Bag Demand by Material, 2012, 2017, 2022, 2027, &2032
- Demand by Establishment Type
- Demand by Market
- Plastic Bags
- Scope & Product Description
- Figure 6-1. Plastic Bags: Product Examples
- Supply & Demand
- Demand Overview
- Table | Plastic Retail Bag Supply & Demand, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Retail Bag Supply & Demand, 2019 - 2026
- International Trade
- Figure 6-2. US Plastic Bag Imports by Source, 2022
- Figure 6-3. US Plastic Bag Exports by Destination, 2022
- Production
- Figure 6-4. Plastic Retail Bag Production, 2012, 2017, 2022, 2027, &2032
- Demand Overview
- Single-Use vs. Reusable
- Table | Plastic Retail Bag Demand by Type: Single-Use vs. Reusable, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Retail Bag Demand by Type: Single-Use vs. Reusable, 2019 - 2026
- Figure 6-5. Plastic Retail Bag Demand: Single-Use vs. Reusable, 2012, 2017, 2022, 2027, &2032
- Demand by Market
- Table | Plastic Retail Bag Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Retail Bag Demand by Market, 2019 - 2026
- Figure 6-6. Plastic Retail Bag Demand by Market, 2012, 2017, 2022, 2027, &2032
- Resin Trends
- Demand by Plastic Resin
- Table | Plastic Retail Bag Demand by Resin, 2012, 2017, 2022, 2027, &2032
- Table | Annual Plastic Retail Bag Demand by Resin, 2019 - 2026
- Polyethylene (HDPE, LDPE, LLDPE, Co-Extruded)
- Table | Polyethylene Retail Bag Demand by Resin, 2012, 2017, 2022, 2027, &2032
- Table | Annual Polyethylene Retail Bag Demand by Resin, 2019 - 2026
- Other Plastics (PP, rPET, Synthetic Fabrics, Bioplastics)
- Table | Other Plastic Retail Bag Demand by Resin, 2012, 2017, 2022, 2027, &2032
- Table | Annual Other Plastic Retail Bag Demand by Resin, 2019 - 2026
- Demand by Plastic Resin
- Polyethylene Bag Demand by Gauge
- Table | Polyethylene Retail Bag Demand by Gauge, 2012, 2017, 2022, 2027, &2032
- Table | Annual Polyethylene Retail Bag Demand by Gauge, 2019 - 2026
- Figure 6-7. Statewide Bans on Polyethylene Bags by Gauge, 2023
- Market Share & Key Suppliers
- Figure 6-8. Plastic Bag Market Share by Company, 2022
- Scope & Product Description
- Paper Bags
- Scope & Product Description
- Figure 7-1. Paper Bags: Product Examples
- Supply & Demand
- Demand Overview
- Table | Paper Retail Bag Supply & Demand, 2012, 2017, 2022, 2027, &2032
- Table | Annual Paper Retail Bag Supply & Demand, 2019 - 2026
- Production & Trade
- Figure 7-2. Paper Retail Bag Production, 2012, 2017, 2022, 2027, &2032
- Demand Overview
- Demand by Market
- Table | Paper Retail Bag Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Paper Retail Bag Demand by Market, 2019 - 2026
- Product Trends
- Table | Paper Bag Demand by Material, Coating, &Presence of Handles, 2012, 2017, 2022, 2027, &2032
- Table | Annual Paper Bag Demand by Material, Coating & Presence of Handles, 2019 - 2026
- Market Share
- Figure 7-3. Paper Bag Market Share by Company, 2022
- Scope & Product Description
- Reusable Bags
- Scope & Product Description
- Figure 8-1. Reusable Bags: Product Examples
- Supply & Demand
- Table | Reusable Retail Bag Supply & Demand, 2012, 2017, 2022, 2027, &2032
- Table | Annual Reusable Retail Bag Supply & Demand, 2019 - 2026
- Materials Trends
- Demand by Material
- Table | Reusable Retail Bag Demand by Material, 2012, 2017, 2022, 2027, &2032
- Table | Annual Reusable Retail Bag Demand by Material, 2019 - 2026
- Figure 8-2. Reusable Retail Bag Demand by Material, 2012, 2017, 2022, 2027, &2032
- Polyethylene
- Figure 8-3. Reusable Polyethylene Bag Demand by Resin, 2012, 2017, 2022, 2027, &2032
- Figure 8-4. Reusable Polyethylene Bag Examples
- Polypropylene (Woven & Nonwoven)
- Figure 8-5. Reusable Polypropylene Bag Demand, 2012, 2017, 2022, 2027, &2032
- Figure 8-6. Reusable Polypropylene Bag Examples
- Other Plastics (rPET, Nylon, Polyester)
- Figure 8-7. Other Plastic Reusable Bag Demand, 2012, 2027, 2022, 2027, &2032
- Figure 8-8. Other Reusable Plastic Retail Polyethylene Bag Examples
- Natural Fabrics (Cotton, Jute, Linen, &Hemp)
- Table | Reusable Natural Fabric Retail Bag Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Reusable Natural Fabric Retail Bag Demand by Market, 2019 - 2026
- Figure 8-9. Reusable Natural Fabric Retail Bag Examples
- Demand by Material
- Demand by Market
- Table | Reusable Retail Bag Demand by Market, 2012, 2017, 2022, 2027, &2032
- Table | Annual Reusable Retail Bag Demand by Market, 2019 - 2026
- Figure 8-10. Reusable Retail Bag Demand by Market, 2012, 2017, 2022, 2027, &2032
- Leading Suppliers
- Scope & Product Description
- Competitive Analysis
- Industry Composition
- Table | US Retail Bag Sales by Company, 2022
- Market Share
- Figure 9-1. US Retail Bag Market Share by Company, 2022
- Figure 9-2. US Retail Bag Market: Leading Supplier, 2022
- Figure 9-3. US Retail Bag Market: Second Leading Supplier, 2022
- Figure 9-4 US Retail Bag Market: Co-Third Leading Supplier, 2022
- Figure 9-5. US Retail Bag Market: Co-Third Leading Supplier, 2022
- Figure 9-6. US Retail Bag Market: Fifth Leading Supplier, 2022
- Mergers & Acquisitions
- Table | Selected Mergers & Acquisitions
- New Product Development
- Captive Recycling Operations
- Marketing & Distribution
- List of Industry Participants
- Table | Selected Retail Bag Industry Participants
- Industry Composition
- Appendix
- Report Details
- Table | Relevant Industry Codes
- Table | Relevant HS Codes
- Definitions
- Abbreviations
- Table | Abbreviations & Acronyms Used in Study
- Freedonia Methodology
- Study-Specific Methodology
- Data Changes from Previous Version
- Sources
- Associations & Agencies
- Related Studies & Reports
- Macroeconomic Assumptions
- Economic Environment
- Table | Macroeconomic Indicators, 2012, 2017, 2022, 2027, &2032
- Demographic Trends
- Table | Population & Households, 2012, 2017, 2022, 2027, &2032
- Consumer Spending
- Table | Personal Consumption Expenditures, 2012, 2017, 2022, 2027, &2032
- Retail Sales
- Table | Nondurable Goods Retail Sales, 2012, 2017, 2022, 2027, &2032
- Economic Environment
- Report Details
In the current business climate, a high premium is placed on sustainability, which is crucial to most companies striving for ways to maintain a positive public image. The impact of single-use bags on the environment has forced retailers, governments, and manufacturers alike to consider various sustainability options to reduce both costs and the use of non-renewable resources and to maintain a minimal impact on the environment.
Demand for single-use bags is forecast to grow 2.2% per year to $3.8 billion in 2027, with gains based almost solely on a shift in product mix toward more expensive paper bags with value added features such as handles.
A variety of materials can be used to make retail bags: plastics – such as polyethylene (PE), polypropylene (PP), recycled polyethylene terephthalate (rPET), nylon, polyester, and bioplastics, paper – primarily unbleached kraft but also bleached white and natural fabrics – including cotton, jute, linen, and hemp.
The five leading retail bag companies include Novolex, Inteplast Group, Advance Polybag, Sigma Plastics Group, and International Paper.