Children’s Food and Beverage Market: Trends and Opportunities, 3rd Edition
When it comes to purchasing food, taste is the number one priority for most consumers. For parents, their children’s willingness to eat a given food is a close second. Compared to all consumers, parents are more likely to prioritize food characteristics that provide a health halo such as high protein, healthy fats, clean label, and non-GMO.
Free Sample Report
Request a free sample of this report and our team will email it to you.
Report Overview
 Packaged Facts found that parents seek out packaged foods with a health halo for their children.
-
Plant-based
-
No artificial ingredients
-
Low sugar
-
High protein
When it comes to purchasing food, taste is the number one priority for most consumers. For parents, their children’s willingness to eat a given food is a close second. Compared to all consumers, parents are more likely to prioritize food characteristics that provide a health halo such as high protein, healthy fats, clean label, and non-GMO.
Read the Blog: 3 Noteworthy Trends in the Children’s Food and Beverage Market
Opportunities exist in offering products that have the taste that will get a child to accept the food and the health halo that will entice parents to buy it, given that parents tend to be more health-conscious and choosy about foods for their kids and themselves.
Products free from common allergens – such as nuts, dairy, eggs, and gluten/wheat – are also a high priority for parents, particularly those who have children with real or perceived allergies or intolerances. Some parents may also believe some allergens are generally unhealthy (especially gluten and soy) and seek out foods without these ingredients for their children.
Additionally, parents are concerned about allergy friendly foods even when their own children do not have food allergies, as their kids may have friends or peers with a food allergy that needs to be accommodated. Schools, sports teams, daycares, and other child-centric organizations sometimes restrict foods with certain allergens for all children to protect those with a food allergy. Thus, parents tend to have more reasons to avoid potential allergens (often for their kids, or for other children their kids come in contact with).
With a focus on “what’s next” and current consumer trends, Children’s Food and Beverage Market: Trends and Opportunities is packed with insights about parent trends, behavior, and motivations to help food producers, retailers, packaging companies, employers, and investors gauge consumer perspectives and find areas for growth in a competitive market.
Children’s Food and Beverage Market: Trends and Opportunities delivers actionable predictions and recommendations designed to guide producers, retailers, and investors in making business decisions by providing data and insights about parent behavior and what parents think about food.
Scope
Children’s Food and Beverage Market: Trends and Opportunities is the go-to source for a complete understanding of U.S. consumer trends regarding children’s food and beverage products. This report combines Packaged Facts’ extensive monitoring of the food and beverage market with proprietary surveys, and evaluates current trends and future directions for marketing and retailing, along with consumer patterns during the pandemic and inflation area and across the broader food and beverage market.
This Packaged Facts report analyses the market for children’s food and beverage products. Retail sales of food and beverages marketed for children are projected to grow at an average rate of 4.6% annually through 2028.
Parent demographics, perceptions, motivations, and behavior are examined as pertaining to food and diet choice and attitudes about health, since parents purchase the vast majority of food on behalf of their children. Food habits and preferences of children, as reported by their parents, are also examined. Effects of the COVID-19 pandemic on consumers are also analyzed in a broad sense as well as in the context of children’s food and beverages.
Retail sales of children’s food and beverage products are provided in billion dollars from 2018 to 2022, with expected sales estimated for 2023 and sales projected from 2024 to 2028.
Retail sales in this report are defined as sales of children’s food and beverage products from venues such as:
-
Grocery stores, supermarkets, and discount grocers (e.g., Kroger, Safeway, ALDI)
-
Mass merchandisers (e.g., Walmart, Target, Meijer) and warehouse clubs (e.g., Costco, Sam’s Club, BJ’s)
-
Convenience stores (e.g., Pilot/Flying J, Circle K, 7-Eleven) and dollar stores (e.g., Dollar General, Family Dollar)
-
Other retailers, such as co-ops, gift shops, and farmers markets
-
All online outlets, including online-based grocers (e.g., Amazon, Thrive Market, FreshDirect), third-party pack-and-deliver companies that use their own workforces to purchase groceries at various stores and deliver them to customers (e.g., Instacart), brands that sell their own food products direct-to-consumer via their websites, and online sales from websites or apps of retailers in the previous categories
The reasons for and implications of shifts in consumer perception and behavior are analyzed in the context of future market opportunities.
Additionally, Children’s Food and Beverage Market: Trends and Opportunities has dozens of tables highlighting numerical survey data on consumer demographics and psychographics as well as numerous marketing photographs. This report goes in-depth on COVID-19 and inflation trends that have affected the food and beverage market.
Report Methodology
The information contained in Children’s Food and Beverage Market: Trends and Opportunities was developed from primary and secondary research sources. Primary research includes interviews with food and beverage market experts; participation in and attendance at food industry events; and extensive internet canvassing.
Primary research also includes national online consumer polls of U.S. adult consumers (age 18+) conducted on an ongoing basis by Packaged Facts to analyze attitudes of consumers and their relevant food and beverage preferences.
Survey data from MRI-Simmons are used to analyze the demographics and psychographics of parents and age/number of children in the household.
Supplementing Packaged Facts’ exclusive surveys are analysis of the 2022 and 2023 Food & Health Surveys conducted by the International Food Information Council, which analyze consumer food purchase decisions, diet and lifestyle choices, snacking activity, and perception of health benefits in foods.
Frequency of Grocery Shopping in 2023: In-Person vs. Online
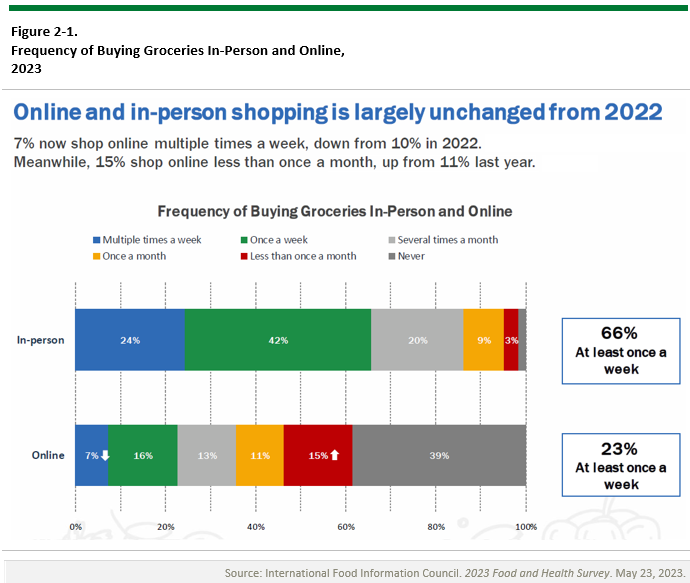
The International Food Information Council’s (IFIC) 2023 Food and Health Survey conducted in May 2023 indicated that online ordering frequency may be decreasing somewhat compared to 2022, though overall use of online shopping was largely unchanged. In the organization’s 2021 survey, 20% of consumers reported buying groceries online at least once per week; that number rose to 25% in 2022 and fell to 23% in 2023.
Online grocery shopping activity skyrocketed in 2020 as the pandemic prevented some people from getting out to shop. Concerns about COVID-19 were very high in 2020 because a vaccine was not yet available for the public. As concerns have waned, people are no longer shopping for groceries online because of the pandemic. Instead, online grocery shopping has become an established habit for some people, largely for convenience.
Consumers who have children are more likely to value online grocery shopping for its convenience since they are very busy and may not have much time to shop. Additionally, parents of young children may have to bring their kids on shopping trips and take them into a grocery store, which can be inconvenient. Online grocery shopping (either for delivery or curbside pickup) is much more convenient when parents have young children and reduces the amount of time spent on a shopping trip. It is also important to note that greater varieties of children’s food and beverage products are available for purchase online than in many local stores; this is particularly true of small startups that ship products directly to customers but lack traditional retail distribution.
Read the Blog: 3 Noteworthy Trends in the Children’s Food and Beverage Market
Opportunities exist in offering products that have the taste that will get a child to accept the food and the health halo that will entice parents to buy it, given that parents tend to be more health-conscious and choosy about foods for their kids and themselves.
Products free from common allergens – such as nuts, dairy, eggs, and gluten/wheat – are also a high priority for parents, particularly those who have children with real or perceived allergies or intolerances. Some parents may also believe some allergens are generally unhealthy (especially gluten and soy) and seek out foods without these ingredients for their children.
Additionally, parents are concerned about allergy friendly foods even when their own children do not have food allergies, as their kids may have friends or peers with a food allergy that needs to be accommodated. Schools, sports teams, daycares, and other child-centric organizations sometimes restrict foods with certain allergens for all children to protect those with a food allergy. Thus, parents tend to have more reasons to avoid potential allergens (often for their kids, or for other children their kids come in contact with).
With a focus on “what’s next” and current consumer trends, Children’s Food and Beverage Market: Trends and Opportunities is packed with insights about parent trends, behavior, and motivations to help food producers, retailers, packaging companies, employers, and investors gauge consumer perspectives and find areas for growth in a competitive market.
Children’s Food and Beverage Market: Trends and Opportunities delivers actionable predictions and recommendations designed to guide producers, retailers, and investors in making business decisions by providing data and insights about parent behavior and what parents think about food.
Scope
Children’s Food and Beverage Market: Trends and Opportunities is the go-to source for a complete understanding of U.S. consumer trends regarding children’s food and beverage products. This report combines Packaged Facts’ extensive monitoring of the food and beverage market with proprietary surveys, and evaluates current trends and future directions for marketing and retailing, along with consumer patterns during the pandemic and inflation area and across the broader food and beverage market.
This Packaged Facts report analyses the market for children’s food and beverage products. Retail sales of food and beverages marketed for children are projected to grow at an average rate of 4.6% annually through 2028.
Parent demographics, perceptions, motivations, and behavior are examined as pertaining to food and diet choice and attitudes about health, since parents purchase the vast majority of food on behalf of their children. Food habits and preferences of children, as reported by their parents, are also examined. Effects of the COVID-19 pandemic on consumers are also analyzed in a broad sense as well as in the context of children’s food and beverages.
Retail sales of children’s food and beverage products are provided in billion dollars from 2018 to 2022, with expected sales estimated for 2023 and sales projected from 2024 to 2028.
Retail sales in this report are defined as sales of children’s food and beverage products from venues such as:
-
Grocery stores, supermarkets, and discount grocers (e.g., Kroger, Safeway, ALDI)
-
Mass merchandisers (e.g., Walmart, Target, Meijer) and warehouse clubs (e.g., Costco, Sam’s Club, BJ’s)
-
Convenience stores (e.g., Pilot/Flying J, Circle K, 7-Eleven) and dollar stores (e.g., Dollar General, Family Dollar)
-
Other retailers, such as co-ops, gift shops, and farmers markets
-
All online outlets, including online-based grocers (e.g., Amazon, Thrive Market, FreshDirect), third-party pack-and-deliver companies that use their own workforces to purchase groceries at various stores and deliver them to customers (e.g., Instacart), brands that sell their own food products direct-to-consumer via their websites, and online sales from websites or apps of retailers in the previous categories
The reasons for and implications of shifts in consumer perception and behavior are analyzed in the context of future market opportunities.
Additionally, Children’s Food and Beverage Market: Trends and Opportunities has dozens of tables highlighting numerical survey data on consumer demographics and psychographics as well as numerous marketing photographs. This report goes in-depth on COVID-19 and inflation trends that have affected the food and beverage market.
Report Methodology
The information contained in Children’s Food and Beverage Market: Trends and Opportunities was developed from primary and secondary research sources. Primary research includes interviews with food and beverage market experts; participation in and attendance at food industry events; and extensive internet canvassing.
Primary research also includes national online consumer polls of U.S. adult consumers (age 18+) conducted on an ongoing basis by Packaged Facts to analyze attitudes of consumers and their relevant food and beverage preferences.
Survey data from MRI-Simmons are used to analyze the demographics and psychographics of parents and age/number of children in the household.
Supplementing Packaged Facts’ exclusive surveys are analysis of the 2022 and 2023 Food & Health Surveys conducted by the International Food Information Council, which analyze consumer food purchase decisions, diet and lifestyle choices, snacking activity, and perception of health benefits in foods.
Frequency of Grocery Shopping in 2023: In-Person vs. Online
The International Food Information Council’s (IFIC) 2023 Food and Health Survey conducted in May 2023 indicated that online ordering frequency may be decreasing somewhat compared to 2022, though overall use of online shopping was largely unchanged. In the organization’s 2021 survey, 20% of consumers reported buying groceries online at least once per week; that number rose to 25% in 2022 and fell to 23% in 2023.
Online grocery shopping activity skyrocketed in 2020 as the pandemic prevented some people from getting out to shop. Concerns about COVID-19 were very high in 2020 because a vaccine was not yet available for the public. As concerns have waned, people are no longer shopping for groceries online because of the pandemic. Instead, online grocery shopping has become an established habit for some people, largely for convenience.
Consumers who have children are more likely to value online grocery shopping for its convenience since they are very busy and may not have much time to shop. Additionally, parents of young children may have to bring their kids on shopping trips and take them into a grocery store, which can be inconvenient. Online grocery shopping (either for delivery or curbside pickup) is much more convenient when parents have young children and reduces the amount of time spent on a shopping trip. It is also important to note that greater varieties of children’s food and beverage products are available for purchase online than in many local stores; this is particularly true of small startups that ship products directly to customers but lack traditional retail distribution.

- Executive Summary
- Parent Priorities When Buying Food
- Parents Turning to Online Grocery Shopping for Convenience
- Key Demographics
- Scope
- Parent Priorities When Buying Food
- Recent Historical Trends from the Pandemic to the Inflation Era
- Highlights
- Boosted Online Grocery Shopping Activity
- Frequency of Grocery Shopping in 2023: In-Person vs. Online
- Use of Meal Kit Delivery Services
- Snacking and Healthy Eating Habits
- Trends from 2021-2022
- Table | Coronavirus Eating Habits: "Because of the coronavirus, I am eating more…", 2021 (percent of consume
- Changes to Snacking Habits in 2023
- Table | Current Snacking Activity Compared to Pre-Pandemic Levels, 2023 (percent of consumers)
- Trends from 2021-2022
- Concerns about COVID-19 Exposure Have Remained
- Most Still Consider the Pandemic a Health Threat Personally or to Family/Friends
- Table | Coronavirus Health Concerns: "I am concerned about…", 2020 - 2021 (percent of consumers)
- Table | Coronavirus Health Concerns: "I am concerned about…", 2022 - 2023 (percent of consumers)
- Concerns about COVID-19 Variants
- Concerns about Future Potential Pandemic Outbreaks
- Table | Future Potential Pandemic Outbreak Concerns, 2023 (percent of consumers)
- Vaccination Plans Reveal Many Consumers Are Taking COVID-19 and the Flu Seriously, Though Fewer May
- Table | Consumer Vaccination Plans, 2023 (percent of consumers)
- Parents Express More Pandemic Concerns and Are More Likely to Be Getting the Newest COVID-19 Booster
- Table | Coronavirus Health Concerns: "I am concerned about…" by Parenthood and Age of Children, 2023 (percen
- Most Still Consider the Pandemic a Health Threat Personally or to Family/Friends
- Negative Personal Effects of the Pandemic
- Mental and Physical Health Effects in 2022
- Reporting Negative Mental States in 2023
- Stress Levels and Impact on Food/Beverage Consumption
- Near Term Effects on Work Habits
- Changes to Work Patterns Continued in 2021 and 2022
- Working from Home in 2023
- Table | Ability to Work from Home and Frequency of Remote Work, 2023 (percent of consumers)
- Table | Working at a Co-Working Space or Working from Home, 2023 (percent of consumers)
- Table | Consumer Rating of Experiences Working at a Co-Working Space or Working from Home, 2023 (percent of
- Table | Consumer Opinions on Working at a Co-Working Space or Working from Home, 2023 (percent of employed c
- Rising Prices: From Supply Chain Crunches to Inflation
- Many Consumers Are Concerned about Inflation and Rising Food Prices
- Table | Consumer Concerns about Rising Food Prices, 2021 - 2023 (percent of consumers)
- The Vast Majority of Consumers Have Noticed the Rising Cost of Food, and Many Are Changing Their Pur
- Consumers Find Price More Important for Food Purchase Decisions in 2023
- Cutting Back on Household Expenses
- Table | Consumers Cutting Back on Household Expenses in the Last 12 Months, 2022 (percent of consumers)
- Table | Types of Household Expenses Cut Back on in the Last 12 Months, 2022 (percent of consumers)
- Table | Consumer Spending on "Extras", 2023 (percent of consumers)
- Many Consumers Are Concerned about Inflation and Rising Food Prices
- Overview and Market Trends
- Highlights
- Outlook for Children's Food and Beverage Market
- Table | Children's Food and Beverage Market, 2017-2022, 2023E (billion dollars)
- Table | Children's Food and Beverage Market, 2023E, 2024P-2028P(billion dollars)
- Home Baking Trends
- Chocolate Candy Trends
- Functional Food and Beverage Trends
- Table | Seeking Out and Willingness to Pay More for Functional Beverages by Presence of Children in HH, 2023
- "Hidden" Vegetables for Increased Nutrition Kids Will Love
- Trends in Online Grocery Shopping
- Recent Historical Trends
- Parents May Shop Online for Children's Food and Beverage Products
- Meal Kits and Meal Delivery Services
- Impulse Buying
- Convenient Meals Can Be the Ultimate Selling Point for Busy Consumers
- Grocery Prepared Meals
- Restaurant Meals, Including Takeout and Delivery
- Meal Delivery Services
- Thaw and Eat Foods
- Lunch/Snack Kits for Consumption On-the-Go or at School or Daycare
- Table | Household Use of Lunch or Snack Combinations/Kits in the Last 6 Months or in the Last 30 Days by Pre
- Table | Household Use of Lunch or Snack Combinations/Kits in the Last 6 Months by Brand, 2023 (percent of co
- Table | Frequency of Household Use of Lunch or Snack Combinations/Kits in the Last 30 Days, 2023 (percent of
- Food Allergies and Dietary Restrictions Are a Concern to Many Parents and Their Children
- Food Allergies, Celiac Disease, Gluten Intolerance, and Lactose Intolerance
- Other Food Intolerances and Negative Perceptions of Ingredients Lead to Wide Appeal for Allergy-Frie
- Prevalence in 2023
- Reported Food Allergies and Intolerances over Time
- Table | Prevalence of Food Allergies, Gluten Intolerance, and Lactose Intolerance, 2018 - 2023 (percent of c
- Food Allergies Are on the Rise
- At-Home Testing Increases Consumer Awareness and Can Lead to Diet Changes
- Food Preferences and Allergies/Intolerances
- Table | Foods that Consumers Generally Eat, Generally Don't Like, or Are Allergic or Intolerant/Sensitive to
- Purchases of Foods with Allergy-Friendly Labels
- Many Consumers Purchase Allergy-Friendly Foods for Reasons Other Than an Allergy or Intolerance
- Plant-Based and Plant-Forward Trends
- Definitions
- Plant-Based Eating and Sustainability Are Buzzwords Important to the General Public
- One-Fourth of Consumers Claim to Primarily Follow a Flexitarian Diet in 2023
- Parents Are More Likely to Follow Plant-Forward Diets
- Table | Following Plant-Forward Diets by Presence of Children in the Household, 2023 (percent of consumers)
- A "Reducetarian" Mindset is Growing Among Consumers Who Eat Animal Products (and It's Not Just Among
- Consumers with Children Are More Likely to Use Plant-Based Alternatives and Are More Open to Cultiva
- Clean Label and "Better-for-You" Trends
- Organic and Non-GMO
- Sugar-Free/No Sugar Added Products and Alternative Sweeteners
- Addition of Fruit, Seeds, "Ancient Grains", "Superfoods", and other Ingredients for Increased Nutrit
- Vegan/Plant-Based Products
- Keto, Paleo, Low-Carb, and High Protein Diets
- Table | Following Keto, Paleo, Atkins, South Beach, or Whole30 Diets; Buying Food Labeled High Protein or Lo
- Table | Following Keto, Paleo, or Low-Carb Diets; Keto, Paleo, High Protein, and Low-Carb High Priorities; L
- Gluten-Free Diets
- Table | Following Special Eating Habits due to Gluten Intolerance or Food Allergies; Buying Food Labeled as
- Table | Following a Gluten-Free/Wheat-Free Diet and High Gluten-Free/Grain-Free Food Priorities by Parenthoo
- Snacking Trends
- Most Consumers Snack Daily
- Preferred Types of Snacks
- Table | Preferred Types of Snacks, 2023 (percent of consumers)
- "Snackification" of Meals
- When Consumers Snack Throughout the Day
- What Consumers Snack on in the Morning and the Evening/Late Night
- Nutrients and Ingredients Sought by Consumers
- Protein Is the Most Popular Nutrient That People Try to Consume
- Sources Used to Consume Nutrients
- Consumers Report Increasing Consumption of Protein from Poultry and Whole-Plant Sources
- Functional Health Benefits
- Avoiding or Limiting Sugar Intake
- Reasons for Avoiding or Limiting Sugar Intake
- Sugar Continues to Be Preferred Over Low/No-Calorie Sweeteners
- Many Sweeteners Are Considered Unsafe by Consumers
- Avoiding or Limiting Sodium
- Information Consumers Seek Out on Nutrition Facts Labels
- Mindful and Intuitive Eating
- Definition
- How People Are Practicing Mindful and Intuitive Eating
- Dieting Activity
- Frequency of Feelings and Behaviors Associated with Mindful and Intuitive Eating Patterns
- Consumer Mindfulness Index
- Concerns about Food Waste
- Most Consumers Are Concerned about Food Waste
- How Consumers Reduce Food Waste
- Greater Concerns about Food Waste among Adults Living with Children
- Opportunities for Children's Foods
- Consumer Demographics
- Highlights
- Number of Children in the Household
- 2023
- Historical Trends
- Age of Children in the Household
- Parents and Those Living with Children in Their Household
- Trends by Gender
- Table | Parenthood and Presence of Children under 18 in the Household by Gender, 2023 (percent of consumers)
- Trends by Age Bracket/Generation
- Table | Parenthood and Presence of Children under 18 in the Household by Age Bracket, 2023 (percent of consu
- Table | Parenthood and Presence of Children under 18 in the Household by Generation, 2023 (percent of consum
- Patterns Based on Household Income
- Table | Parenthood and Presence of Children under 18 in the Household by Household Income Bracket, 2023 (per
- Home Ownership and Rental Trends
- Table | Parenthood and Presence of Children under 18 in the Household by Home Ownership or Rental, 2023 (per
- Patterns Based on Marital Status
- Table | Parenthood and Presence of Children under 18 in the Household by Marital Status, 2023 (percent of co
- Regional Differences
- Table | Parenthood and Presence of Children under 18 in the Household by Region, 2023 (percent of consumers)
- Urban, Suburban, and Rural Consumers
- Table | Parenthood and Presence of Children under 18 in the Household by Population Density of Residence Are
- Educational Attainment
- Table | Parenthood and Presence of Children under 18 in the Household by Educational Attainment, 2023 (perce
- Race/Ethnicity
- Table | Parenthood and Presence of Children under 18 in the Household by Race/Ethnicity, 2023 (percent of co
- Plant-Forward Consumers
- Table | Parenthood and Presence of Children under 18 in the Household by Types of Plant-Forward Eating, 2023
- Online Grocery Shoppers
- Table | Parenthood and Presence of Children under 18 in the Household by Online Grocery Shopping Habits, 202
- Trends by Gender
- Consumer Psychographics
- Highlights
- Priorities Placed on Food Characteristics
- All Consumers
- Table | Priorities Placed on Foods, 2023 (percent of consumers)
- Parents/Guardians
- Table | Priorities Placed on Foods, 2023 (percent of parents)
- All Consumers
- Attitudes of Parents
- Sugar, Sweeteners, and Low-Calorie Foods
- Table | Statements about Sugar, Sweeteners, and Low-Calorie Foods, 2023 (percent of consumers who strongly a
- Snacking
- Table | Statements about Snacking, 2023 (percent of consumers who agree)
- Table | Frequency of Snacking on Typical Weekdays and Weekends, 2023 (percent of consumers who agree)
- Cooking
- Table | Statements about Cooking, 2023 (percent of consumers who agree completely)
- Premium Foods and Novel Food Experiences
- Table | Statements about Premium and Novel Food Preferences, 2023 (percent of consumers who agree completely
- Food Nutrition and Healthy Food
- Table | Statements about Food Nutrition and Healthy Food, 2023 (percent of consumers who agree completely)
- Being Busy and Seeking Out Convenient Foods
- Table | Statements about Being Busy and Seeking out Convenient Foods, 2023 (percent of consumers who agree c
- Sugar, Sweeteners, and Low-Calorie Foods
- Children's Food Habits
- Table | Statements about Children's Eating Habits, 2023 (percent of parents/guardians with children under 18
- Table | Statements about Children's Food Choice and Preparation Habits, 2023 (percent of parents/guardians w
Many parents seek out packaged foods with a health halo for their children, such as plant-based, no artificial ingredients, low sugar, and high protein.
Convenience is one of the driving factors of growth in the children’s food and beverage market, as parents with children are especially busy.
The retail market for children’s food and beverage products experienced average annual growth of 8.5% from 2018 to 2023.